Understanding Life Insurance Beneficiary Designations: What It Means When Reno is the Beneficiary of a Policy on Sula’s Life
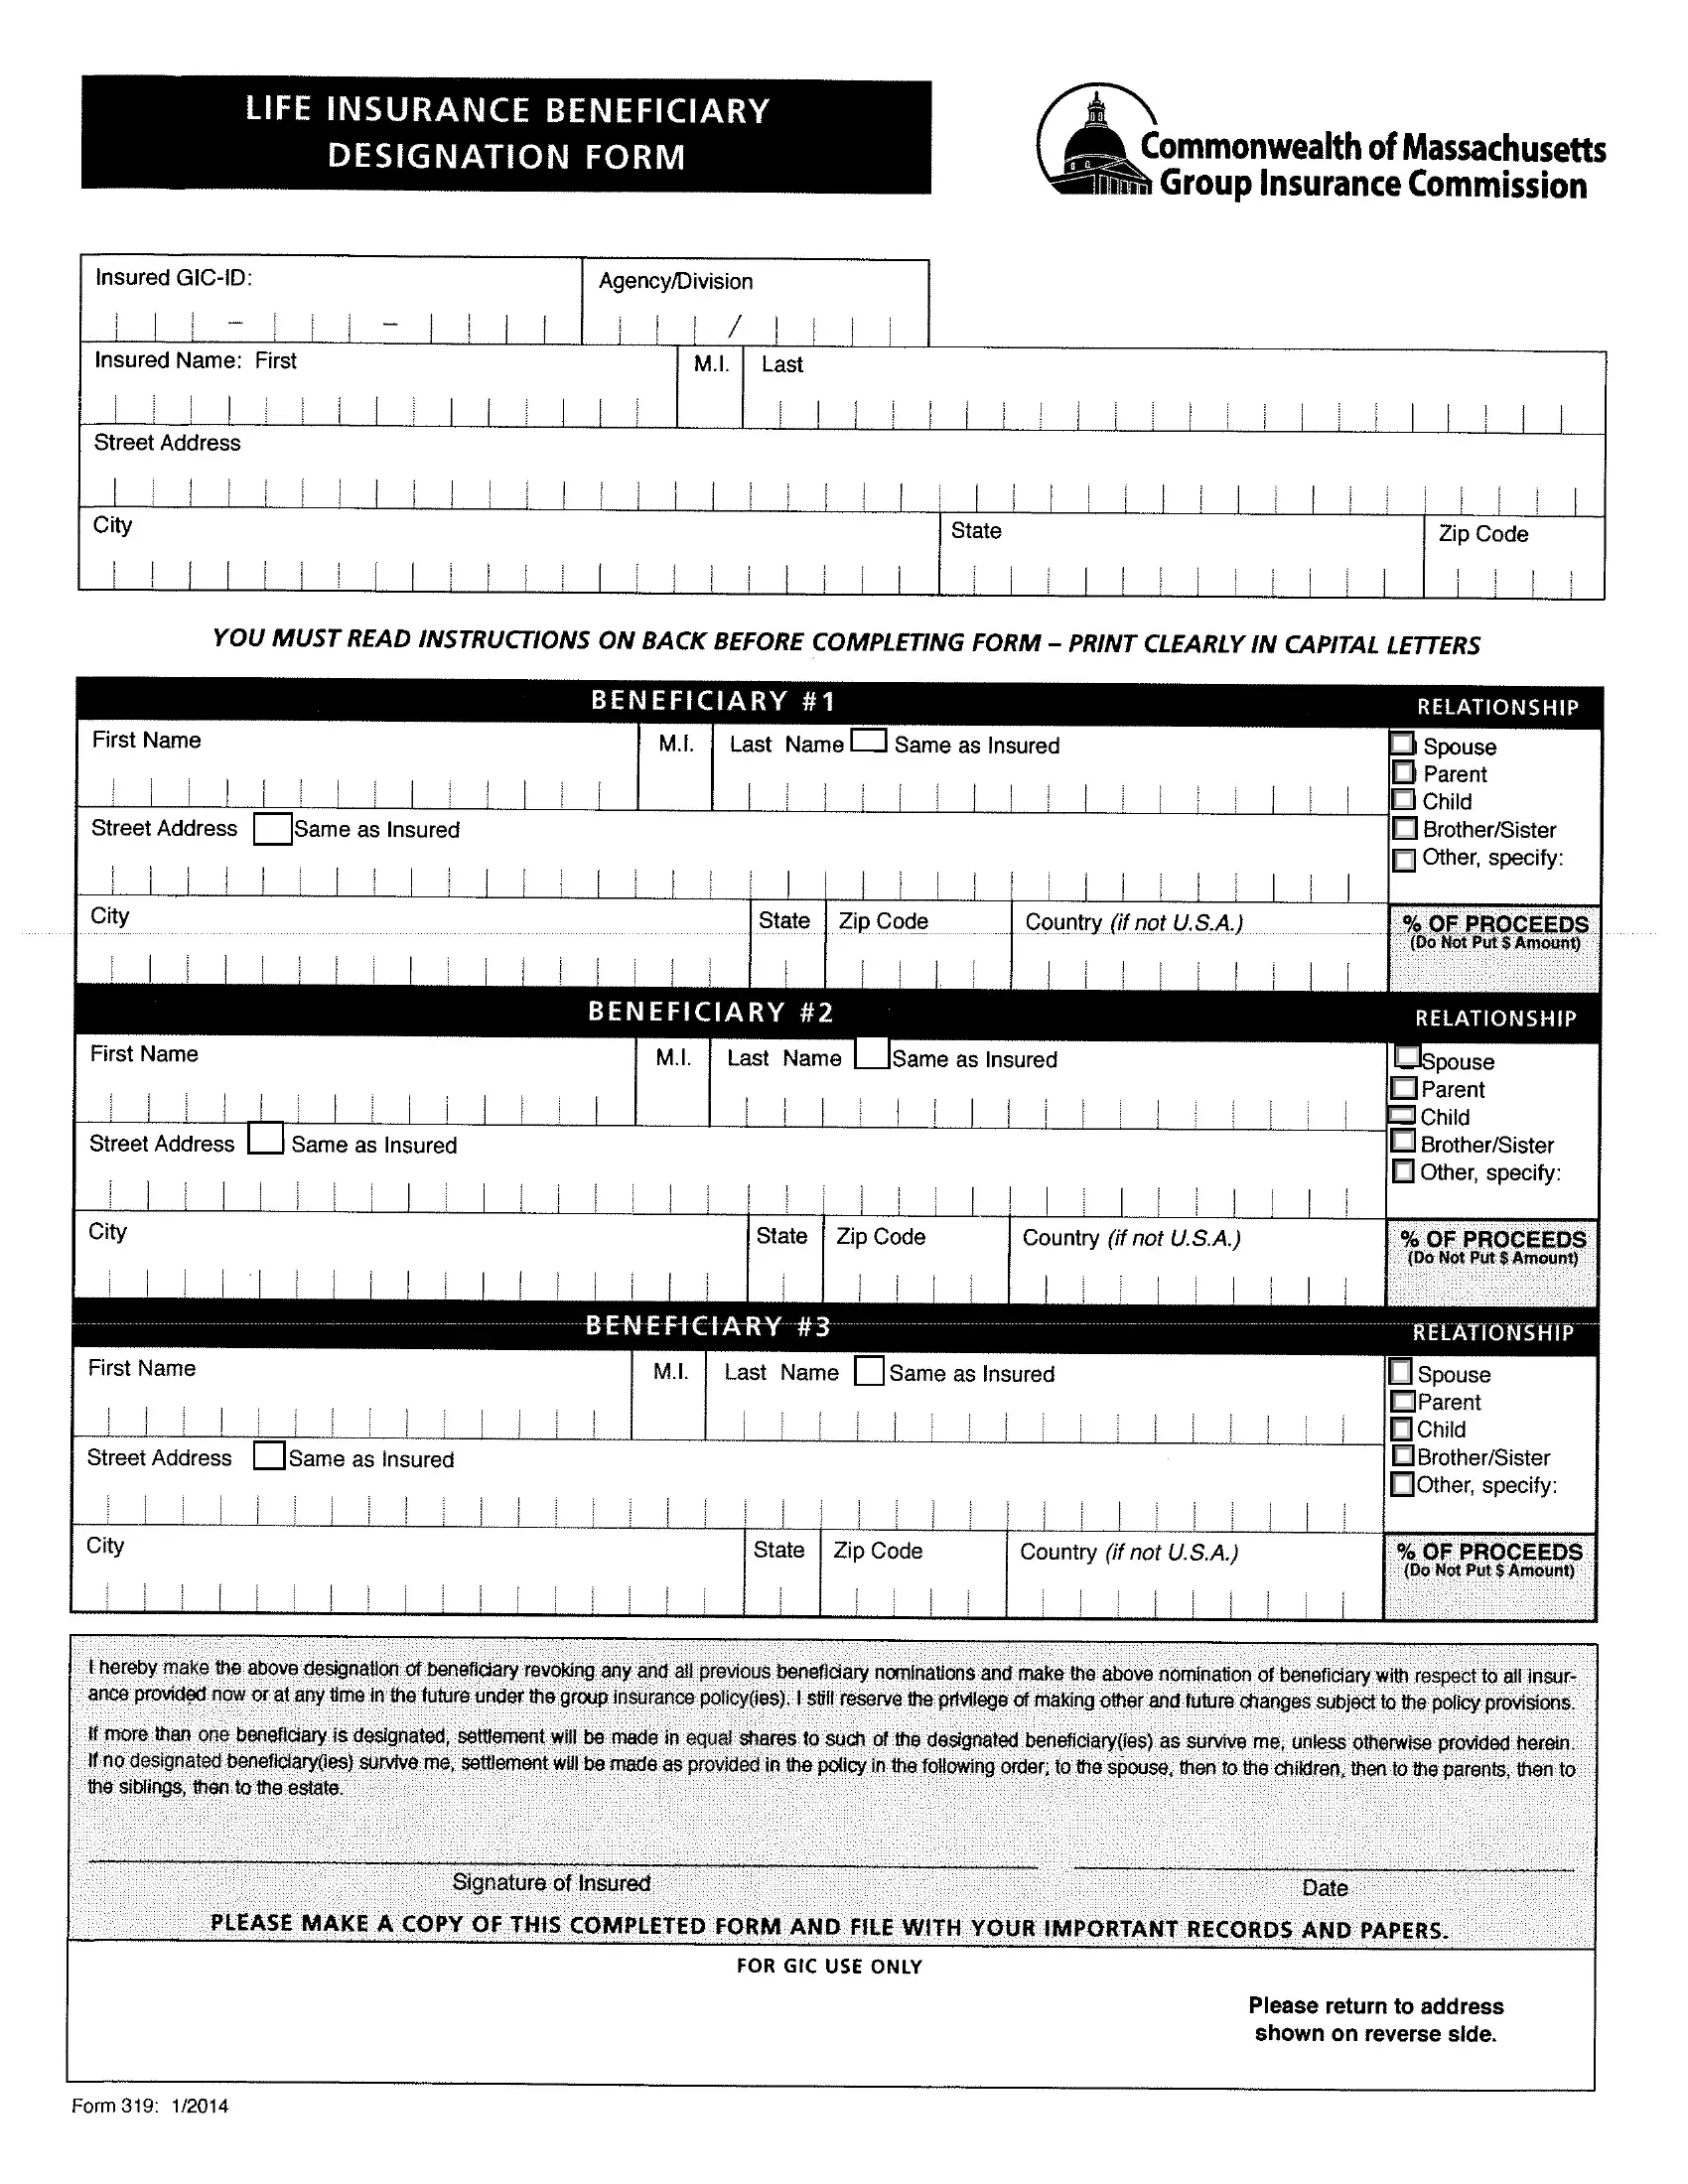
When Reno is designated as the beneficiary of a life insurance policy on Sula’s life, it means that Reno holds the legal right to receive the policy’s death benefit payout upon Sula’s passing. This financial arrangement involves specific contractual obligations, legal rights, and administrative procedures that dictate how and when the funds will be transferred from the insurance carrier to the designated individual.
Navigating the financial and legal landscape of life insurance beneficiary designations requires a clear understanding of contract law, estate planning principles, and insurer administrative processes. Whether you are setting up a policy, reviewing existing coverage, or preparing for future administrative steps, understanding the mechanics of a beneficiary designation ensures that the policyholder's intentions are successfully fulfilled without unnecessary legal or financial friction.
The Fundamentals of Life Insurance Beneficiary Designations
A life insurance policy is a binding legal contract between the policyowner (who may or may not be the insured person) and the insurance company. Within this contract, the beneficiary designation represents a core directive instructing the insurer on how to distribute the financial proceeds when the insured individual dies.
When Sula secures a life insurance policy—assuming Sula is both the insured and typically the owner—she names Reno to receive the financial payout. Reno does not own the policy while Sula is alive; Reno holds what is known as a contingent or primary expectancy interest. This means Reno has no right to borrow against the policy, change coverage amounts, or alter the policy terms while Sula is living, unless ownership rights were explicitly transferred—a separate legal action from merely naming a beneficiary.
Primary Versus Contingent Beneficiaries
Understanding the distinction between beneficiary tiers is critical for proper estate and risk planning.
- Primary Beneficiary: Reno, in this scenario, is designated as the primary beneficiary. This means Reno stands first in line to receive 100% of the policy proceeds (or a specific percentage if multiple primary beneficiaries are named) upon Sula's death.
- Contingent Beneficiary: A contingent (or secondary) beneficiary is named to receive the death benefit only if the primary beneficiary—Reno—predeceases Sula or disclaims the inheritance. If no contingent beneficiary is named and Reno passes away before Sula, the death benefit typically reverts to Sula’s estate, subjecting the funds to probate proceedings.
Legal and Contractual Obligations Governing the Policy
Life insurance contracts operate under strict state insurance laws and contract statutes. The designation of Reno as a beneficiary must adhere to the formal requirements outlined by the issuing insurance carrier.
To ensure the designation is legally binding, Sula must complete the insurer’s official change-of-beneficiary form or execute the designation during the initial application process. Verbal agreements, unfulfilled promises, or informal notes written in a personal journal generally carry no legal weight in insurance claims processing. Courts consistently rule that the insurer is obligated to pay the beneficiary explicitly named in the official, unrevoked documents currently on file with the company's home office at the time of the insured's death.
Revocable Versus Irrevocable Designations
- Revocable Beneficiary: By default, most life insurance beneficiary designations are revocable. This means Sula retains the right to remove or replace Reno as the beneficiary at any time during her life without Reno's consent or knowledge.
- Irrevocable Beneficiary: If Sula designates Reno as an irrevocable beneficiary (often done in the context of divorce settlements, business agreements, or specific financial loans), Sula cannot change the beneficiary, surrender the policy, or borrow against its cash value without Reno's explicit, written consent.

Financial and Tax Implications for the Beneficiary
For Reno, receiving a life insurance payout carries specific financial realities, particularly regarding income taxes, estate taxes, and administrative timelines.
In most jurisdictions, life insurance death benefits paid to a named individual beneficiary are income tax-free. When Sula passes away and the claim is processed, the lump sum distributed to Reno is generally not subject to federal or state income taxes. However, if the policy has accumulated significant cash value and has been earning interest between the date of death and the date of payout, that accumulated interest portion may be taxable as ordinary income.
Comparison of Payout Methods Available to Reno
Insurance companies typically offer several options for how Reno can receive the death benefit funds. Selecting the right payout method depends on immediate financial needs and long-term wealth management goals.
| Payout Method | Description | Pros | Cons |
|---|---|---|---|
| Lump-Sum Payment | A single, immediate check or wire transfer for the full death benefit amount. | Complete financial control; no ongoing administrative fees. | Risk of impulsive spending or poor immediate management. |
| Retained Asset Account | Funds are placed in a secure interest-bearing account managed by the insurer, accessed via checkbook. | Immediate liquidity with time to plan investments; earns modest interest. | Interest rates may lag behind other market investments. |
| Structured Settlement / Annuity | The payout is distributed in regular, periodic installments over a specified term or lifetime. | Provides steady, predictable income; prevents rapid depletion of funds. | Reduced financial flexibility if unexpected large expenses arise. |
The Claims Process: What Reno Must Do When Sula Passes Away
When Sula passes away, the transfer of the life insurance proceeds does not happen automatically. Reno must actively initiate the claims process with the insurance carrier. Navigating this process efficiently requires gathering specific documentation and understanding insurer requirements.
Step-by-Step Claims Procedure
- Locate Policy Documents: Reno should locate the original policy schedule, policy number, and contact information for the insurance company or the insurance agent who handled the account.
- Obtain Death Certificates: Order multiple certified copies of Sula’s death certificate from the vital statistics office or local health department. The insurance company will require an official certified copy to process the claim.
- Contact the Insurance Carrier: Notify the insurer’s claims department of the insured's passing. Request the specific claimant's statement form and instructions.
- Complete the Claimant’s Statement: Reno must fill out the required paperwork accurately, providing proof of identity and selecting the preferred payout method (such as a lump sum or retained asset account).
- Submit Documentation: Send the completed claimant's statement, the certified death certificate, and any additional requested documents securely to the insurer.
- Acknowledge Payout: The insurer will review the claim, verify policy status, check for any outstanding policy loans or unpaid premiums, and disburse the remaining death benefit to Reno.
Common Pitfalls and Dispute Resolution
While the process of paying a death benefit to a named beneficiary is typically straightforward, complications can arise that delay disbursement or lead to legal disputes.
1. Outdated Beneficiary Designations
A common issue occurs when life events—such as marriage, divorce, or the birth of children—change a policyholder's intentions, but the official policy paperwork is never updated. If Sula named Reno years ago and intended to change the beneficiary later but failed to submit the proper forms to the insurance company, the insurer is legally bound to pay Reno, regardless of subsequent oral promises or wills.
2. Minor Beneficiaries and Legal Guardianship
If Reno were a minor (under the age of majority), an insurance company cannot legally disburse a large death benefit directly to a child. In such cases, the court would typically need to appoint a legal guardian or property custodian to manage the funds until the minor reaches the age of majority, introducing court costs, delays, and judicial oversight. (This highlights why designating an adult like Reno, or establishing a proper trust, is critical when naming beneficiaries).
3. Interpleader Actions
If multiple parties contest the validity of the beneficiary designation—such as family members claiming Sula was subjected to undue influence or that the designation was fraudulent—the insurance company may file an interpleader action. In this legal procedure, the insurer deposits the disputed funds with the court, stepping out of the dispute and leaving Reno and the contesting parties to litigate the matter before a judge.
Professional Advice and Long-Term Planning
Life insurance planning intersects heavily with estate law, taxation, and family dynamics. Because individual circumstances vary widely based on jurisdiction, policy type (term versus permanent), and overall estate size, consulting with qualified professionals is essential.
Policyowners like Sula benefit from consulting estate planning attorneys and certified financial planners (CFPs) to ensure that beneficiary designations align harmoniously with wills, trusts, and power-of-attorney documents. Similarly, beneficiaries like Reno should consider consulting a fiduciary financial advisor upon receiving a significant payout to develop a tax-efficient wealth preservation strategy.
Image Gallery
Select an image to open it in a new tab.
Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
