Understanding the New Driver Average Car Insurance Cost: What to Expect and How to Save
Securing car insurance as a new driver typically costs significantly more than the national average, often ranging from $2,500 to over $4,000 annually in the United States, depending primarily on the driver's age, location, and the vehicle being insured. Because insurance companies base their rates on statistical risk, individuals with limited driving history present an unknown variable to underwriters. Without a documented track record of safe driving, carriers price policies to account for the heightened statistical probability of accidents. Navigating these costs requires understanding the structural components of auto insurance premiums, recognizing the external variables that influence pricing, and implementing proactive strategies to lower monthly or annual expenses.
Why New Drivers Face Higher Insurance Premiums
The foundational principle of car insurance pricing is risk assessment. Insurance companies analyze vast datasets compiled over decades to determine the likelihood that a specific policyholder will file a claim. When an individual receives their driver's license, they enter the market with a blank slate—a condition that actuaries treat with financial caution.
Statistically, inexperienced drivers are involved in a disproportionate number of collisions during their first few years on the road. Factors such as delayed hazard recognition, overconfidence, and lack of defensive driving instincts contribute to this trend. Consequently, carriers mitigate their financial exposure by charging higher rates. This surcharge is often referred to as a "inexperienced driver fee" or is baked directly into the base risk tier assigned to the policy.
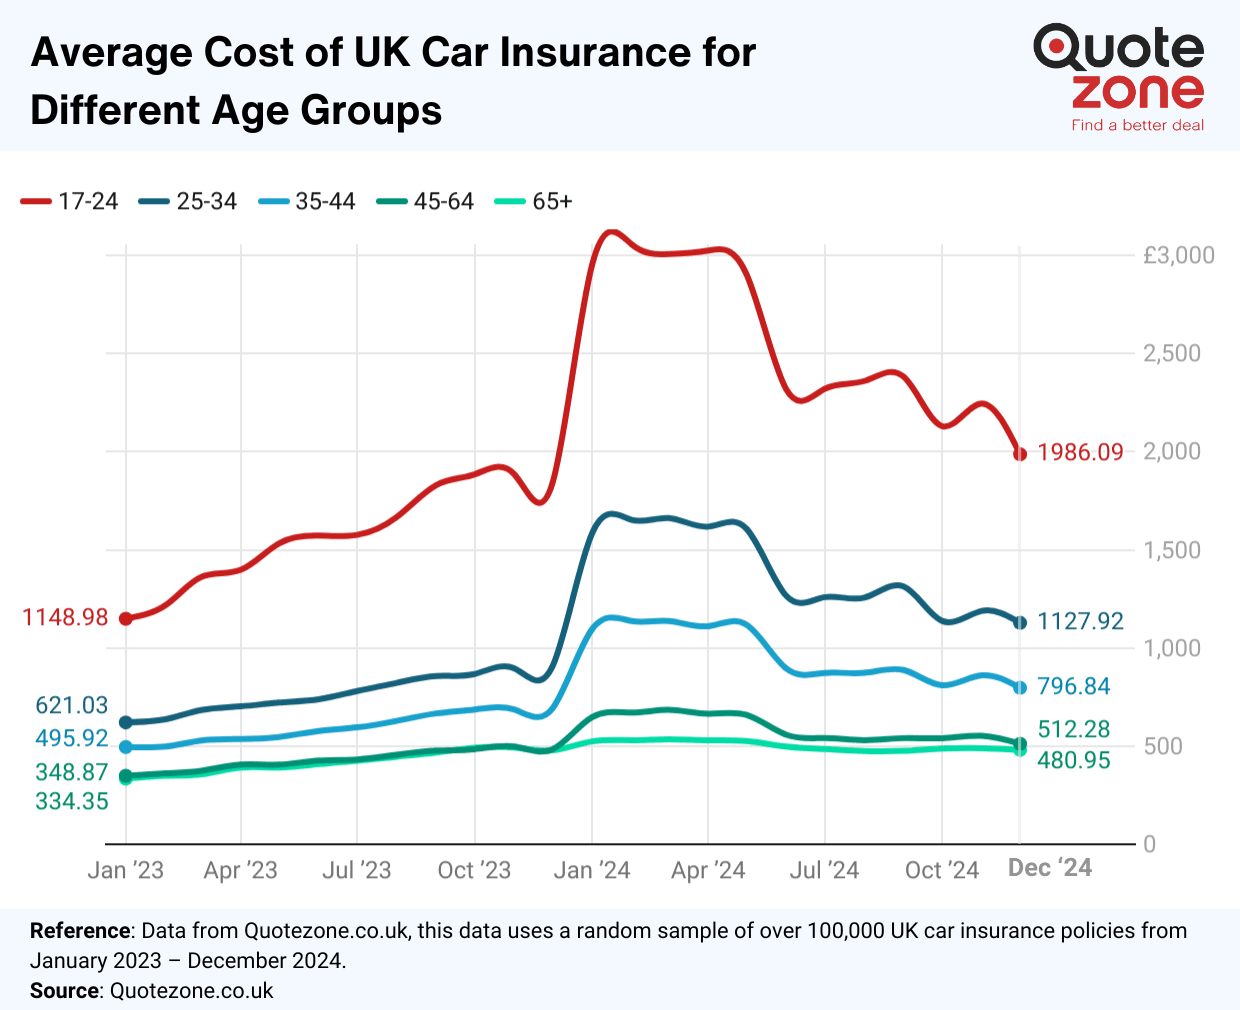
Furthermore, younger new drivers face an even steeper pricing curve. A teen driver securing a standalone policy will almost always see much higher quotes than an adult who is getting their license for the first time at age thirty. While both are new drivers, age-related risk correlations compound the lack of driving history, pushing premiums to their highest thresholds.
Key Factors Influencing the Cost of Insurance for New Drivers
Several distinct variables dictate the exact price a new driver will pay for coverage. Understanding these elements can help prospective policyholders anticipate costs and identify areas where they can exercise some control.
Age and Driving Experience
Age remains one of the most heavily weighted rating factors in the insurance industry. Teenagers and drivers under the age of 25 consistently pay the highest rates. An adult new driver, however, may benefit slightly from age-related maturity metrics, though their lack of a motor vehicle record (MVR) will still result in elevated premiums compared to seasoned drivers.
Geographic Location
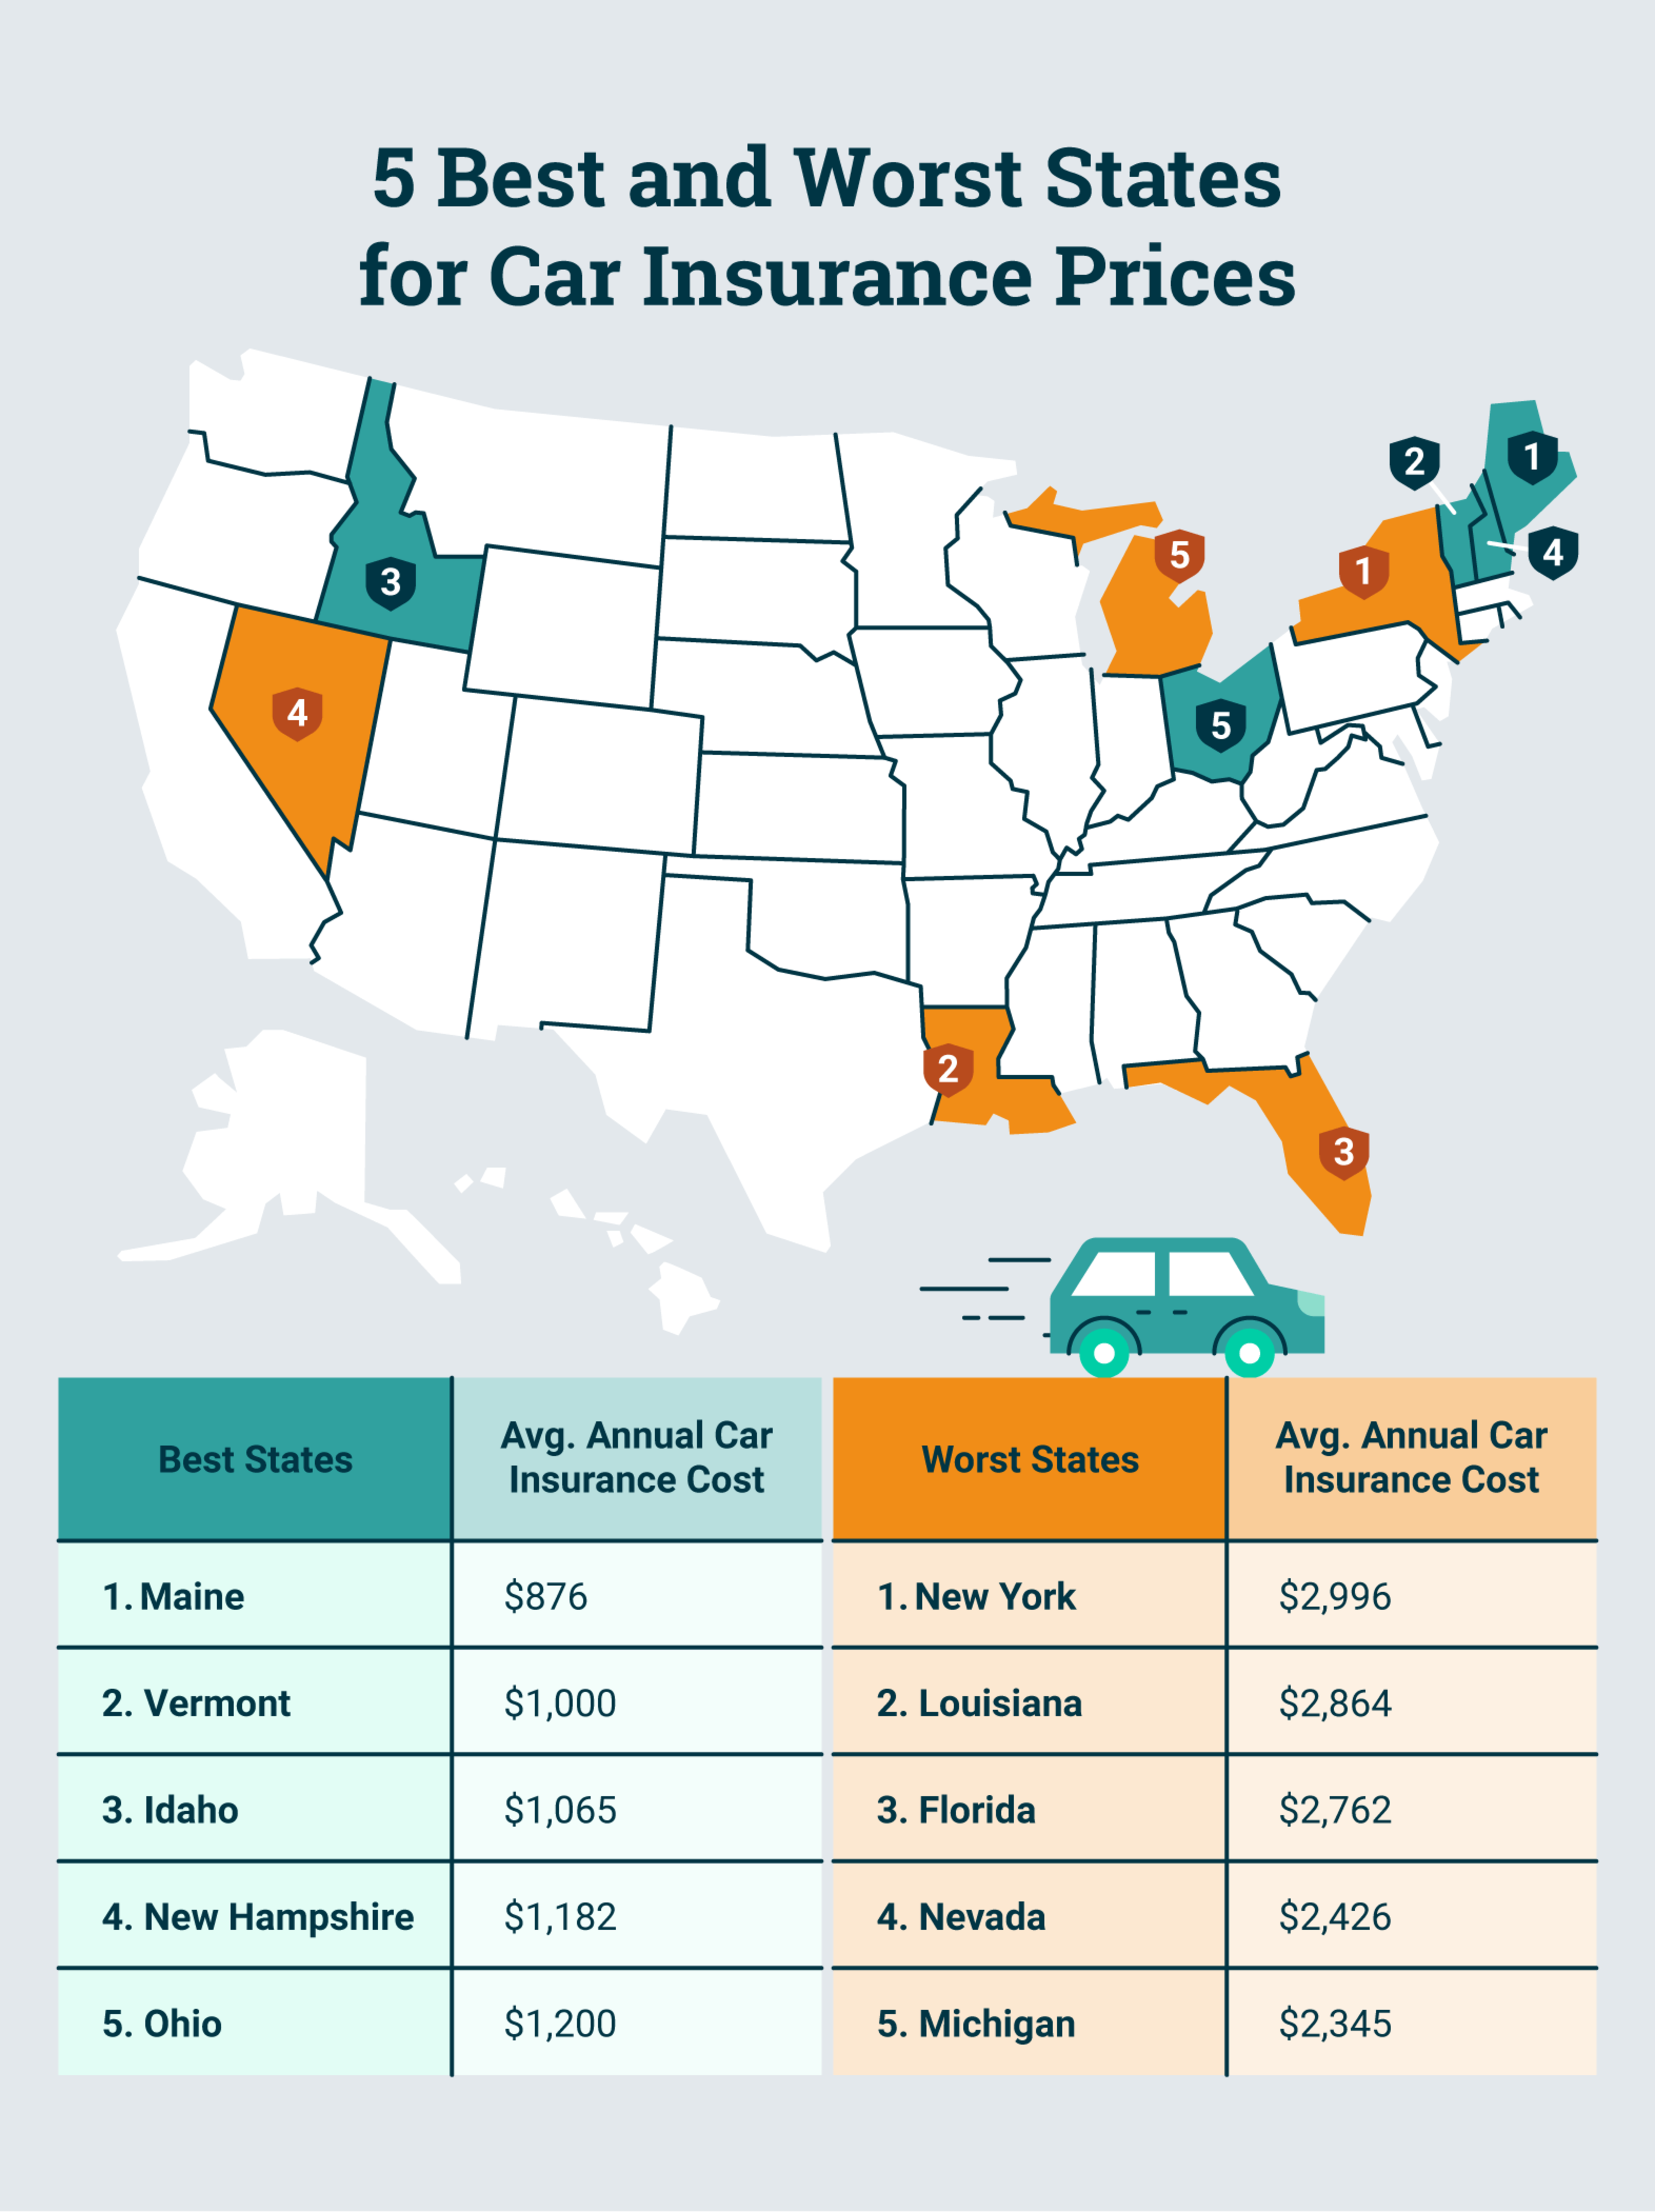
Where a vehicle is parked, registered, and primarily driven plays a massive role in insurance pricing. Urban areas with heavy traffic congestion, higher rates of vehicle theft, and a greater frequency of accidents yield more expensive insurance premiums. Conversely, rural areas with lower traffic density generally feature cheaper insurance costs. State-specific regulations also dictate baseline costs; some states mandate higher minimum liability limits or implement no-fault insurance systems that naturally increase average premiums.
Vehicle Make, Model, and Year
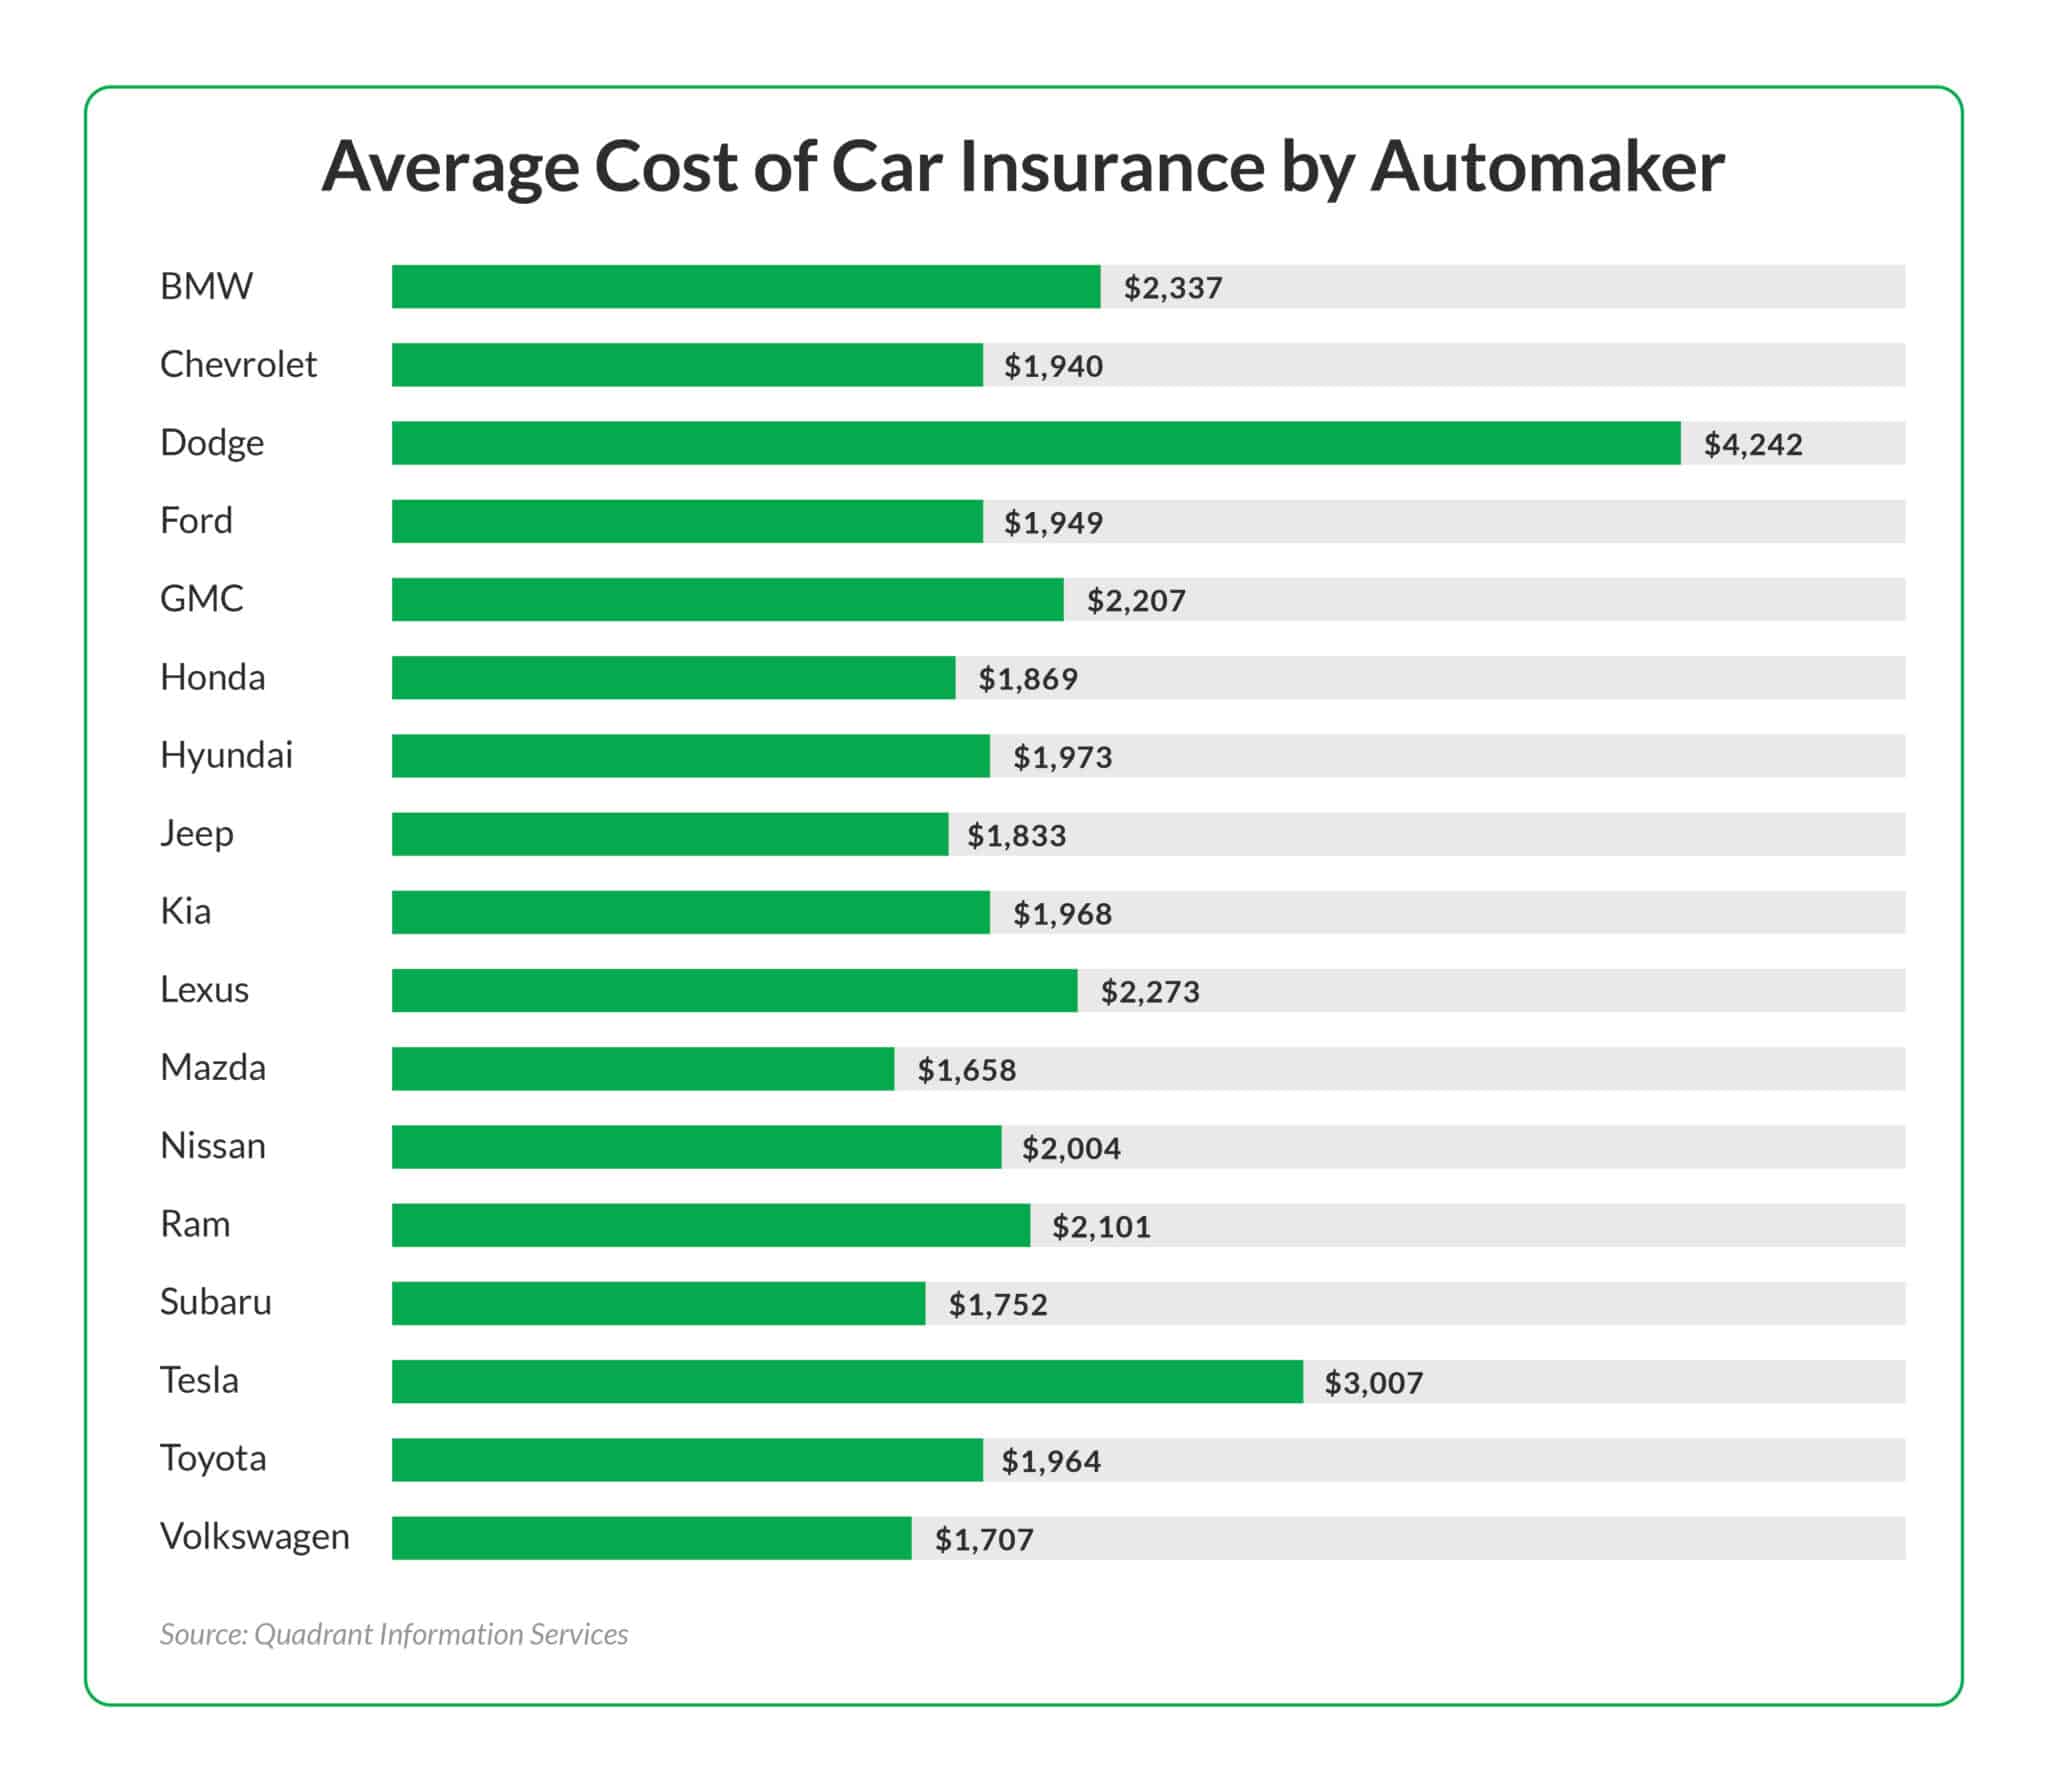
The type of car being insured directly impacts the cost of coverage. Vehicles with high safety ratings, robust anti-theft devices, and affordable replacement parts are cheaper to insure. On the other hand, sports cars, luxury vehicles, and large SUVs with high horsepower ratings attract higher premiums. For new drivers, purchasing an older, reliable sedan is a proven method to keep insurance costs manageable.
Coverage Levels and Deductibles
The extent of protection chosen by the driver will alter the bottom line. Opting for state-minimum liability coverage is the cheapest route upfront, but it leaves the driver financially vulnerable if they cause an accident that damages their own vehicle or injures others. Comprehensive and collision coverage, which protects against theft, weather events, and at-fault collisions, increases the premium significantly, as do lower deductibles.
Average Cost Breakdown by Segment
Because insurance averages fluctuate based on demographic and regional data, examining standard cost estimates across different new driver profiles provides a clearer picture of market expectations.
| Driver Profile / Scenario | Average Annual Cost Range | Key Contributing Factors |
|---|---|---|
| Teen Driver (Ages 16-19) on Own Policy | $3,500 – $5,500+ | Zero driving experience, highest statistical risk bracket, high liability exposure. |
| Teen Driver Added to Family Policy | $1,500 – $2,500 (Increase to existing bill) | Shared risk pool, multi-car discounts, established household insurance history. |
| Adult New Driver (Ages 25+) | $2,000 – $3,500 | Mature decision-making profile, but completely absent motor vehicle record. |
| New Driver with State-Minimum Coverage | $1,200 – $2,000 | Bare-minimum protection limits, high out-of-pocket exposure during claims. |
| New Driver with Full Coverage (Comprehensive/Collision) | $2,500 – $4,500+ | Protection for the insured vehicle, mandatory if the car is financed or leased. |
Note: These ranges serve as broad market estimates based on national averages. Individual quotes will vary significantly based on ZIP code, credit score (where permitted by law), and specific policy selections.
Strategies to Lower Car Insurance Costs for New Drivers
While high initial rates can feel discouraging, new drivers are not permanently locked into expensive premiums. Over time, as driving history accumulates and strategic discounts are applied, costs generally decline.
Join an Existing Household Policy
For younger new drivers, the most cost-effective approach is almost always joining a parent's or guardian's existing auto insurance policy rather than purchasing a standalone policy. Insurers view household pools as lower risk because the primary policyholder has an established history, and multi-car discounts often offset a portion of the added cost of a new driver.
Complete a Defensive Driving Course
Many insurance providers offer discounts to new drivers who voluntarily complete an accredited defensive driving course or a state-approved driver's education program. These courses demonstrate a proactive commitment to safety and educate new drivers on hazard avoidance, potentially reducing premiums by 5% to 15%.
Maintain Good Grades (Student Discounts)
For high school and college students, maintaining a "B" average or a 3.0 GPA or higher can unlock "Good Student" discounts with major insurance carriers. Insurers have found a statistical correlation between academic diligence and responsible behind-the-wheel behavior.
Choose Telematics and Usage-Based Insurance
Many modern insurers offer telemetry programs—such as Progressive's Snapshot, State Farm's Drive Safe & Save, or Allstate's Drivewise—that track driving habits via a mobile app or a plug-in device. Safe driving behaviors, such as smooth braking, maintaining safe speeds, and avoiding nighttime driving or phone distraction, can earn new drivers substantial discounts that bypass the traditional penalty of lacking a long driving history.
Shop Around and Compare Quotes
Insurance rates vary wildly between competing carriers for the exact same coverage profile. Obtaining quotes from at least three different national and regional providers ensures that a new driver is not overpaying. Independent insurance brokers can also assist in scanning the market for carriers that specialize in high-risk or youthful driver segments.
Frequently Asked Questions
Why is car insurance so expensive for brand-new drivers?
Car insurance is expensive for new drivers because insurers lack historical data to evaluate their risk level. Without a driving record, underwriters must rely on demographic statistics, which show that inexperienced drivers are statistically more likely to be involved in accidents during their first few years on the road.
Is it cheaper for a new driver to be on their own policy or their parents' policy?
It is almost always significantly cheaper for a new driver to be added to an existing family or household policy. Standalone policies for inexperienced or young drivers carry maximum risk weightings, whereas household policies benefit from multi-car discounts and established loyalty histories.
How long do new drivers have to pay high insurance rates?
Typically, insurance rates begin to decrease significantly after the driver turns 25, provided they maintain a clean driving record free of accidents, traffic violations, and speeding tickets. Accumulating three to five years of documented clean driving is usually the milestone required to exit high-risk rating tiers.
Does the type of car I drive affect my insurance rates as a new driver?
Yes, the vehicle choice has a massive impact. Cars with high safety ratings, low repair costs, and moderate engine power are much cheaper to insure. Sports cars, luxury imports, and vehicles with high theft rates will dramatically inflate insurance premiums for a new driver.
Can a new driver lower their insurance without changing cars?
Yes. New drivers can lower their premiums by opting for higher deductibles, maintaining a clean driving record, bundling renters or homeowners insurance if applicable, participating in telematics monitoring programs, and taking defensive driving courses.
Next Actions and Recommendations
Navigating the expenses associated with a new driver average car insurance cost requires a methodical approach. Start by evaluating the specific vehicle being driven and consider whether trading down to a safer, more economical model makes financial sense. Next, request quotes from multiple providers while exploring discounts such as good student programs, defensive driving certifications, and telematics tracking. Finally, if the driver is young or part of a shared household, prioritize joining an established family policy to secure immediate group savings while building a clean, violation-free driving record over the coming years.
Image Gallery
Select an image to open it in a new tab.


Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
