Finding the cheapest auto liability insurance in NYC requires balancing New York State’s strict "no-fault" requirements with the high-risk nature of metropolitan driving. In 2026, the most affordable paths involve selecting minimum legal limits, maximizing defensive driving credits, and leveraging telematics programs from providers like GEICO, Progressive, and State Farm.
Understanding New York State Liability Insurance Requirements
Before searching for the lowest price, it is critical to understand what the law mandates. New York is a "no-fault" state, meaning your own insurance pays for your medical bills regardless of who caused the accident. However, liability insurance is specifically designed to protect you if you are sued or held responsible for damages to others.
As of 2026, the minimum liability requirements in New York remain structured around the "25/50/10" rule, supplemented by mandatory No-Fault (PIP) and Uninsured Motorist coverage.
Bodily Injury Liability
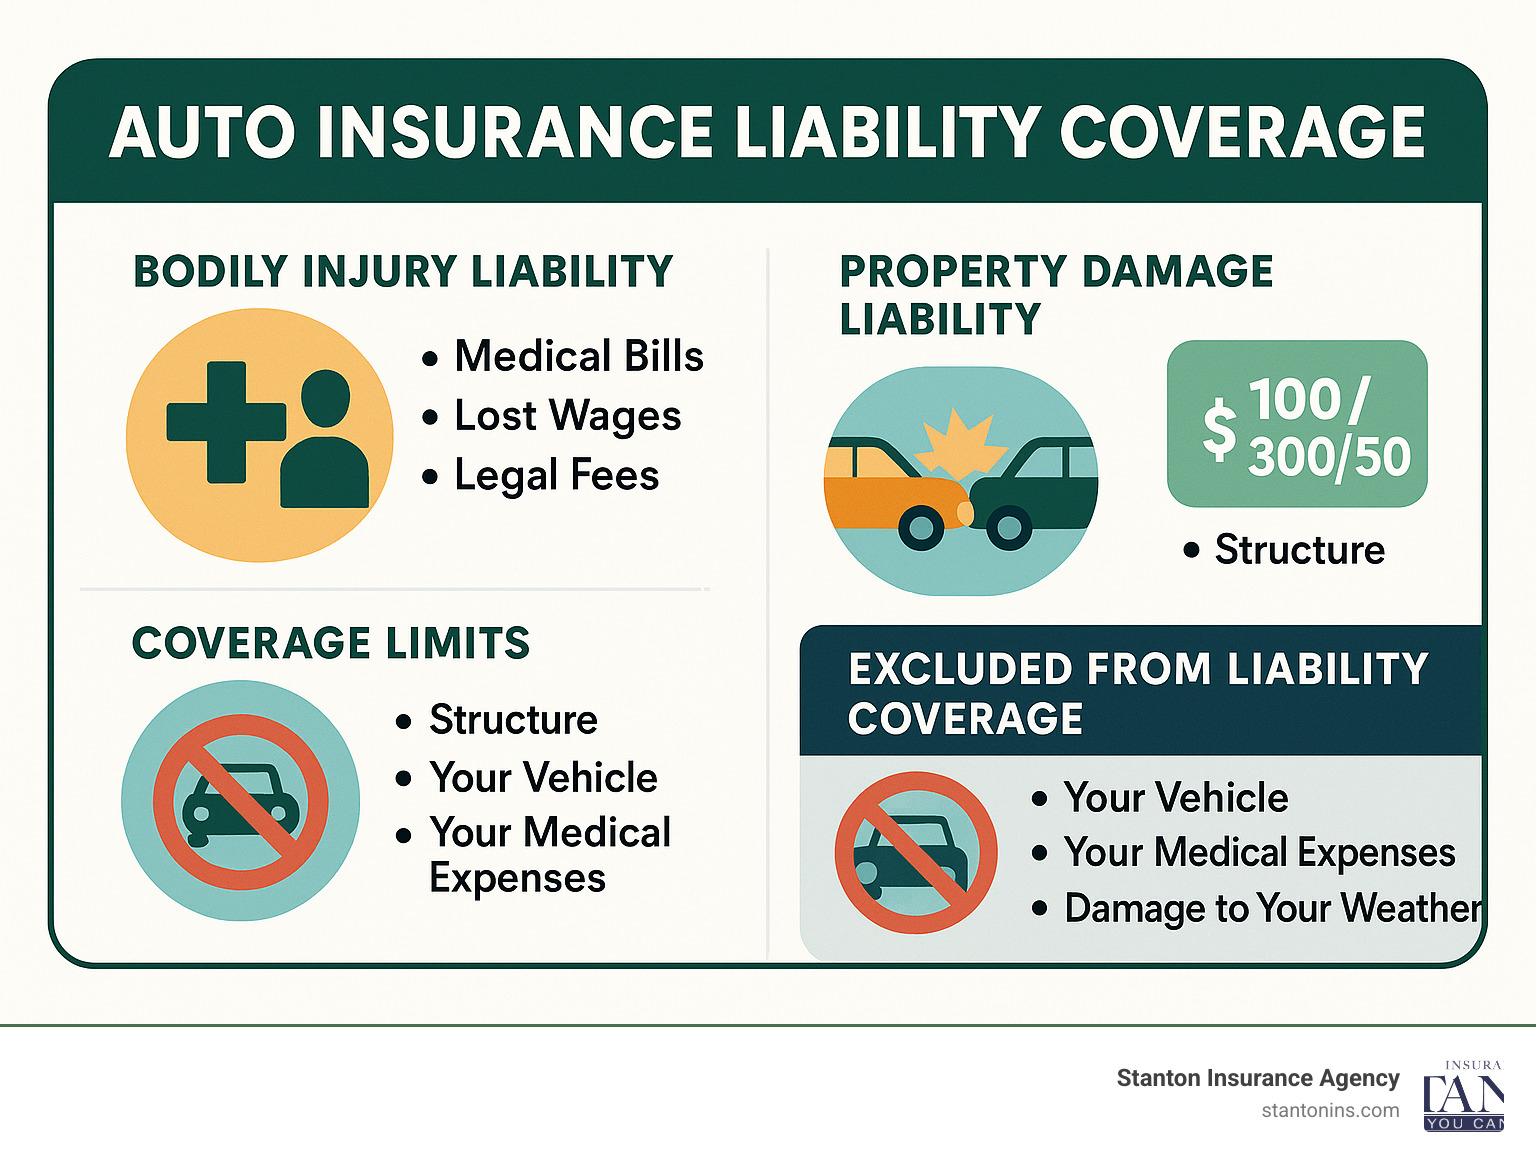
This coverage pays for the medical expenses, lost wages, and legal fees of other people injured in an accident where you are at fault.
- $25,000 for bodily injury to one person.
- $50,000 for bodily injury to all persons in one accident.
- $50,000 for death of one person.
- $100,000 for death of all persons in one accident.
Property Damage Liability
This covers damage to another person's vehicle or property (such as a fence or storefront). In a high-density area like NYC, where luxury vehicles and expensive infrastructure are common, the state minimum of $10,000 is often considered insufficient, yet it remains the floor for those seeking the absolute cheapest premium.
Personal Injury Protection (PIP)
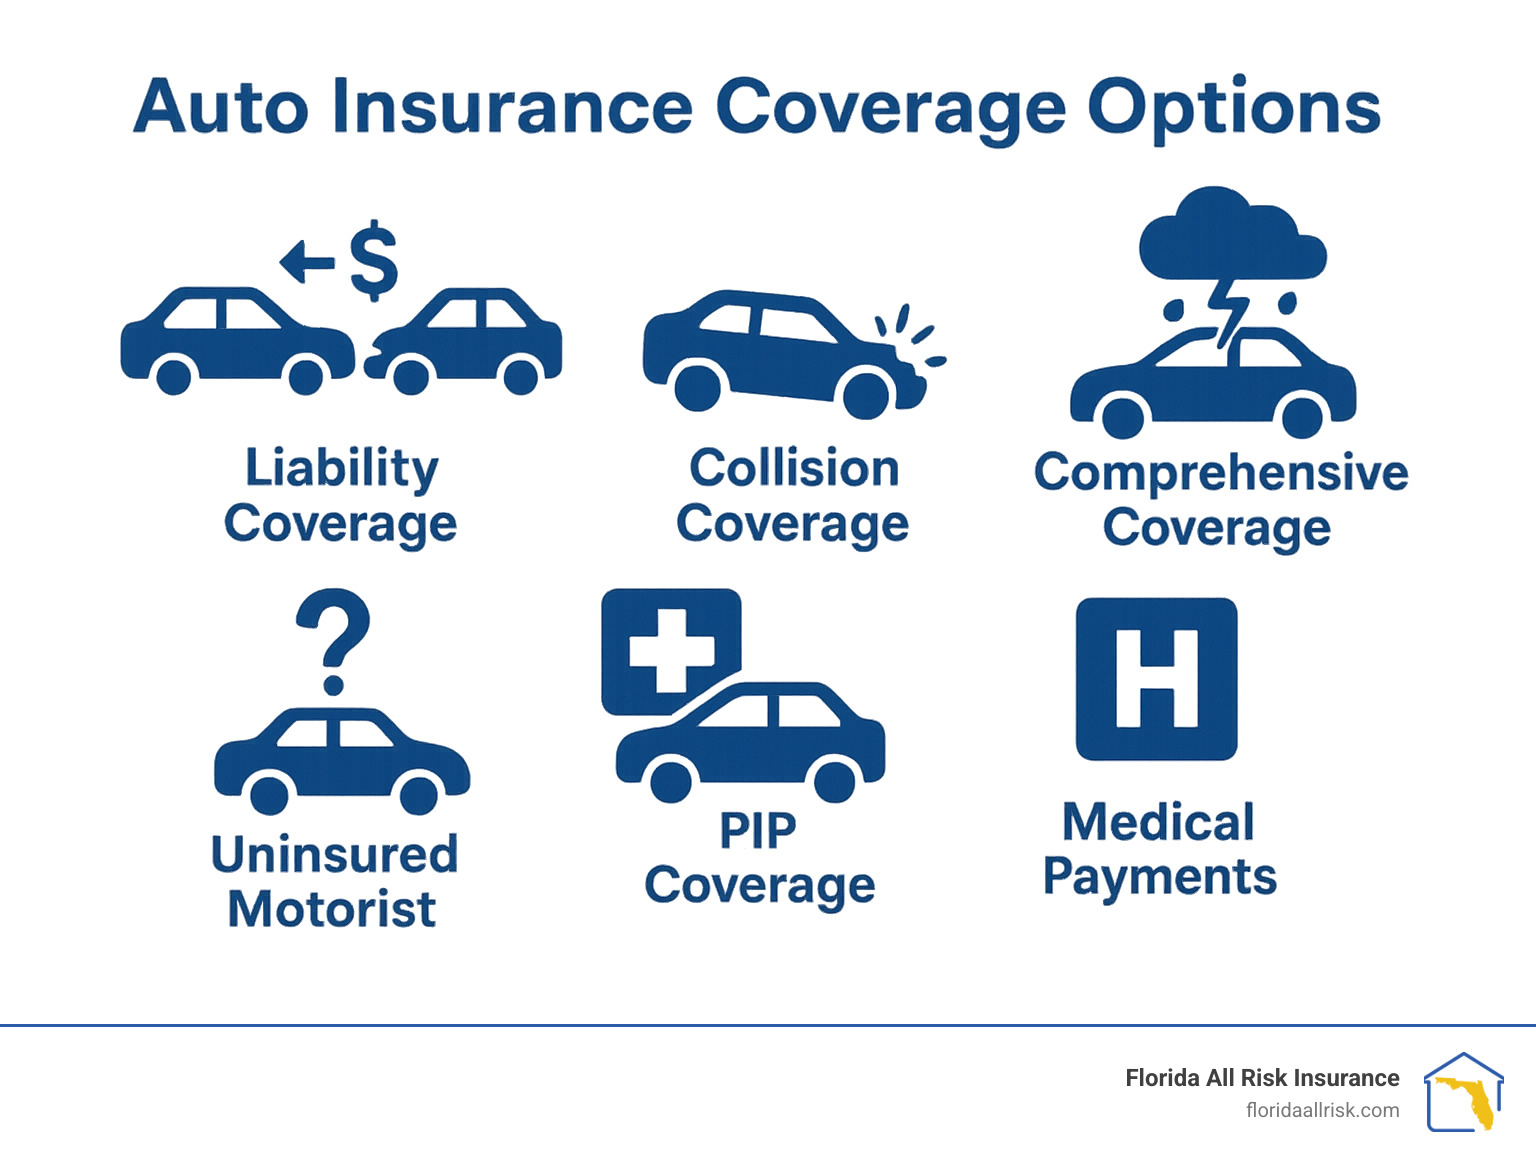
Often called "No-Fault" insurance, New York requires a minimum of $50,000 in PIP. This covers medical expenses, lost earnings, and other reasonable expenses for the driver and passengers of your vehicle, as well as pedestrians injured by your vehicle.
Uninsured Motorist Coverage
You must carry coverage that protects you if you are involved in an accident with a driver who has no insurance or a hit-and-run driver. This must match the $25,000/$50,000 limits of your bodily injury liability.
Why NYC Insurance Rates are Higher in 2026
The cost of auto insurance in the five boroughs—Manhattan, Brooklyn, Queens, the Bronx, and Staten Island—is significantly higher than the national and state averages. Several factors unique to the NYC ecosystem drive these costs:
- Population Density: The sheer volume of vehicles in NYC increases the statistical probability of collisions.
- Litigation Costs: New York’s legal environment is complex, and the cost of defending liability claims in the city is higher than in upstate regions.
- Insurance Fraud: Historically, NYC has struggled with "staged accident" rings, which forces insurers to raise premiums to cover the cost of fraudulent claims.
- Repair Costs: Labor rates in NYC auto body shops are among the highest in the country, increasing the payout for property damage claims.

Top Providers for Cheap Liability Insurance in NYC
While rates vary based on individual credit scores, driving history, and the specific zip code, certain companies consistently rank as the most affordable for liability-only coverage in the New York City market.
GEICO
GEICO remains a dominant force in the NYC market due to its direct-to-consumer model. By eliminating agent commissions, they often provide the lowest baseline rates for drivers with clean records. Their mobile app integration allows for quick adjustments to coverage, which is ideal for NYC residents who may frequently change their vehicle usage.
Progressive
Progressive is particularly competitive for drivers who may have a "less-than-perfect" record. Their Snapshot program—a telematics-based tool—is a primary way for NYC drivers to prove they are safe despite the chaotic city environment. If you drive infrequently or avoid peak traffic hours, Progressive can often beat competitors on liability pricing.
State Farm
While often perceived as a "premium" brand, State Farm’s massive network of local agents in neighborhoods like Astoria, Flushing, and Bay Ridge allows for personalized discounts that digital-only insurers might miss. They are frequently the cheapest option when "bundling" auto liability with renters or homeowners insurance, which is common for NYC residents.
Travelers and Erie
For those with excellent credit scores, Travelers and Erie (where available) offer highly competitive liability rates. They use sophisticated underwriting that rewards stability, such as long-term residency in the same apartment or a history of continuous insurance coverage.
Strategies to Lower Your NYC Liability Premium
In 2026, simply "shopping around" is not enough. You must actively manipulate the factors that insurers use to calculate your risk.
The Defensive Driving Credit (PIRP)
New York State offers the Point and Insurance Reduction Program (PIRP). By completing a DMV-approved defensive driving course, you are legally entitled to a 10% reduction in the base rate of your liability and collision insurance premiums for three years. In NYC, where liability premiums can exceed $2,000 annually, this 10% discount is substantial. Many of these courses are now available online and can be completed in a single afternoon.
Adjusting Your Deductibles and Limits
While we are discussing liability-only insurance (which typically doesn't have a deductible), you can lower costs by sticking strictly to the 25/50/10 limits. However, you should be aware that if you cause an accident resulting in $15,000 of damage to a Tesla in Manhattan, you will be personally responsible for the $5,000 gap if you only carry the $10,000 minimum.
Telematics and Usage-Based Insurance (UBI)
For many New Yorkers, the car sits in a garage or on the street for six days a week and is only used for weekend getaways or grocery runs. Usage-based insurance programs track your mileage and braking habits. If your annual mileage is low (under 5,000 miles), companies like Metromile (now part of Lemonade) or Root can offer liability rates that are significantly lower than traditional "flat-rate" policies.
Credit Score Optimization
In New York, insurance companies are permitted to use your credit-based insurance score to help determine your premium. Improving your credit score by even 50 points can move you into a different "tier" of risk, potentially saving you hundreds of dollars on your liability policy.
Comparing Estimated Annual Costs by Borough (2026 Projections)
The following table provides an estimated comparison of annual premiums for a "Standard" driver (30-year-old, clean record, 2020 sedan) seeking minimum New York liability limits.
| Borough | Estimated Annual Premium (Minimum Liability) | Primary Cost Driver |
|---|---|---|
| Manhattan | $1,850 - $2,400 | High property damage risk/Luxury vehicles |
| Brooklyn | $2,100 - $3,100 | High accident frequency/Vandalism rates |
| Queens | $1,700 - $2,500 | Commuter density/Street parking risks |
| The Bronx | $2,200 - $3,300 | Higher rates of uninsured motorists/Theft |
| Staten Island | $1,400 - $1,900 | Lower density/Suburban driving patterns |
Note: These figures are estimates for 2026 and can vary wildly based on specific zip codes and individual underwriting factors.
Common Pitfalls When Seeking the "Cheapest" Option
While the goal is to save money, certain mistakes can lead to long-term financial disaster or the cancellation of your policy.
Allowing a Coverage Lapse
New York is extremely strict regarding insurance lapses. The DMV is notified electronically the moment your policy is canceled. If you have even a one-day lapse in coverage, the DMV may suspend your vehicle registration and charge daily civil penalties. Furthermore, when you go to re-apply for insurance, a history of lapses will mark you as "high risk," significantly increasing your "cheap" premium.
Misrepresenting Your "Garaging Address"
Some NYC residents attempt to register their vehicles at a friend's or relative's house in Upstate New York or Pennsylvania to secure lower rates. This is considered insurance fraud. If you are involved in an accident and the insurer discovers you actually live and park the car in Bushwick rather than Buffalo, they can deny the claim entirely, leaving you personally liable for all damages.
Skipping "Supplemental Spousal Liability"
By law, New York insurers must offer Supplemental Spousal Liability insurance. This covers your spouse if they are injured in an accident where you are at fault. While declining this can save a few dollars on your premium, it removes a critical layer of protection for your family.
How to Verify an Insurer’s Credibility
In the quest for the lowest price, you may encounter small, specialized insurers you haven't heard of. Before signing a policy, verify their standing:
- AM Best Rating: Check the company’s financial strength. A rating of 'A' or better ensures the company has the capital to pay out claims.
- NY Department of Financial Services (DFS): Visit the NY DFS website to check for consumer complaint ratios. A company with the lowest price but a high complaint ratio may be difficult to deal with during the claims process.
Frequently Asked Questions
Can I get liability insurance in NYC if I have a foreign driver's license?
Yes, but it will be significantly more expensive. Most major insurers like Progressive or GEICO will accept a foreign license, but they will treat you as an "inexperienced driver." To lower the rate, you should obtain a New York State driver's license as soon as possible and provide a certified driving record from your home country if it shows a clean history.
Does "no-fault" mean I don't need liability insurance?
No. "No-fault" (PIP) only covers medical expenses and lost wages for you and your passengers. It does not cover the damage you do to someone else's car or the "pain and suffering" lawsuits that can arise if an injury exceeds the "serious injury threshold" defined by New York law. Liability insurance is mandatory to cover these specific risks.
Why did my NYC liability rate go up even though I had no accidents?
In 2026, insurance rates are influenced by "inflationary pressure" on medical costs and auto parts. Additionally, if your specific zip code saw a spike in accidents or claims overall, the insurer may perform a "territorial rate hike," affecting all policyholders in that area regardless of individual driving records.
Is it cheaper to buy insurance online or through an NYC broker?
For "standard" drivers, online portals usually offer the cheapest rates because they bypass broker fees. However, if you have a complicated history (e.g., multiple DUIs or high-point totals), a specialized local broker in NYC may have access to "non-standard" markets (like the New York Automobile Insurance Plan) that are not available through standard online quotes.
How does the New York Automobile Insurance Plan (NYAIP) work?
The NYAIP is the "assigned risk" plan for drivers who cannot find coverage in the voluntary market due to a poor driving record. While it is rarely the "cheapest" option, it is the guaranteed option for New Yorkers who are legally required to have insurance but have been rejected by private companies.
Final Recommendations for NYC Drivers
To secure the cheapest auto liability insurance in NYC for 2026, follow this specific checklist:
- Step 1: Complete an online NY DMV-approved defensive driving course to instantly shave 10% off your liability premium.
- Step 2: Gather quotes from at least three major "direct" providers (GEICO, Progressive, and State Farm) and one usage-based provider (Root or Lemonade) if you drive less than 7,000 miles a year.
- Step 3: Ensure your credit score is as high as possible before the "hard pull" by the insurance company.
- Step 4: Opt for "Paperless" billing and "Pay-in-Full" discounts, which can often reduce the total cost by another 5% to 8%.
- Step 5: Set an annual reminder to re-shop your policy. Loyalty rarely pays in the NYC insurance market; new customer discounts are often more substantial than renewal "benefits."
Disclaimer: The information provided in this article is for educational purposes only and does not constitute legal or financial advice. Insurance laws and rates are subject to change. Consult with a licensed insurance professional or the New York Department of Financial Services for specific guidance regarding your policy.
Image Gallery
Select an image to open it in a new tab.

Mateo Castillo
Decentralized Finance and E-Payments Strategist
