Finding the Best Texas City Auto Insurance for Everyday Drivers
Securing the right auto insurance in a Texas city requires balancing state-mandated liability minimums with the high-mileage realities of metropolitan commuting. For the everyday driver, the "best" policy is one that provides comprehensive coverage against uninsured motorists and weather-related perils while maintaining affordable premiums through local discounts and smart driving habits.
Understanding the Texas Auto Insurance Landscape
Texas operates under a "fault" system for auto insurance, meaning the party responsible for an accident is liable for the damages. As of 2026, the Texas Department of Insurance (TDI) mandates that all drivers carry minimum liability coverage, often referred to as 30/60/25 coverage. This means $30,000 for bodily injury per person, $60,000 for bodily injury per accident, and $25,000 for property damage per accident.
While these minimums satisfy legal requirements, they are rarely sufficient for the everyday driver navigating high-traffic urban corridors like those in Dallas, Houston, Austin, or San Antonio. Urban driving involves risks beyond just standard collisions, including higher rates of hit-and-runs, hail damage—which is prevalent across Texas—and flood risks during severe weather events. For the everyday driver, "best" is a designation that combines financial stability, responsive local claims handling, and digital accessibility.
Why "Minimum" Is Rarely Enough for Urban Commuters
In major Texas cities, the density of luxury vehicles and the frequency of traffic congestion increase the likelihood of expensive property damage claims. If you are found at fault in a collision involving a high-end vehicle, minimum coverage will be exhausted almost instantly, leaving you personally liable for the remaining balance.
Furthermore, Texas drivers should prioritize adding Uninsured/Underinsured Motorist (UM/UIM) coverage. According to state reporting, a significant percentage of drivers on Texas roads operate without active insurance. Relying on state minimums leaves you vulnerable; if an uninsured driver strikes your vehicle, you would have to rely on your own collision coverage—if you carry it—or pursue legal action, which is costly and time-consuming.
Key Factors for Selecting a Provider in 2026
When evaluating insurance providers for your daily commute, consider the following metrics of service quality:
- Claims Processing Efficiency: Look for companies that provide mobile app integration for digital claims filing. The ability to upload photos of vehicle damage directly via a smartphone can significantly expedite the initial assessment.
- Financial Strength: Check the AM Best or S&P rating of the insurer. You want a company with a high capital reserve to ensure they can pay claims during large-scale catastrophe events, such as widespread hail storms that often impact entire Texas neighborhoods.
- Customer Service Accessibility: Does the company offer 24/7 support? For someone driving to work every day, the ability to reach an agent or digital portal at odd hours is vital if a mechanical breakdown or incident occurs during a commute.
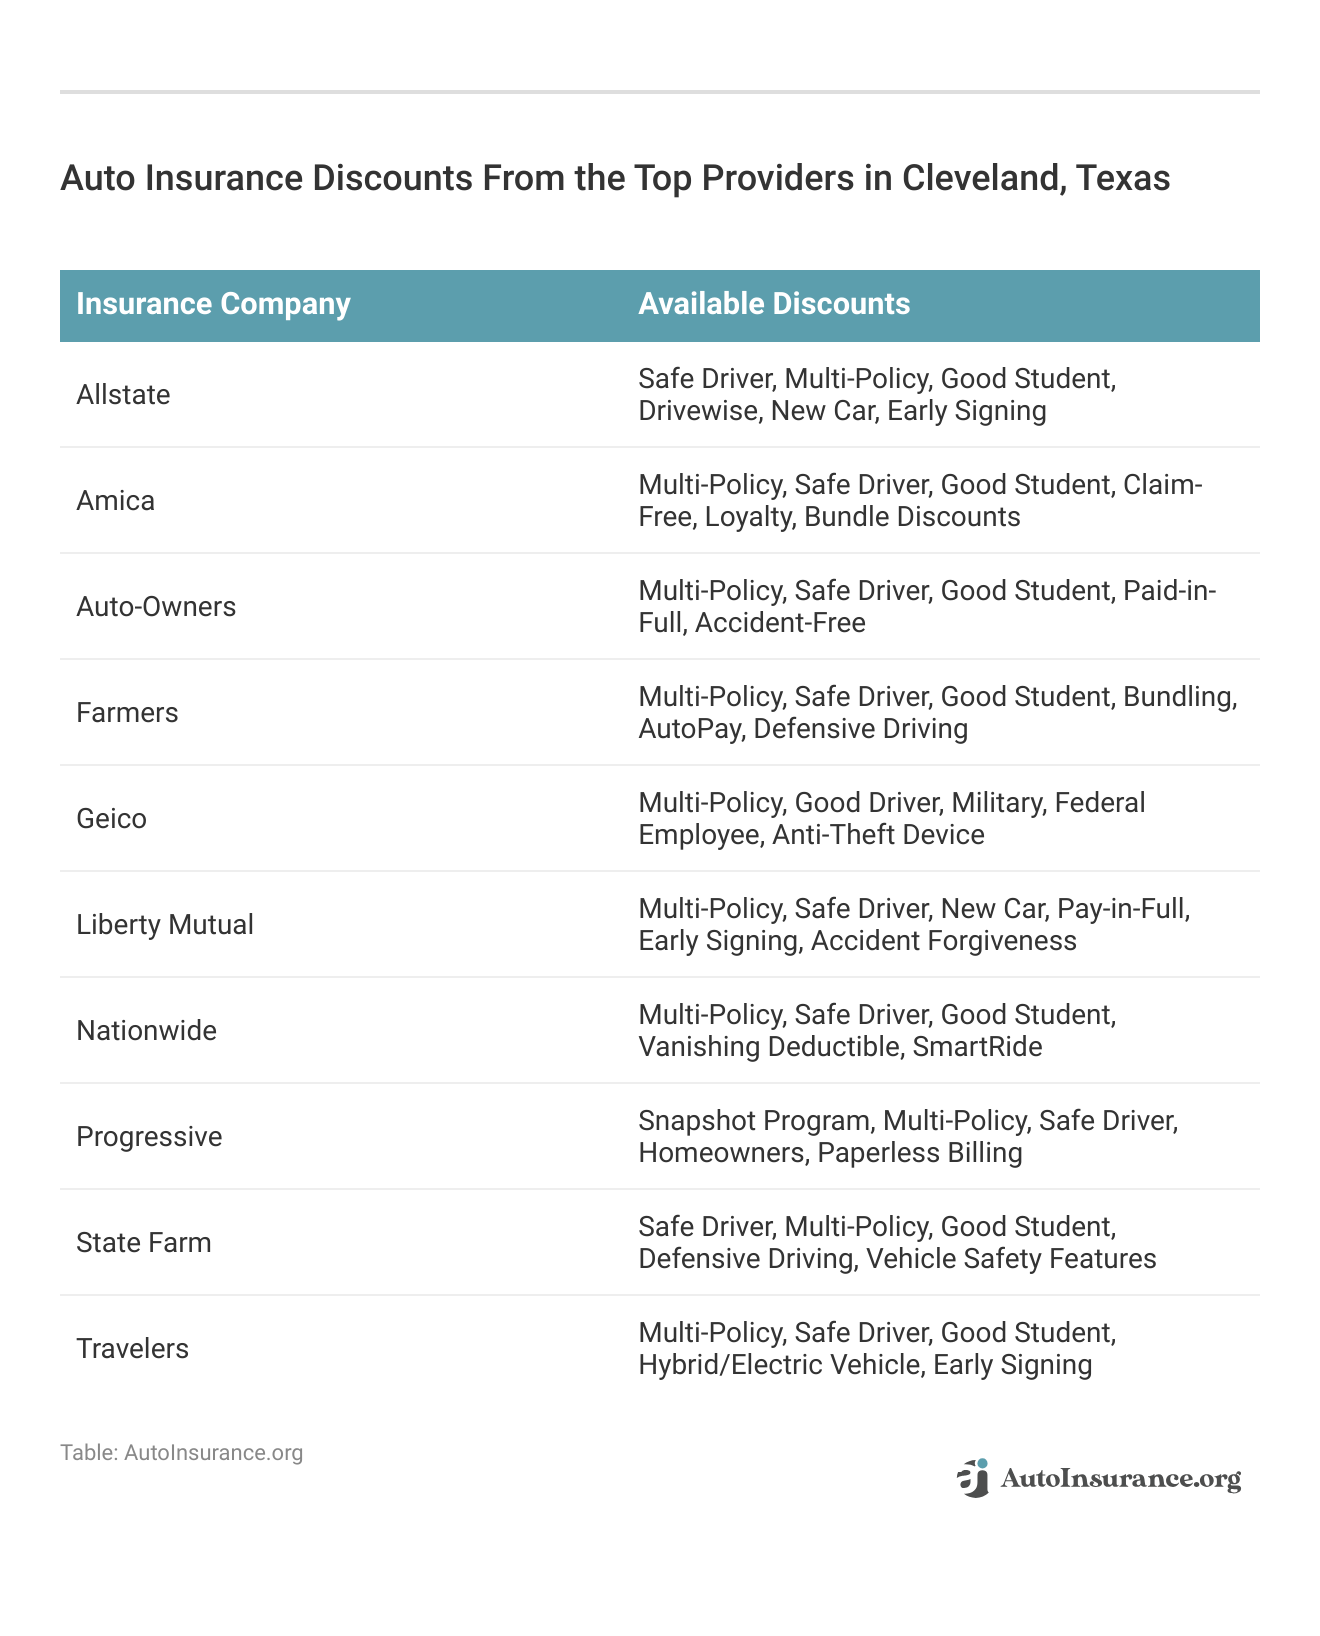
- Discounts for Commuters: Many insurers offer specific discounts for safe driving telematics (programs that track braking and speed) or for bundling auto with homeowners or renters insurance.
Comparison Table: Coverage Types for Texas Drivers
| Coverage Type | Purpose | Recommendation for Urban Drivers |
|---|---|---|
| Liability | Pays for damages you cause to others | Carry at least $100k/$300k/$100k |
| Collision | Pays to repair your car after an accident | Highly recommended for all commuters |
| Comprehensive | Covers theft, fire, hail, and flood | Essential for Texas climate risks |
| UM/UIM | Covers you if the other driver has no insurance | Critical in high-density urban areas |
| PIP | Pays for your medical bills regardless of fault | Highly recommended for everyday safety |
The Role of Telematics and Usage-Based Insurance
In 2026, technology plays a central role in premium adjustment. Most major insurers now offer Usage-Based Insurance (UBI) or telematics programs. These programs use a mobile app or an installed plug-in device to monitor driving behaviors such as rapid acceleration, harsh braking, and late-night driving habits.
For the everyday driver who adheres to speed limits and maintains a predictable work commute, these programs can result in significant annual savings. However, drivers who frequently operate their vehicles during high-risk hours or engage in aggressive urban maneuvers may see their premiums increase. Before enrolling, review the privacy policy and the specific metrics the insurer uses to calculate its discount.
Navigating Weather-Related Risks in Texas
Texas cities are prone to extreme weather, particularly hailstorms and localized flash flooding. A standard liability policy does not cover your vehicle if it is damaged by hail or submerged in high water. If you live in an area prone to flooding—such as low-lying regions in Houston—ensure that your comprehensive coverage is adequate.
Always review your deductible for comprehensive coverage. While a high deductible (e.g., $1,000) can lower your monthly premium, you must be prepared to pay that amount out of pocket if a severe hail event damages your vehicle’s body panels or glass.
Shopping for Insurance: A Step-by-Step Approach
- Assess Your Current Needs: Review your current declarations page. Identify if your liability limits match your current net worth.
- Gather Information: Collect your VIN (Vehicle Identification Number), current mileage, and a summary of any past claims or traffic violations from the last three years.
- Request Multiple Quotes: Obtain quotes from at least three different insurers. Ensure that you are requesting the exact same coverage limits for each quote so the comparison is "apples to apples."
- Evaluate Local Reputation: Search for the insurer on the Texas Department of Insurance website to check their complaint index. A high complaint ratio is a red flag regardless of how low the premium might be.
- Review the Fine Print: Look specifically for exclusions regarding business use of your vehicle. If you use your car for gig-economy delivery services, standard personal policies will not cover you, and you will need an endorsement or a commercial policy.
Frequently Asked Questions
1. Does my credit score affect my auto insurance rate in Texas? Yes, Texas law allows insurers to use credit-based insurance scores as one of many factors to determine premiums. Insurers argue that this score correlates with the likelihood of filing a claim. To maintain the best rates, keep your credit utilization low and ensure payments are on time.
2. Can I get a discount for a defensive driving course? Most Texas insurance companies offer a discount if you complete a state-approved defensive driving course. This is particularly useful for drivers who have recently incurred a traffic ticket or who have teenage drivers on their policy. Check with your specific insurer regarding their eligibility requirements.
3. What is the difference between towing and roadside assistance? Towing is a specific service to move your vehicle after a breakdown, while roadside assistance typically includes services like jump-starts, tire changes, lockout assistance, and fuel delivery. For the everyday commuter, having a robust roadside assistance package is often more valuable than basic towing.
4. Does moving from a rural area to a Texas city change my insurance rate? Yes, insurance rates are heavily based on ZIP codes. Urban areas typically have higher rates due to increased traffic density, higher rates of vehicle theft, and a greater frequency of accidents. When you move, notify your insurer immediately to avoid issues with claims later.
5. How often should I re-evaluate my policy? You should review your policy at least once a year, or whenever you experience a major life event, such as moving, changing jobs, or adding a new driver to your household. Market conditions change, and a policy that was competitive last year may no longer be the best fit for your budget.
Next Actions for the Texas Driver
Your immediate next step is to log into your current provider’s portal and download your "declarations page." Review your current limits against the reality of your daily commute. If you are carrying only state minimums, request an updated quote for higher liability limits and uninsured motorist protection. Contact a local independent insurance agent who can provide quotes from multiple carriers simultaneously, saving you time and providing a deeper level of localized expertise than a national call center. Ensure that your final selection balances the financial stability of the insurer with a coverage plan that protects your personal assets from the unique risks of the Texas road.
Image Gallery
Select an image to open it in a new tab.

Vivian Cho
Executive IT and Emerging Technologies Reporter
