Finding the 1 Best Life Insurance Company for Diabetics: Why John Hancock Often Leads

Securing coverage with a diabetes diagnosis requires navigating strict underwriting guidelines, but John Hancock consistently emerges as a top choice by rewarding proactive condition management, utilizing advanced underwriting technology, and offering integrated wellness programs that lower long-term premiums.
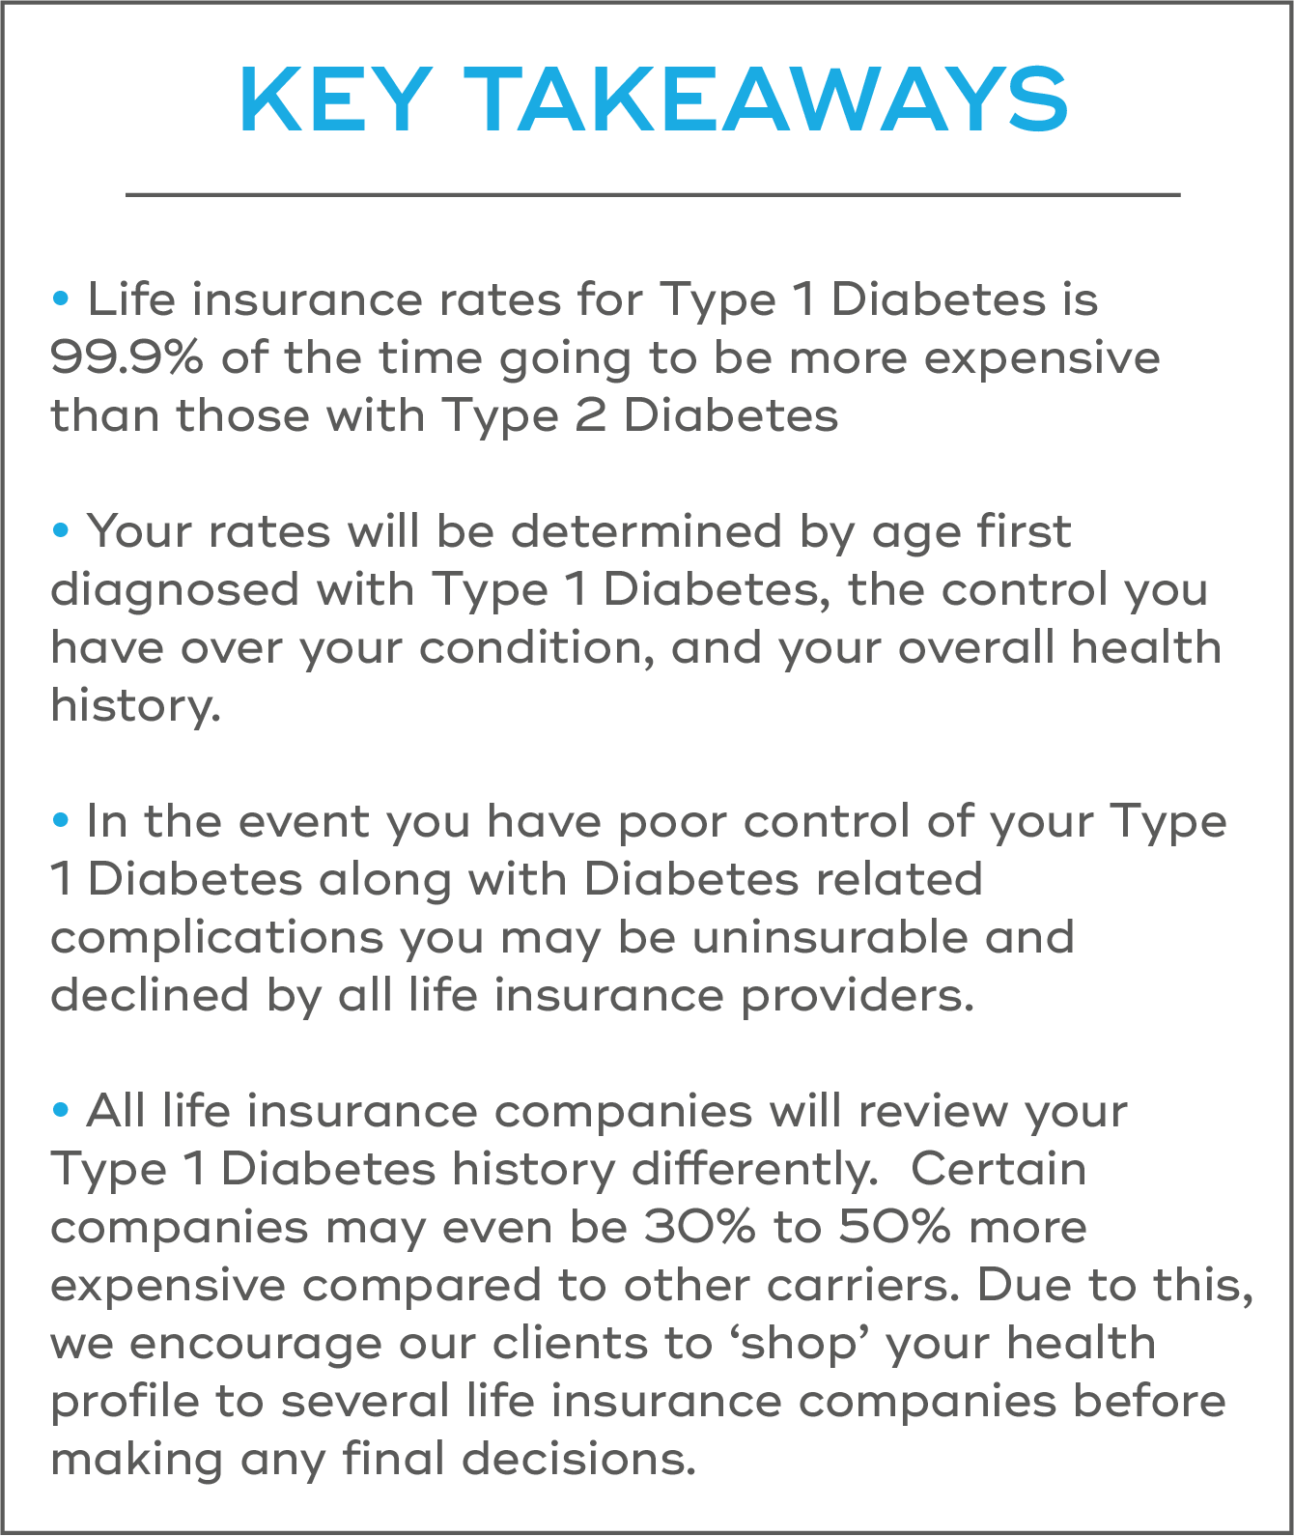
Navigating the life insurance market with a diabetes diagnosis can feel like traversing a maze. Historically, individuals with Type 1 or Type 2 diabetes faced automatic rate hikes, limited policy options, or outright denials from traditional carriers. However, modern underwriting has evolved significantly. Today, finding the 1 best life insurance company for diabetics depends heavily on how a carrier evaluates blood sugar control, lifestyle habits, and technological integration. Among major providers, John Hancock frequently claims the top spot for policyholders managing diabetes, largely due to its innovative approach to risk assessment, emphasis on health tracking, and competitive pricing for well-controlled profiles.
Understanding why John Hancock often leads the industry requires a close examination of how life insurance underwriting works for diabetic applicants, the specific metrics carriers evaluate, and the policy structures that offer the best long-term value. This guide explores the foundational requirements, specific advantages of leading carriers, common pitfalls during the application process, and actionable steps to secure the most favorable rates.
Understanding Life Insurance Underwriting for Diabetics
To understand why a particular carrier stands out, one must first understand how life insurance companies evaluate applicants with diabetes. Underwriters do not view diabetes as a monolithic condition; instead, they look at a granular profile of your health management.
When you apply for term or permanent life insurance with diabetes, underwriters look beyond the simple fact that you have the condition. They evaluate how effectively you manage it day-to-day. The primary objective of the underwriter is to determine your life expectancy and the risk of developing secondary complications, such as neuropathy, retinopathy, nephropathy, or cardiovascular disease.
Key Metrics Evaluated by Underwriters
- Hemoglobin A1c (HbA1c): This is the single most critical biometric marker underwriters check. It measures your average blood glucose levels over the past three months. An A1c under 7.0 is typically required for standard or better ratings, though some companies offer competitive rates for readings up to 7.5 or 8.0 if other health indicators are pristine.
- Age of Onset and Duration: Developing diabetes later in life (Type 2 after age 40, for example) is generally viewed more favorably than a childhood diagnosis of Type 1 diabetes, simply because the cumulative damage window is shorter.
- Compliance and Treatment Consistency: Underwriters want to see that you work with an endocrinologist or primary care physician regularly. Consistent medication adherence, whether through oral hypoglycemics or insulin therapy, is a positive indicator of risk management.
- Type of Medication: The specific medications you take matter. Diet-controlled diabetes or diabetes managed via oral medications (like metformin) usually receives more favorable pricing than insulin-dependent diabetes, though advanced carriers are increasingly closing this gap for well-managed insulin users.
- Secondary Health Markers: Blood pressure, cholesterol levels, Body Mass Index (BMI), and tobacco use play a massive amplifying role. A diabetic applicant with clean cardiovascular markers will secure vastly superior rates compared to one struggling with hypertension or obesity.
Why John Hancock Often Leads the Market
John Hancock has built a reputation as an industry leader for diabetic life insurance by shifting the underwriting paradigm. Traditional insurers often penalize chronic conditions uniformly, but John Hancock uses a specialized approach that rewards policyholders for managing their health actively.
The Vitality Program and Behavioral Underwriting
The cornerstone of John Hancock’s market dominance for diabetic applicants is its Vitality program. Unlike traditional policies where your premium is locked based strictly on static medical exams taken years apart, John Hancock integrates behavioral economics and wearable technology.
Through the John Hancock Vitality program, policyholders can earn points by engaging in everyday healthy activities, such as walking, tracking sleep, getting annual health screenings, and maintaining stable blood glucose readings. For a diabetic applicant, this program offers tangible financial incentives:
- Initial Savings: Policies often start with discounted premiums compared to standard industry averages for diabetic profiles.
- Ongoing Discounts: As policyholders log healthy habits via compatible fitness trackers (such as Apple Watch, Garmin, or Fitbit), they can earn Vitality Status levels (Bronze, Silver, Gold, Platinum), which directly reduce annual premiums or earn rewards on everyday purchases.
- Data-Driven Re-underwriting: If your health improves over time—such as lowering your A1c through sustained lifestyle changes—your pricing structure can reflect those improvements without requiring a completely new policy application.
Favorable Guidelines for Well-Controlled Diabetes
John Hancock employs a more nuanced underwriting manual than many competitors. While a rigid insurer might automatically relegate any applicant with an A1c of 7.5 to a table-rated (substandard) pricing tier, John Hancock evaluates the broader picture. If an applicant demonstrates comprehensive medical records, stable blood sugar logs, and zero tobacco use, John Hancock frequently extends standard or even better-than-average rating classes.
Furthermore, the company has progressive guidelines for Type 1 diabetics who maintain exceptional control using modern medical technology, such as continuous glucose monitors (CGMs) and automated insulin delivery systems. By recognizing that modern tools allow for tighter glycemic control, John Hancock’s underwriters assess modern risks more accurately than legacy-bound competitors.
Comparing Leading Life Insurance Options for Diabetics
While John Hancock is frequently cited as the top choice, the life insurance landscape includes several other competitive carriers. Each has distinct strengths depending on whether you have Type 1 or Type 2 diabetes, your age, and your preferred policy type.
| Insurance Carrier | Primary Advantage for Diabetics | Best Suited For | Typical A1c Threshold for Best Rates |
|---|---|---|---|
| John Hancock | Vitality program rewards health tracking; progressive underwriting for controlled profiles. | Tech-savvy applicants and those dedicated to active health management. | Under 7.0 (up to 7.5 case-by-case) |
| Prudential | Highly flexible manual; specialized underwriting for complex or combined health issues. | Applicants with secondary conditions or fluctuating A1c levels. | Under 7.5 |
| Mutual of Omaha | Excellent options for simplified issue or final expense policies if medical underwriting is restrictive. | Older applicants or those seeking smaller face-value policies without exams. | Varies by product tier |
| AIG (American General) | Competitive pricing for older applicants with long-standing Type 2 diabetes. | Seniors diagnosed with adult-onset diabetes seeking permanent coverage. | Under 8.0 depending on age |
Step-by-Step Guide to Securing the Best Rates
Applying for life insurance with diabetes requires careful preparation. Because underwriters rely heavily on documentation, missing or disorganized medical records can result in unnecessarily high rate quotes or delayed approvals. Follow these steps to optimize your application outcome:
1. Gather Your Medical Records in Advance
Before speaking with an agent, pull your recent medical history. You should have ready access to:
- Your last 2 to 3 years of physician notes, specifically from your endocrinologist or primary care doctor.
- A complete log of your recent A1c test results.
- A precise list of all current prescriptions, dosages, and administration methods.
- Records of any routine screenings (eye exams, kidney function tests, foot exams) that prove you are actively monitoring for complications.
2. Optimize Your Biometrics Prior to the Exam
While you cannot instantly reverse a long-term condition, you can control short-term variables that influence your paramedical exam. Ensure that in the days leading up to your blood and urine tests, you maintain stable eating habits, avoid excessive carbohydrates or sugary foods immediately before the test, stay well-hydrated, and refrain from alcohol and tobacco.
3. Work with an Independent Broker
Do not apply directly to a single insurance company. Instead, work with an independent insurance broker who specializes in high-risk or impaired-risk underwriting. An experienced broker has access to multiple carriers (including John Hancock, Prudential, and others) and can shop your specific health profile anonymously to see which underwriter will view your diabetic management in the most favorable light before submitting a formal application.
4. Be Completely Transparent on the Application
Never conceal details about your diagnosis date, medication compliance, or past complications. Underwriters cross-reference applications with the Medical Information Bureau (MIB) and prescription database histories. Discrepancies between your application and your actual medical records will immediately stall underwriting or result in a policy denial for misrepresentation.
Common Pitfalls to Avoid
Navigating the application process successfully also means understanding what not to do. Many applicants inadvertently drive up their quotes or face outright rejections due to avoidable missteps.
- Applying Too Early After a Change in Medication: If you recently altered your insulin dosage or switched medications, wait until your blood sugar stabilizes for at least 3 to 6 months before applying. Underwriters prefer stability over volatility.
- Neglecting Routine Screenings: If your primary care physician recommends an annual eye exam or kidney panel and you skip it, underwriters view that omission as a compliance risk. Regular screening demonstrates that you are a proactive patient.
- Ignoring Co-morbidities: Focusing exclusively on blood sugar while ignoring high blood pressure or elevated cholesterol can derail an application. Comprehensive health management requires keeping all key vital signs within acceptable ranges.
- Settling for Guaranteed Issue Too Soon: Guaranteed acceptance policies (which require no medical exam) often feature extremely high premiums and low payout caps (often restricted to $25,000 or $30,000). Unless your health profile is severe, traditional underwritten policies through carriers like John Hancock will offer vastly superior coverage amounts at a lower cost.
Frequently Asked Questions
Can I get term life insurance if I have Type 1 diabetes?
Yes, individuals with Type 1 diabetes can qualify for term life insurance, provided the condition is well-controlled and diagnosed after childhood (or managed effectively for many years). While premiums will generally be higher than those for a non-diabetic applicant of the same age, modern underwriting views well-managed Type 1 cases much more favorably than in the past, especially when using continuous glucose monitoring technology.
What is the maximum A1c level accepted by life insurance companies?
There is no absolute industry-wide cutoff, but most standard or preferred rates require an A1c below 7.0. Some carriers will consider applicants with an A1c up to 8.0 or slightly higher, though these applications typically result in table ratings (substandard tiers) that increase the cost of insurance. A few specialized carriers may postpone applications if the A1c exceeds 9.0 until the applicant demonstrates better long-term control.
Does John Hancock require a medical exam for diabetic applicants?
While John Hancock offers accelerated underwriting pathways for certain healthy applicants without medical exams, diabetic applicants almost always require a full paramedical exam. This includes blood draws and urinalysis to verify your current A1c levels, kidney function, and other metabolic markers directly.
Are diabetes-related complications an automatic disqualifier?
Not necessarily. Minor, well-managed secondary conditions may result in a rated policy rather than a denial. However, severe complications—such as advanced nephropathy, neuropathy, or a history of cardiovascular events—will significantly impact insurability and may require specialized high-risk carriers or simplified issue alternatives.
How does the John Hancock Vitality program lower my insurance costs?
The Vitality program tracks your everyday health activities through connected mobile apps and wearable devices. By hitting weekly physical activity goals, getting regular medical checkups, and maintaining stable health metrics, you accumulate Vitality points. These points determine your annual status level, which directly translates to percentage discounts on your yearly life insurance premiums.
Professional Guidance and Next Actions
Securing life insurance with diabetes requires treating the application process like a strategic project. Because underwriting guidelines vary wildly between carriers, partnering with an independent brokerage that maintains deep relationships with progressive companies like John Hancock is your most effective strategy. Begin by gathering your complete medical history, confirming your recent A1c logs, and requesting preliminary quotes through an expert who can match your exact glycemic profile with the most accommodating underwriting manual on the market.
Image Gallery
Select an image to open it in a new tab.


Zara El-Hashem
Sociocultural Dynamics and Academics Writer
