
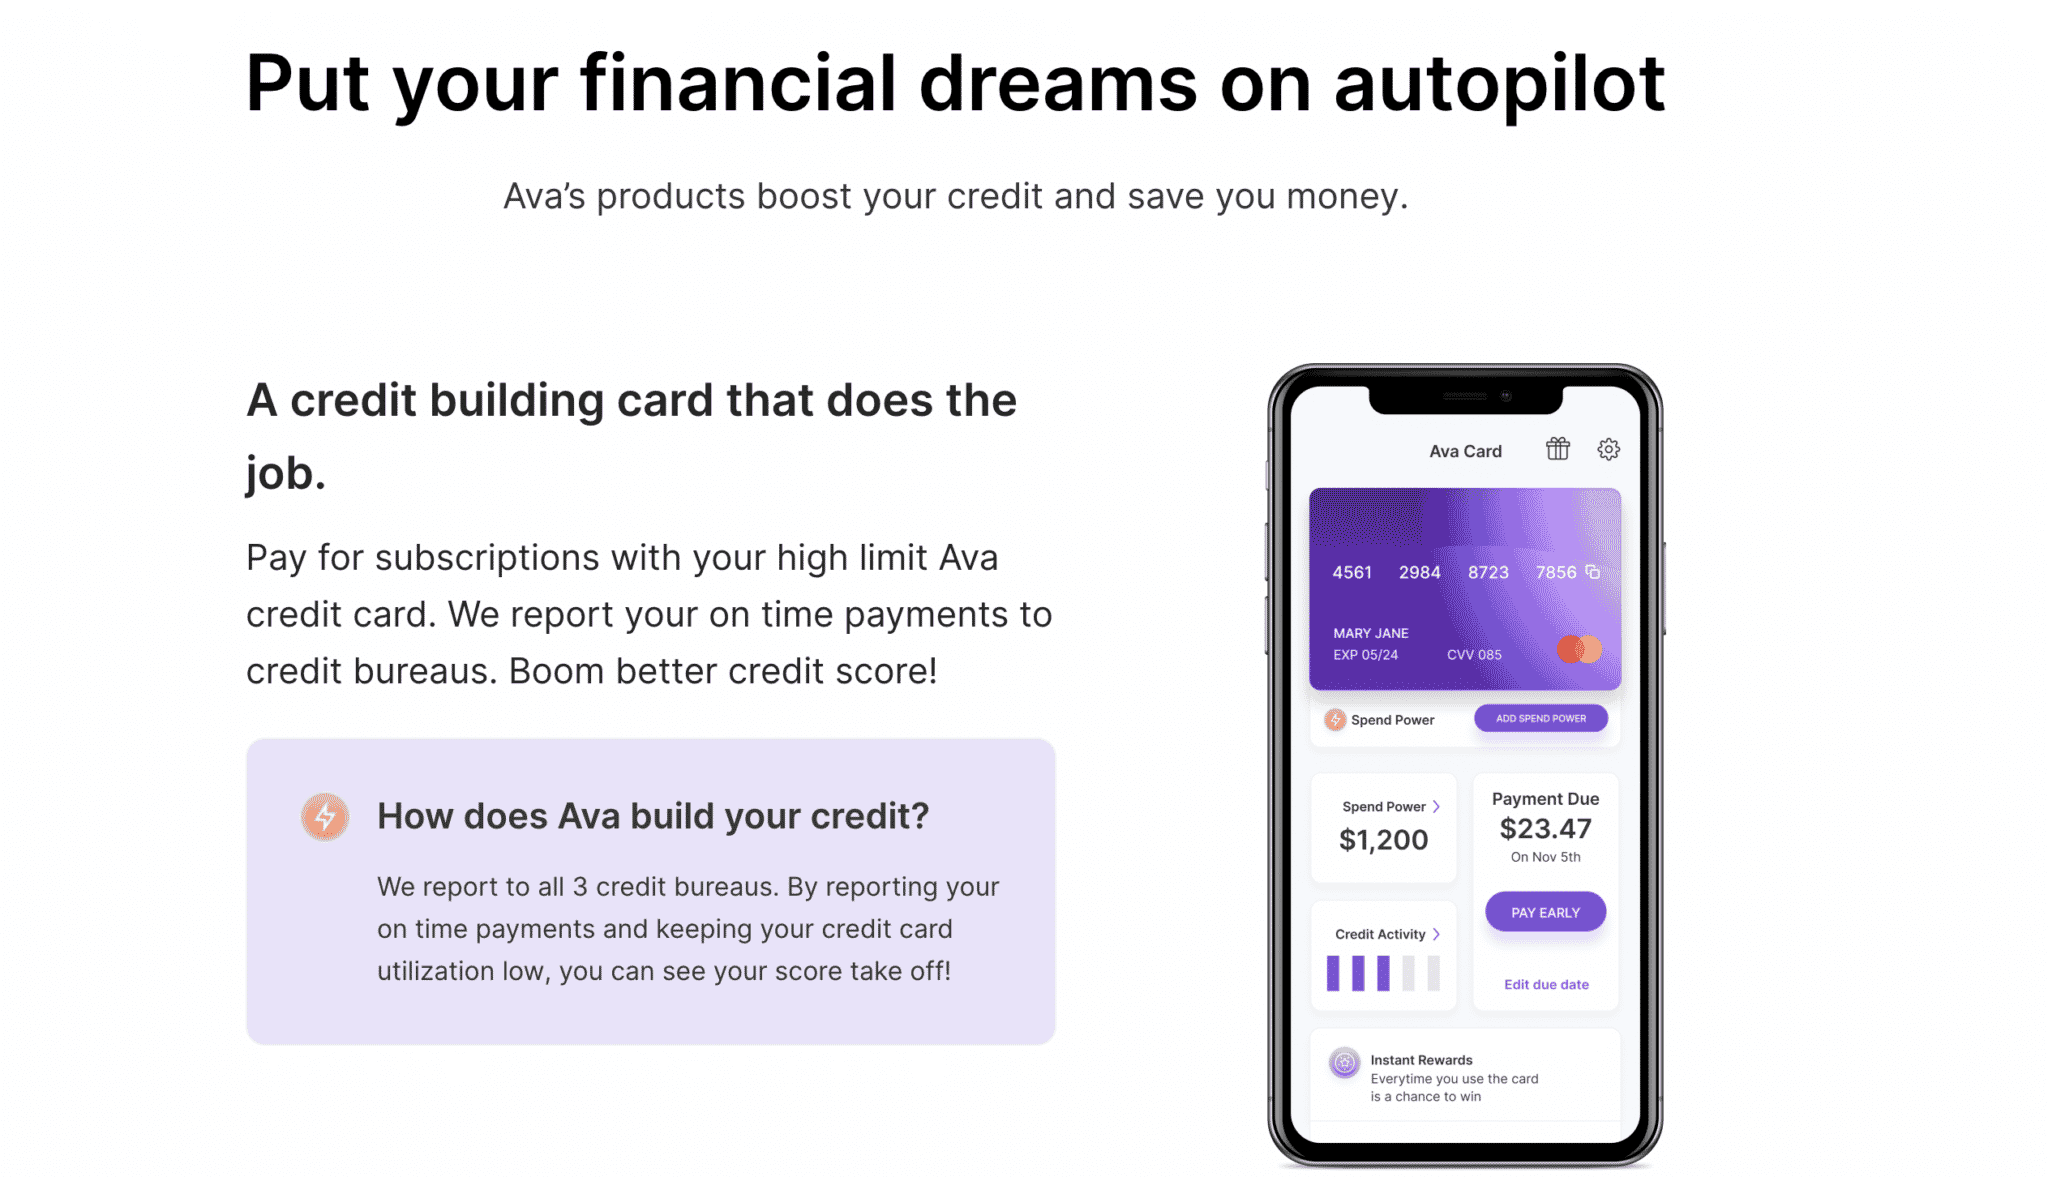
The Ava app credit system functions as a financial tool designed to help users build credit history, manage expenses, and navigate cash flow challenges without incurring traditional credit card debt or high-interest revolving balances. By integrating digital budgeting features with credit-building mechanisms, the application allows consumers to monitor their financial standing, track credit scores, and access specific credit lines or cash advances subject to eligibility criteria, subscription tiers, and internal algorithmic assessments.
Navigating modern financial applications requires a clear comprehension of how digital credit tools operate, what prerequisites are necessary for access, and how these mechanisms affect your overall financial health. As consumer fintech solutions continue to evolve, understanding the distinction between credit-building accounts, cash advances, and traditional revolving lines of credit remains critical for anyone looking to optimize their personal finances responsibly.
The Core Mechanics of FinTech Credit and App-Based Financial Tools
Financial technology applications have transformed how consumers interact with credit reporting agencies and lending products. Historically, building or repairing credit required securing a traditional secured credit card, taking out a small personal loan, or becoming an authorized user on an established account. Today, platforms like Ava bridge the gap by offering alternative pathways that report payment history to major credit bureaus, thereby influencing consumer credit scores.
App-based credit systems typically operate on subscription models or bundled fee structures rather than traditional interest rates alone. Users pay a recurring fee to access a suite of tools, which may include credit monitoring, automated savings features, debt-payoff calculators, and specific credit-builder lines. When an application reports positive payment histories to major credit bureaus—such as Equifax, Experian, and TransUnion—it helps establish a positive payment history, which constitutes a major component of standard credit-scoring models like FICO and VantageScore.
However, users must distinguish between credit-building products and high-cost borrowing. While credit-builder accounts hold funds in a locked savings account while reporting monthly payments, other app features might provide immediate liquidity or purchasing power. Examining the underlying mechanics ensures that consumers do not inadvertently trigger adverse financial habits or misunderstand the true cost of app-based subscriptions and fees.
Eligibility, Requirements, and Setup Procedures
Accessing credit features within modern financial applications involves a structured onboarding process designed to verify identity, assess financial capacity, and comply with federal and state regulations. Before utilizing any credit-building or cash advance feature, users must typically satisfy several baseline requirements.
Standard Prerequisites for App-Based Credit Access
- Identity Verification: Users must provide legal identification, a valid Social Security Number (SSN) or Individual Taxpayer Identification Number (ITIN), and proof of residential address to comply with Know Your Customer (KYC) regulations.
- Connected Bank Account: Applications generally require Read-Only access to a primary checking account via secure data aggregators (such as Plaid) to analyze income stability, cash flow, and existing financial obligations.
- Subscription Status: Many comprehensive credit tools operate behind a paid tier, requiring an active monthly or annual subscription fee to maintain access to credit-reporting features and specialized credit lines.
- Age and Jurisdiction: Applicants must be at least 18 years of age (or the age of majority in their respective state) and reside within supported geographic regions, as specific state laws govern lending practices and fee caps.
Once these prerequisites are met, users complete a digital application. Unlike traditional hard credit inquiries that can temporarily lower a credit score, many modern financial apps utilize soft credit pulls during the initial eligibility phase, which do not impact your credit score.
Features, Costs, and Comparative Analysis
Evaluating a financial application requires a side-by-side look at what features are included, what costs are associated with the service, and how the platform compares to traditional financial products. The following table outlines key dimensions of app-based credit products versus conventional banking alternatives.
| Feature / Dimension | App-Based Credit Tools (e.g., Ava) | Traditional Secured Credit Cards | Traditional Personal Loans |
|---|---|---|---|
| Primary Purpose | Credit building, budgeting, financial tracking | Credit building, day-to-day purchasing | Lump-sum borrowing, major expenses |
| Credit Bureau Reporting | Typically reports monthly payments to major bureaus | Reports monthly balances, utilization, and payments | Reports monthly installment payments |
| Cost Structure | Monthly or annual subscription fees | Annual fees, high APR if balances are carried | Origination fees, fixed interest rates (APR) |
| Impact on Credit Score | Positive history building; low risk if managed | High impact; utilization ratio heavily weighted | Fixed installment history; installment mix |
| Approval Requirements | Bank account verification, identity check | Security deposit, standard credit/ID check | Credit score check, income verification |
When assessing these options, consumers must weigh the convenience and integrated budgeting features of apps against the rigid regulatory protections and cost structures of traditional banking products. While apps offer accessible entry points for individuals with thin credit files, users should calculate the annualized cost of subscription fees to ensure the financial return justifies the expense.
Potential Risks, Limitations, and Common Misconceptions
While financial applications provide valuable tools for credit visibility and education, they are not a universal fix for severe credit distress or structural financial instability. Understanding the limitations prevents unrealistic expectations and safeguards against financial missteps.
Key Risks and Operational Limitations
- Subscription Fatigue: Continuous monthly fees can accumulate over time, sometimes outweighing the financial benefit gained from minor credit score improvements.
- Algorithmic Adjustments: App-based credit lines and advance limits are typically determined by automated algorithms tracking bank account inflows. Sudden shifts in income or irregular deposit patterns can lead to unexpected reductions in available credit limits.
- Limited Scope: Using a single app-based credit tool will not instantly repair severe negative marks such as tax liens, bankruptcies, or long-standing charge-offs on a credit report. Comprehensive credit repair requires addressing underlying debt obligations directly.
- Data Privacy Considerations: Connecting primary banking credentials to third-party fintech applications requires sharing sensitive financial data. Users should review privacy policies regarding how data is stored, shared, or utilized for marketing purposes.
Troubleshooting and Best Practices for Digital Credit Management
Successfully managing app-based credit tools involves consistent oversight and disciplined financial habits. If you encounter issues with account synchronization, credit bureau reporting delays, or feature access, systematic troubleshooting can resolve most common hurdles.
Best Practices for Optimal Usage
- Maintain Consistent Cash Flow: Ensure your primary checking account maintains a healthy balance and regular deposit schedule, as algorithmic credit limits often depend on steady income verification.
- Monitor Credit Reports Directly: Do not rely solely on an app's dashboard. Periodically pull your official credit reports through government-authorized platforms (such as AnnualCreditReport.com) to verify that the app's reported payments are accurately reflected on your bureau files.
- Audit Subscription Value: Regularly evaluate whether the features you use justify the recurring subscription cost. If your credit score has stabilized or you no longer utilize the supplementary budgeting tools, reassess your need for the service.
- Address Sync Errors Promptly: If your bank account disconnects due to security updates or password changes, re-link the account immediately to prevent missed reporting cycles or failed subscription fee payments.
By approaching financial applications with a clear understanding of their mechanics, costs, and limitations, consumers can leverage digital tools effectively to support long-term financial health and credit stability.
Image Gallery
Select an image to open it in a new tab.



Akira Tanaka
International Academic Trends Correspondent
