
You generally need commercial auto insurance if your work truck is registered to a business, used to transport goods or equipment for profit, or driven by employees. Personal auto policies typically exclude coverage for business-related activities, meaning a claim could be denied if an accident occurs while performing work duties.
Determining whether your vehicle requires a commercial policy or a standard personal policy is one of the most critical financial decisions a contractor or small business owner can make in 2026. While the physical vehicle—a Ford F-150 or a Chevrolet Silverado—might look like a standard commuter vehicle, the legal and financial risks associated with its use can vary significantly. Insurance companies categorize risk based on how a vehicle is used, who is driving it, and what it carries.
Miscalculating this need can lead to catastrophic financial consequences, including the total denial of a claim following a major accident. This guide explores the specific triggers that necessitate commercial coverage, the limitations of personal policies, and how to ensure your livelihood is protected.
Understanding the Fundamental Difference in Risk
Insurance is essentially the "pricing of risk." From an insurer's perspective, a work truck represents a higher risk profile than a personal vehicle used for commuting or grocery shopping. In 2026, data-driven underwriting has only sharpened these distinctions.
A work truck is often on the road for more hours per day, frequently travels to unfamiliar job sites, and carries heavy tools or materials that can increase the severity of an accident. Furthermore, a business-owned vehicle is a more attractive target for litigation. If a truck branded with a company logo is involved in a collision, the injured party is more likely to sue for higher damages, assuming the business has "deep pockets." Commercial policies are designed with higher liability limits—often starting at $500,000 or $1,000,000—to account for this increased exposure.
Key Triggers for Commercial Auto Insurance
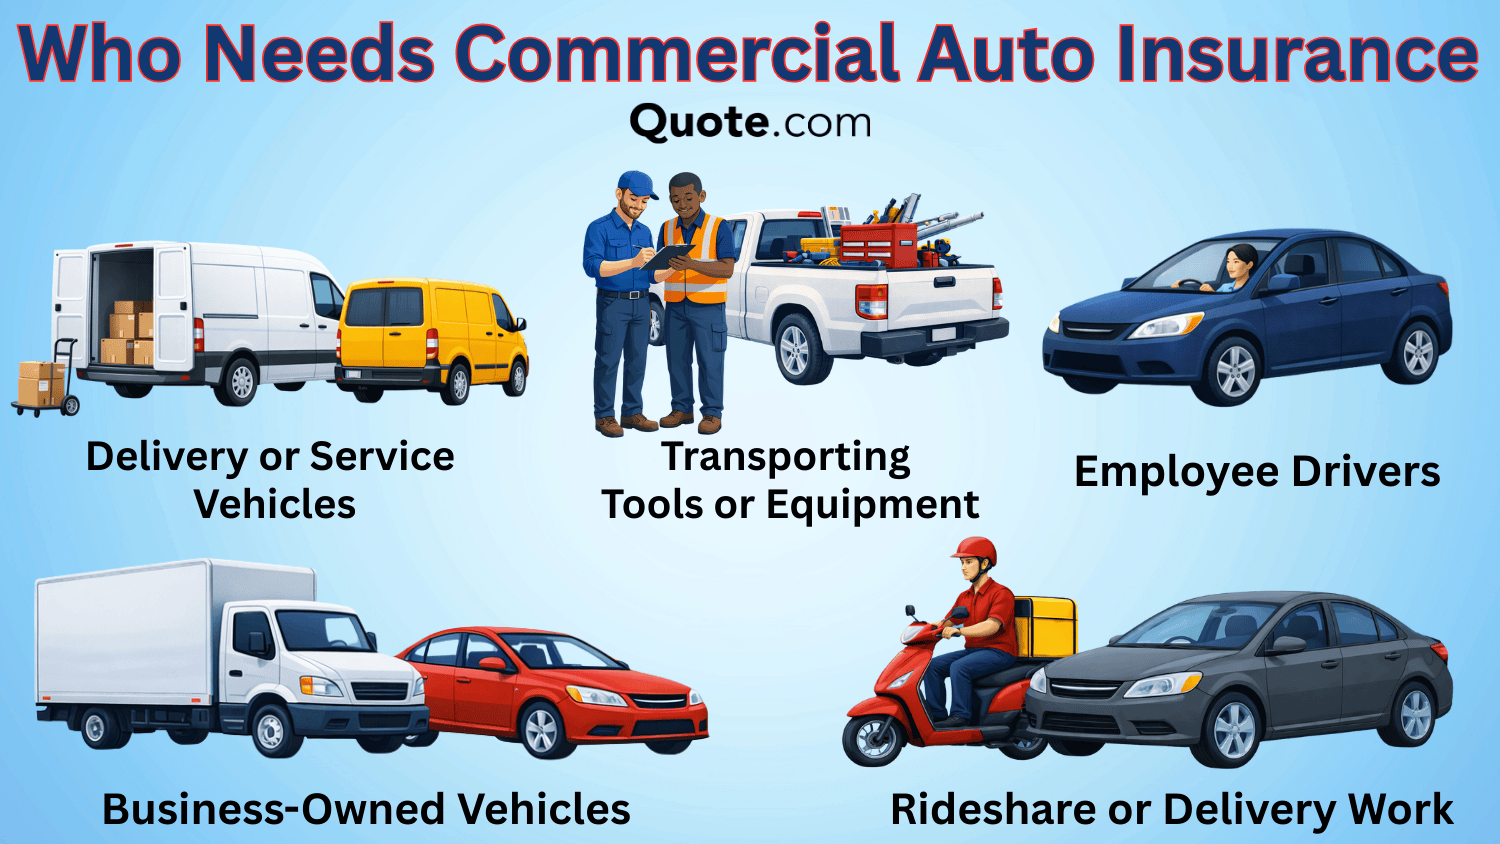
If you are unsure whether your truck requires a commercial policy, evaluate your situation against these four primary triggers. Meeting even one of these criteria usually mandates a transition away from personal insurance.
1. Business Ownership and Registration
If the title and registration of the truck are in the name of a corporation, LLC, or partnership, you almost certainly need a commercial auto policy. Personal insurance is designed for individuals and households. Most personal insurers will not issue a policy to a business entity. Even if you are a sole proprietor, if you have registered your vehicle as a commercial asset for tax purposes, your insurance should align with that classification.
2. The Weight and Size of the Vehicle
Most personal auto insurance policies have a weight limit, typically capped at a Gross Vehicle Weight Rating (GVWR) of 10,000 pounds. Many heavy-duty work trucks, such as the Ford F-350, Ram 3500, or any truck with a utility body, dump bed, or crane, exceed this limit. Even if you only use the truck for occasional "side jobs," the sheer size of the vehicle places it in a commercial category for most carriers. According to the Federal Motor Carrier Safety Administration (FMCSA), vehicles over a certain weight involved in interstate commerce must also follow specific federal regulations, which further necessitates commercial-grade insurance.
3. Employee Drivers
A standard personal policy covers the policyholder and occasionally "permissive users" (like a spouse or child). However, if you have employees, subcontractors, or laborers driving your truck, a personal policy will likely not cover them in the event of an accident. Commercial policies allow for "Any Auto" or "Scheduled Auto" coverage, which ensures that whoever is behind the wheel on behalf of the business is protected.
4. Specialized Equipment and Usage
What you carry in the truck matters as much as the truck itself. If your vehicle is equipped with a snowplow, a permanent ladder rack, or specialized towing equipment used for hire, it is no longer a personal vehicle. Furthermore, if you use the truck to transport hazardous materials, flammable liquids, or heavy machinery, the liability risk increases exponentially. Personal insurers are not equipped to calculate the risk of a chemical spill or a tool-related injury occurring from the bed of a truck.

Comparing Personal and Commercial Policies
The following table highlights the structural differences between these two types of coverage to help you identify where your current protection may be lacking.
| Feature | Personal Auto Insurance | Commercial Auto Insurance |
|---|---|---|
| Typical Liability Limits | $25,000 – $300,000 | $500,000 – $1,000,000+ |
| Allowable GVWR | Usually up to 10,000 lbs | No limit (includes heavy-duty) |
| Driver Coverage | Policyholder & household | Employees & multiple drivers |
| Equipment Coverage | Personal effects only | Tools, equipment, & cargo |
| Business Use Exclusion | Standard in most policies | Built into the core policy |
| Towing/Hauling | Personal trailers only | Commercial trailers & for-hire towing |
The Danger of the "Business Use" Misconception
Many truck owners believe that adding a "business use" endorsement to their personal policy provides sufficient protection. While this endorsement exists, it is intended for a very narrow set of circumstances—usually for white-collar professionals like real estate agents or sales representatives who drive between offices.
A "business use" endorsement on a personal policy typically does not cover:
- Hauling heavy equipment or materials.
- Making frequent deliveries.
- Using the vehicle as a mobile workshop.
- Towing trailers for construction or landscaping.
If you are a contractor, plumber, or landscaper, relying on a personal policy with a business use endorsement is a significant risk. If an adjuster discovers you were hauling a pallet of bricks or a commercial lawnmower at the time of an accident, they may deny the claim based on a violation of the policy's terms.
Coverage Options Unique to Commercial Policies
Commercial insurance offers specialized protections that are unavailable in the personal market. Understanding these can help you customize a policy that actually protects your bottom line.
Inland Marine Insurance
Despite the name, this has nothing to do with water. It covers your tools and equipment while they are in transit to a job site or stored on your truck. A standard auto policy (personal or commercial) covers the vehicle itself, but not the $5,000 worth of power tools in the back. Inland Marine is an essential "rider" for work trucks.
Hired and Non-Owned Auto (HNOA)
If you ever rent a truck for a big job or ask an employee to run an errand in their own vehicle, HNOA coverage protects your business. If an employee gets into an accident in their personal car while picking up supplies for you, your business could be sued. HNOA bridges that gap.
Cargo Insurance
If you are transporting items belonging to others (for example, if you are a delivery contractor or a mover), cargo insurance covers the value of the items in the truck. Standard collision and comprehensive insurance only cover the damage to the truck, not the contents that belong to your clients.
Financial and Legal Consequences of Inadequate Insurance
In 2026, the legal landscape for small businesses is increasingly complex. Operating a work truck without commercial insurance can lead to several negative outcomes:
- Claim Denials: This is the most immediate risk. If you are at fault in an accident and the insurer determines the vehicle was being used for undisclosed commercial purposes, you will be responsible for all medical bills and property damage out of pocket.
- License Suspension: In many states, if you are involved in a commercial accident without the proper filing (such as a Form SR-22 in specific high-risk cases or commercial filings), your driver’s license and business license could be at risk.
- Contractual Breaches: Most General Contractors and government entities require proof of commercial auto insurance with specific limits (often $1M) before you can step onto a job site. Without it, you may lose out on high-value contracts.
- Personal Asset Exposure: If your business is an LLC but you use personal insurance, a lawyer could potentially "pierce the corporate veil," arguing that you did not maintain proper separation between personal and business activities. This could put your home and personal savings at risk in a lawsuit.
Estimating the Cost of Commercial Auto Insurance
While commercial insurance is generally more expensive than personal insurance, the gap has narrowed in 2026 due to better telematics. Many insurers now offer "pay-how-you-drive" programs that allow safe drivers to lower their premiums. Factors influencing your cost include:
- Driving Record: Just like personal insurance, your MVR (Motor Vehicle Record) is the primary factor.
- Location: Trucks operating in high-traffic urban areas pay more than those in rural settings.
- Radius of Operation: If you only travel within a 50-mile radius, your rates will be lower than a truck that travels across state lines.
- Deductibles: Opting for a higher deductible can significantly lower your monthly premium, though it increases your immediate out-of-pocket cost during a claim.
FAQ
Q: Can I keep my personal insurance if I only use my truck for work occasionally? A: It depends on the nature of the "work." If you are simply commuting to a single job site and staying there all day, a personal policy might suffice. However, if you are transporting tools or products between sites, you are likely in the commercial territory. It is best to be transparent with your agent to avoid a denied claim later.
Q: Is commercial insurance tax-deductible? A: Yes. Because commercial auto insurance is a necessary business expense, the premiums are generally 100% tax-deductible. This helps offset the higher cost compared to personal insurance. Always consult with a tax professional regarding IRS Publication 463 for specific deduction rules.
Q: Do I need commercial insurance for a pickup truck used for ridesharing or delivery apps? A: Yes. Apps like Uber, Lyft, or DoorDash typically require specific commercial endorsements or separate policies. While some apps provide limited coverage while the app is active, there are often "gaps" in coverage that only a personal-commercial hybrid or full commercial policy can fill.
Q: Does my personal umbrella policy cover my work truck? A: Generally, no. Most personal umbrella policies specifically exclude any liability arising from business pursuits. If you need extra liability protection for your business, you should look into a Commercial Umbrella or Excess Liability policy.
Q: Can I switch from personal to commercial insurance at any time? A: Yes, you can transition your coverage mid-term. Most insurers will provide a pro-rated refund for your personal policy and start your commercial coverage immediately. It is often smoother to do this if you stay with the same carrier, though shopping around is recommended for the best rates.
Final Recommendation
If your truck is a tool of your trade—meaning it is essential for you to perform your job and generate income—you should prioritize commercial auto insurance. The risk of a denied claim far outweighs the monthly savings of a personal policy.
To take the next step, gather your truck’s VIN, your estimated annual mileage, and a list of all drivers, then contact a commercial insurance broker. Ask specifically about "Inland Marine" riders to protect your tools and "Combined Single Limit" (CSL) options to ensure you have the highest possible protection against 2026's rising litigation costs.
Image Gallery
Select an image to open it in a new tab.
Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
