To determine how much life insurance you need, you must calculate the total sum of your immediate financial obligations, such as debts and funeral costs, plus the long-term present value of your future income required to support your dependents. A standard baseline is 10 to 15 times your annual gross income, though a personalized "needs analysis" considering specific mortgage balances and education goals provides the most reliable security.
Determining the appropriate face value for a life insurance policy is one of the most significant financial decisions an individual will make. In 2026, the economic landscape—characterized by evolving healthcare costs, fluctuating interest rates, and the rising price of higher education—makes a "one size fits all" approach increasingly obsolete. Whether you are looking at term life insurance for temporary protection or permanent life insurance for lifelong coverage and estate planning, the goal remains the same: ensuring that those who depend on your income are not left with a financial burden in your absence.
The Traditional Rules of Thumb and Their Limitations
For decades, financial planners have suggested simple multiples of income to help consumers find a starting point. While these rules offer a quick estimate, they often fail to account for the nuances of individual financial lives.
The 10x Income Rule
The most common recommendation is to purchase a policy worth ten times your annual salary. If you earn $100,000 per year, you would buy a $1 million policy. The logic is that if the $1 million is invested at a 5% return, it could theoretically replace $50,000 of your income indefinitely, or provide a higher amount if the principal is slowly drawn down. However, in 2026, with current inflation trends and lower "safe" withdrawal rates, 10x may leave a family short, especially if they have significant debt or young children.
The 10x Plus Education Rule
An evolution of the standard rule suggests taking ten times your income and adding $100,000 to $200,000 per child for future college expenses. This adjustment recognizes that education is often the largest single expense a family faces after a mortgage. While more accurate, it still overlooks specific debt structures and the actual cost of living in different geographic regions.
The DIME Formula: A Detailed Step-by-Step Approach
The DIME method is a comprehensive framework used by insurance professionals to evaluate needs across four critical categories. DIME stands for Debt, Income, Mortgage, and Education. By calculating each of these variables individually, you arrive at a much more precise figure.
1. Debt (Final Expenses and Consumer Debt)
Sum up all your outstanding debts, excluding your mortgage. This includes credit card balances, personal loans, and auto loans. Additionally, you must factor in "final expenses," which include funeral costs and unsettled medical bills. As of 2026, the average cost of a funeral and burial in the United States ranges between $10,000 and $15,000. Ensuring these debts are cleared immediately prevents creditors from pursuing assets that your heirs might need for daily survival.
2. Income Replacement
This is often the largest component of the calculation. Decide how many years your family will need to rely on your income. If you have a newborn, you may want to replace your income for at least 20 years. Multiply your annual take-home pay by the number of years you wish to provide cover. For example, replacing a $75,000 income for 15 years requires $1.125 million. It is important to account for inflation in this step; a dollar in 2026 will not have the same purchasing power in 2041.
3. Mortgage
The primary goal for many families is to remain in their family home. By including the full payoff amount of your mortgage in your life insurance total, you ensure that your survivors can live debt-free. Removing the monthly mortgage payment significantly reduces the "Income Replacement" requirement calculated in the previous step, as housing is typically a household's largest monthly expenditure.
4. Education
Calculate the estimated cost of sending your children to college or vocational school. According to the College Board, the cost of tuition and fees continues to rise annually. In 2026, parents should consider not just current tuition rates but also the projected costs for when their children reach age 18. Factoring in $150,000 to $250,000 per child for a four-year degree at a public university is a common benchmark for conservative planning.

The Human Life Value (HLV) Method
The Human Life Value approach is a more technical economic model often used for high-net-worth individuals or those with complex career trajectories. It focuses on the total earnings an individual is expected to generate throughout their remaining working years.
To calculate HLV, you determine your total future earnings, subtract taxes and the personal expenses you would have consumed (your "cost of maintenance"), and then calculate the present value of that remaining sum. This method is particularly useful for young professionals whose current income is relatively low but who have high future earning potential, such as medical residents or law associates. It ensures that the "economic engine" of the individual is fully insured against premature loss.
Factors That Increase or Decrease Your Coverage Needs
Your stage in life and your existing assets play a massive role in whether you need more or less coverage than the standard formulas suggest.
Existing Assets and "Self-Insurance"
Life insurance is designed to bridge the gap between what your family has and what they need. If you have $500,000 in a 401(k), a significant brokerage account, or high-value real estate, you can subtract these liquid or semi-liquid assets from your total insurance requirement. An individual with $2 million in assets and no debt may only need a small policy for estate liquidity or no insurance at all—a state known as being "self-insured."
The Value of a Non-Earning Spouse
A common and costly mistake is failing to insure a stay-at-home parent. While they do not bring home a paycheck, the services they provide—childcare, household management, transportation, and cooking—have a significant market value. If a stay-at-home parent passes away, the surviving spouse often faces massive new expenses for professional childcare and domestic help. In 2026, the estimated replacement cost for these services can exceed $50,000 to $70,000 annually. A policy of $500,000 or more for a non-earning spouse is often a vital safeguard.
Business Ownership and Buy-Sell Agreements
If you own a business, your life insurance needs extend beyond your family. You may need coverage to fund a buy-sell agreement, allowing your business partners to buy out your share of the company from your heirs at a fair price. Additionally, "Key Person" insurance can provide the business with the liquidity needed to survive the loss of a founder or top executive while searching for a replacement.
Comparing Calculation Methods
The following table compares the different methodologies to illustrate how the resulting coverage amounts can vary based on the chosen strategy.
| Method | Primary Focus | Best For | Typical Coverage Result |
|---|---|---|---|
| Income Multiple | Simplicity | Young singles or those starting out | Low to Moderate |
| DIME Formula | Specific Obligations | Families with mortgages and children | High (Very Targeted) |
| Human Life Value | Lost Potential | High earners and professionals | Very High |
| Capital Retention | Permanent Wealth | Estate planning and legacy | Extreme (Interest-only focused) |
Common Mistakes to Avoid
- Relying Solely on Employer-Provided Life Insurance: Many employers offer a basic policy equal to one or two times your salary. While a great benefit, this is rarely enough. Furthermore, these policies are usually not portable; if you leave your job in 2026, you lose the coverage, potentially at an age where buying a private policy is much more expensive.
- Underestimating the Impact of Inflation: If you buy a 30-year term policy today, the $1 million death benefit will have significantly less purchasing power in 2056. It is often wise to build a small "inflation buffer" into your initial calculation.
- Ignoring "Laddering" Opportunities: You may not need the same amount of insurance for the next 30 years. You might need $1.5 million while the kids are home, but only $500,000 once the mortgage is paid off. "Laddering" involves buying multiple policies of different durations (e.g., a 10-year term and a 20-year term) to reduce costs while maintaining appropriate coverage levels over time.
- Waiting Too Long to Buy: Life insurance premiums are based on age and health. In 2026, as medical underwriting becomes more sophisticated with data from wearables and electronic health records, locking in a rate while you are young and healthy is more critical than ever.
Verification of Requirements and Next Actions
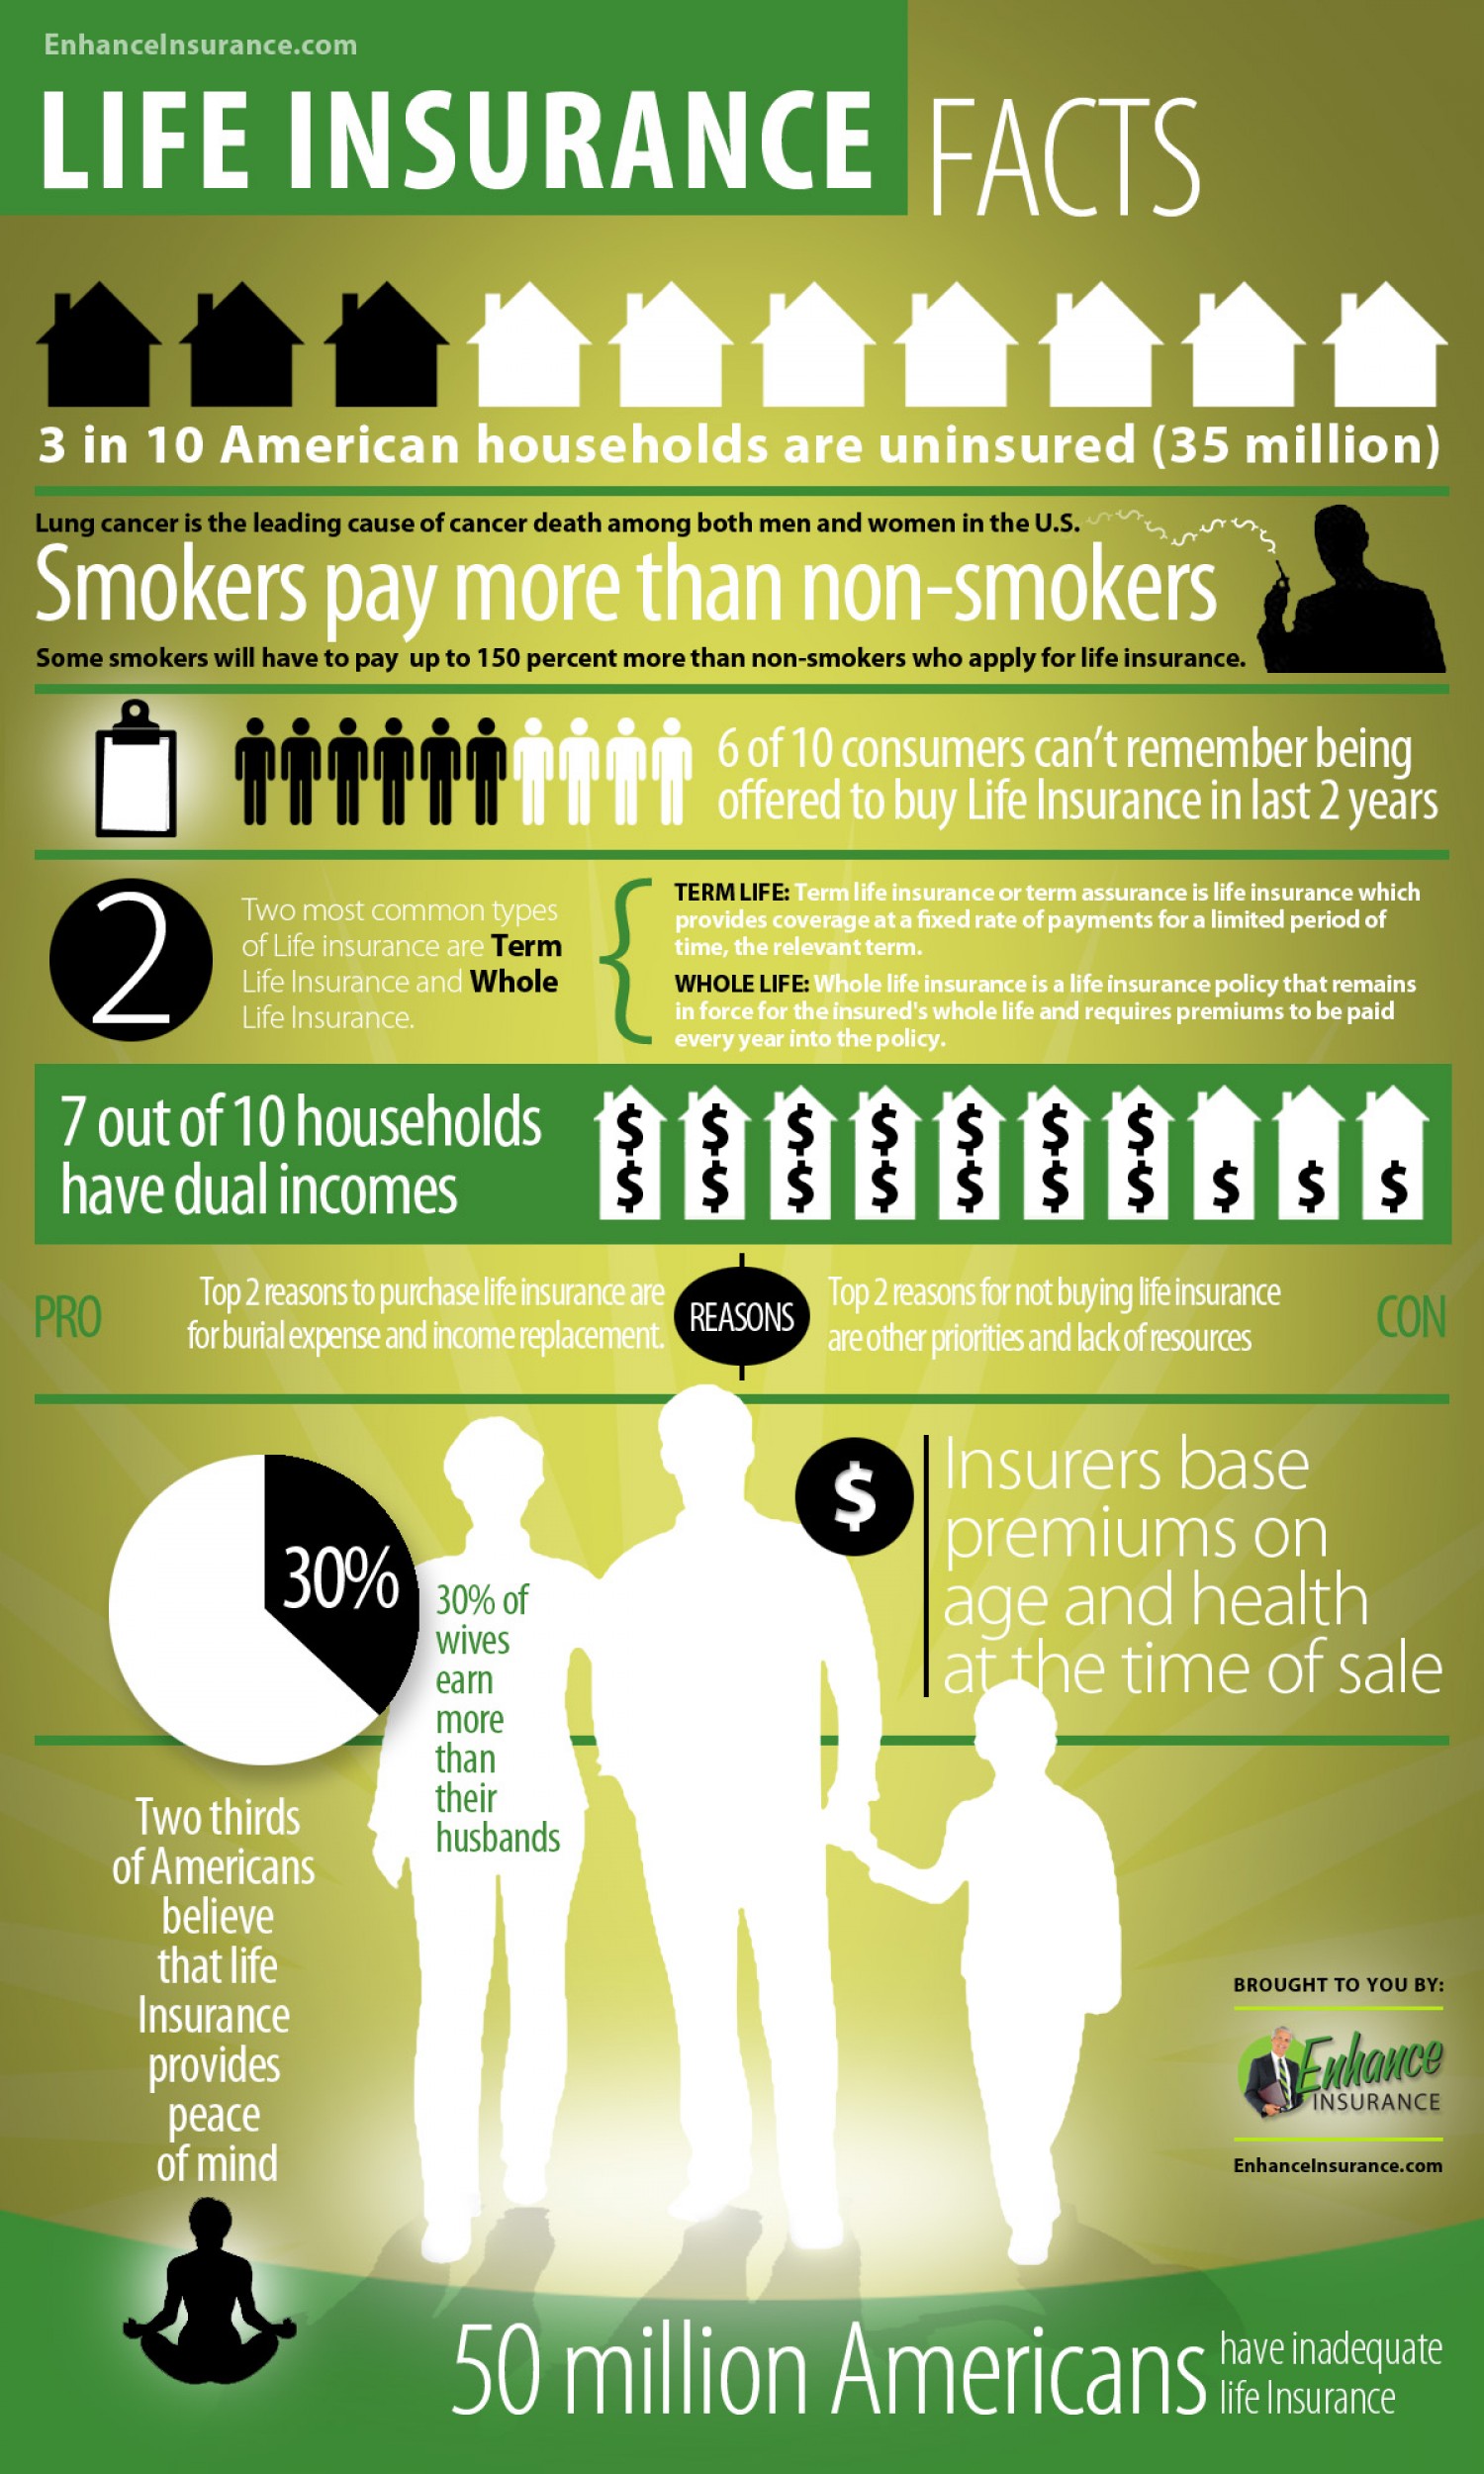
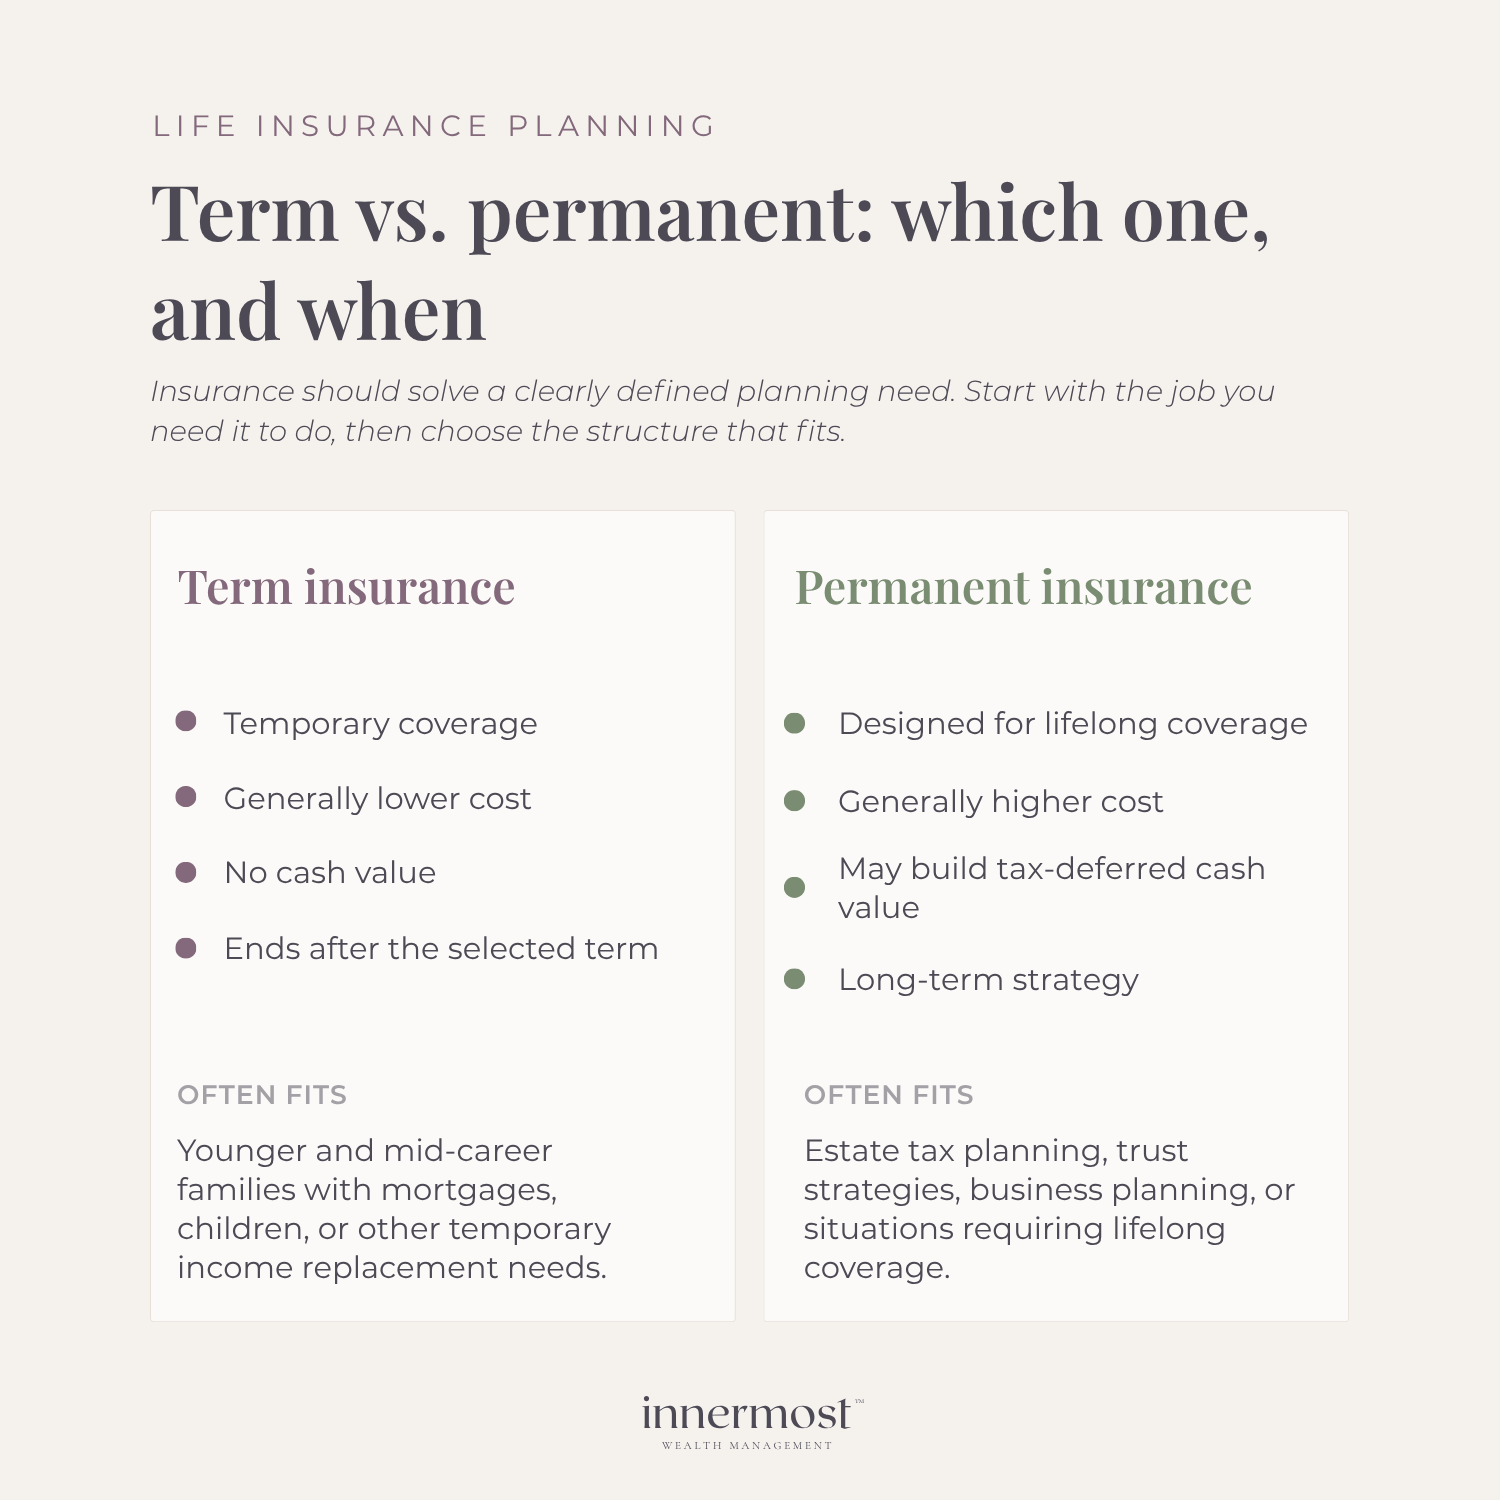
Once you have calculated your number, the next step is verification. Consult with a licensed insurance professional or a fee-only financial planner to review your math. They can help you decide between Term Life, which is affordable and covers a specific period, and Permanent Life (such as Whole or Universal Life), which includes a cash value component and lasts your entire life.
In 2026, the application process for many policies has become "accelerated," meaning you might not need a medical exam if you fall within certain age and health parameters. However, for large policies (typically over $1 million to $2 million), a paramedical exam involving blood work and a physical is still the industry standard for securing the best possible rates.
Frequently Asked Questions
1. Is 10 times my salary enough if I have four children? Usually, no. For larger families, the 10x rule often falls short because the cost of education and multi-decade income replacement for four children is substantial. Using the DIME method will likely show a need closer to 15x or 20x your salary to ensure all children can reach adulthood and complete their education without financial hardship.
2. Should I include my mortgage in the life insurance amount if I have a low interest rate? This depends on your survivor's ability to manage the monthly payments. If your spouse has a high income and can easily cover the mortgage, you might omit the principal payoff to keep your premiums lower. However, providing a debt-free home offers a level of psychological and financial security that is difficult to quantify, which is why most advisors recommend including it.
3. Do I need life insurance if I am single and have no dependents? If no one relies on your income, your need for life insurance is minimal. However, you should still consider a small policy to cover funeral expenses and any co-signed debts (like some private student loans) for which your parents or others might be liable. Additionally, buying a policy while young and healthy "insures your insurability" for the future.
4. Does the "needs analysis" change as I get older? Yes. Your life insurance needs typically follow a bell curve. They are low when you are young and single, peak when you have a large mortgage and young children, and decline as you approach retirement, pay off your debts, and build up your retirement savings. You should re-evaluate your coverage every three to five years or after major life events.
5. Can I use life insurance to pay for estate taxes in 2026? Yes, this is a primary use for permanent life insurance. If your estate exceeds the federal or state inheritance tax thresholds, life insurance provides the necessary liquidity to pay the IRS without forcing your heirs to sell off assets like a family business or real estate at a discount.
Final Recommendation: Do not guess your financial future. Use the DIME method to establish a concrete floor for your coverage needs, then add a 10% buffer for unforeseen economic shifts. Start by obtaining quotes for a 20-year or 30-year term policy, as these offer the most "bang for your buck" in protecting your family's standard of living during your peak earning years.
Image Gallery
Select an image to open it in a new tab.
Declan O'Connor
Higher Education and Campus Culture Reporter
