Fitzgerald Auto Mall Health Insurance Explained: Benefits and Employment Considerations

Employees considering positions at Fitzgerald Auto Mall often inquire about the scope of their health insurance benefits as part of their total compensation package. In the context of automotive retail, which frequently operates under long hours and high-performance demands, understanding the specifics of group health coverage is essential for long-term financial and physical well-being. Fitzgerald Auto Mall provides structured health insurance programs designed to support eligible staff, usually managed through comprehensive group plans that include medical, dental, and vision coverage options.
Understanding Group Health Insurance in Automotive Retail
Automotive dealerships operate under a distinct human resources model. Because Fitzgerald Auto Mall maintains multiple locations and a diverse workforce ranging from sales professionals and service technicians to administrative staff, their health insurance is structured as a group plan. Unlike individual insurance plans purchased on a public exchange, group insurance is a contract between the employer and an insurance carrier.
The primary benefit of this structure for the employee is the employer's contribution toward premiums. By leveraging the collective bargaining power of a large staff, the dealership secures rates that are typically more favorable than those available to individuals. However, understanding your coverage requires looking beyond the monthly premium cost. It involves examining the deductible, out-of-pocket maximums, and the specific network of providers included in the plan.
Eligibility and Enrollment Prerequisites
Eligibility for health insurance at a large dealership network like Fitzgerald Auto Mall is generally predicated on employment status and tenure. Most group plans distinguish between full-time and part-time status.
- Full-Time Employment Status: Benefits are almost exclusively reserved for employees who meet the company’s definition of full-time, typically defined as working a minimum of 30 to 40 hours per week.
- Waiting Periods: New hires should be aware of the "probationary period." It is standard practice in the automotive industry to require a period of service—often 30, 60, or 90 days—before insurance coverage becomes active.
- Open Enrollment: If an employee declines coverage during their initial eligibility window, they may be required to wait for the annual Open Enrollment period to sign up, unless they experience a "qualifying life event" (such as marriage, the birth of a child, or the loss of other coverage).
Components of the Fitzgerald Auto Mall Insurance Package
While specific plan details can shift annually based on renewals, typical corporate insurance packages in this sector include three core pillars: medical, dental, and vision.
Medical Coverage
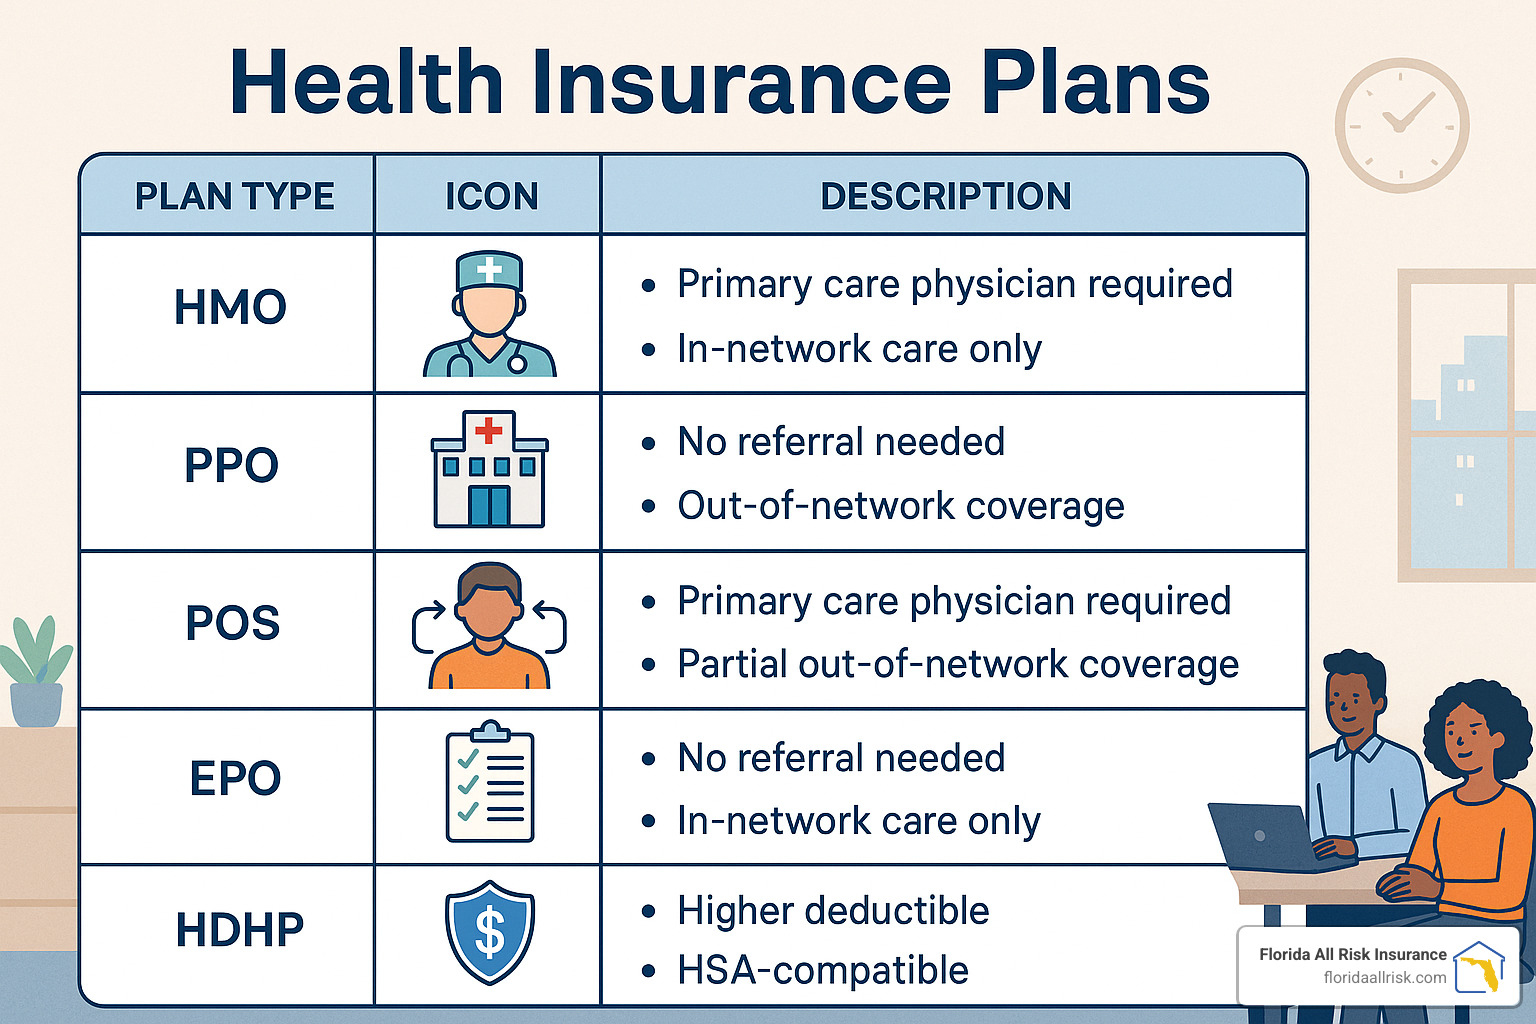
The medical portion is the most significant aspect of the package. These plans typically utilize Preferred Provider Organization (PPO) or Health Maintenance Organization (HMO) networks. A PPO generally offers more flexibility in choosing specialists without requiring referrals but comes with higher premiums. An HMO requires an employee to select a primary care physician (PCP) who coordinates all care, generally resulting in lower premiums but stricter network limitations.
Dental and Vision
Dental and vision benefits are often offered as "ancillary" coverage. Dental plans usually cover preventive care (cleanings and exams) at 100%, while major procedures (crowns or root canals) are covered at a percentage, such as 50% or 80%. Vision insurance often covers a routine eye exam for a small co-pay and provides an allowance for frames, lenses, or contact lenses annually.
Financial Mechanics: Premiums, Deductibles, and Co-pays
Navigating the financial language of health insurance is vital for managing your paycheck deductions.
- Premiums: This is the fixed amount deducted from your paycheck each pay period to maintain the insurance policy. Even if you do not visit the doctor, this amount is non-refundable.
- Deductibles: This represents the amount you must pay out-of-pocket for medical services before the insurance company begins to pay its share. If your deductible is $2,000, you are responsible for the first $2,000 of your medical costs within the plan year.
- Co-payments (Co-pays): These are fixed amounts you pay at the time of service, such as $30 for a primary care visit.
- Out-of-Pocket Maximum: This is the absolute "ceiling" on your costs. Once your deductibles, co-pays, and co-insurance payments reach this limit in a calendar year, the insurance company typically pays 100% of covered expenses for the remainder of the year.
Comparison Table: Common Coverage Structures
The following table outlines how different plan structures generally impact your financial responsibility as an employee.
| Feature | HMO Plan | PPO Plan | High Deductible (HDHP) |
|---|---|---|---|
| Premiums | Lowest | Highest | Low |
| Referrals Needed | Yes | No | No |
| Network Flexibility | Strict (In-Network) | High (Out-of-Network) | Variable |
| Best For | Routine care users | Those wanting flexibility | Healthy individuals (HSA compatible) |
Troubleshooting and Resolution
If an employee encounters issues with their insurance, such as a denied claim or trouble finding a covered provider, the first step is always to consult the Summary of Benefits and Coverage (SBC) document provided by the HR department.
If the problem persists:
- Verify Provider Participation: Always check the current directory of the insurance carrier’s website. A doctor’s status can change from "in-network" to "out-of-network" mid-year.
- Internal HR Inquiry: Fitzgerald Auto Mall’s HR department serves as the intermediary between the employees and the insurance carrier. If a premium is deducted incorrectly or a benefit is not showing as "active" in the carrier’s system, the HR benefits coordinator is the correct point of escalation.
- Appeals Process: If the insurance company denies a claim for a service you believe is covered, you have the right to file an appeal. Keep all documentation, including correspondence with the provider and the insurance company, to build your case.
Frequently Asked Questions
1. Can I change my health insurance plan outside of Open Enrollment? No, typically you cannot change plans unless you have a "Qualifying Life Event." This includes marriage, divorce, birth or adoption of a child, or loss of other health coverage. You usually have 30 days from the date of the event to provide proof and update your enrollment.
2. Is it better to choose an HMO or a PPO? The "better" choice depends on your lifestyle. If you prefer lower monthly costs and don't mind getting referrals for specialists, an HMO is often more economical. If you have a specific specialist you must see or travel frequently, a PPO offers the necessary flexibility, albeit at a higher cost per pay period.
3. Does my insurance cover me at any Fitzgerald Auto Mall location? Health insurance is provided through a carrier (such as CareFirst, Kaiser Permanente, or similar), not by the dealership itself. Your coverage follows you based on the carrier's network, which is generally nationwide or regional, not restricted to the state where you work.
4. What is a Health Savings Account (HSA) and can I get one? An HSA is a tax-advantaged savings account available if you enroll in a High Deductible Health Plan (HDHP). You can contribute pre-tax dollars to pay for qualified medical expenses. The money in an HSA rolls over every year, unlike a Flexible Spending Account (FSA).
5. How do I verify if a doctor is in my network? Never rely solely on a doctor's front desk staff to confirm network status. Always log into your specific insurance carrier’s member portal and use their "Find a Doctor" tool, or call the member services number on the back of your insurance card.
Next Steps for Employees
If you are a current or prospective employee at Fitzgerald Auto Mall, your immediate next step is to request the most recent "Summary of Benefits and Coverage" from the human resources or benefits department. Do not rely on verbal summaries. Read the document to understand what is covered, what the deductibles are, and what the specific premium deductions will be from your check. By understanding these technical details, you can make informed decisions about your compensation and ensure that your healthcare needs are fully supported while you focus on your career in the automotive industry.

Image Gallery
Select an image to open it in a new tab.


Mateo Castillo
Decentralized Finance and E-Payments Strategist
