
Converting 35,000 Indian Rupees (INR) to United States Dollars (USD) requires understanding real-time mid-market exchange rates, assessing provider fees, and selecting a secure transfer or conversion method. Because exchange rates fluctuate continuously based on macroeconomic conditions, the exact USD payout depends heavily on the chosen financial institution, transfer platform, and market timing.
To help you navigate this financial transaction effectively, this guide examines the mechanics of currency conversion, current valuation contexts, fee structures across different channels, and step-by-step strategies to maximize your purchasing power.
Understanding Currency Exchange Basics for INR to USD
The exchange rate between the Indian Rupee and the United States Dollar represents the relative value of India's currency against the world's primary reserve currency. Currency markets operate globally, influencing how much foreign exchange value a specific principal sum holds at any given second.
When you look up a currency conversion online, search engines typically display the mid-market rate. This rate is the midpoint between the buy and sell prices of global currency traders. However, retail consumers rarely receive this exact rate. Banks, currency exchange bureaus, and remittance providers build a margin into the exchange rate—known as a markup—or charge a flat transfer fee to generate revenue.
Therefore, converting 35,000 INR means applying the active commercial exchange rate of the day, adjusting for any applicable service charges, and calculating the final net USD deposited into your destination account or handed to you in physical cash.
Analyzing the Value of 35000 INR in USD
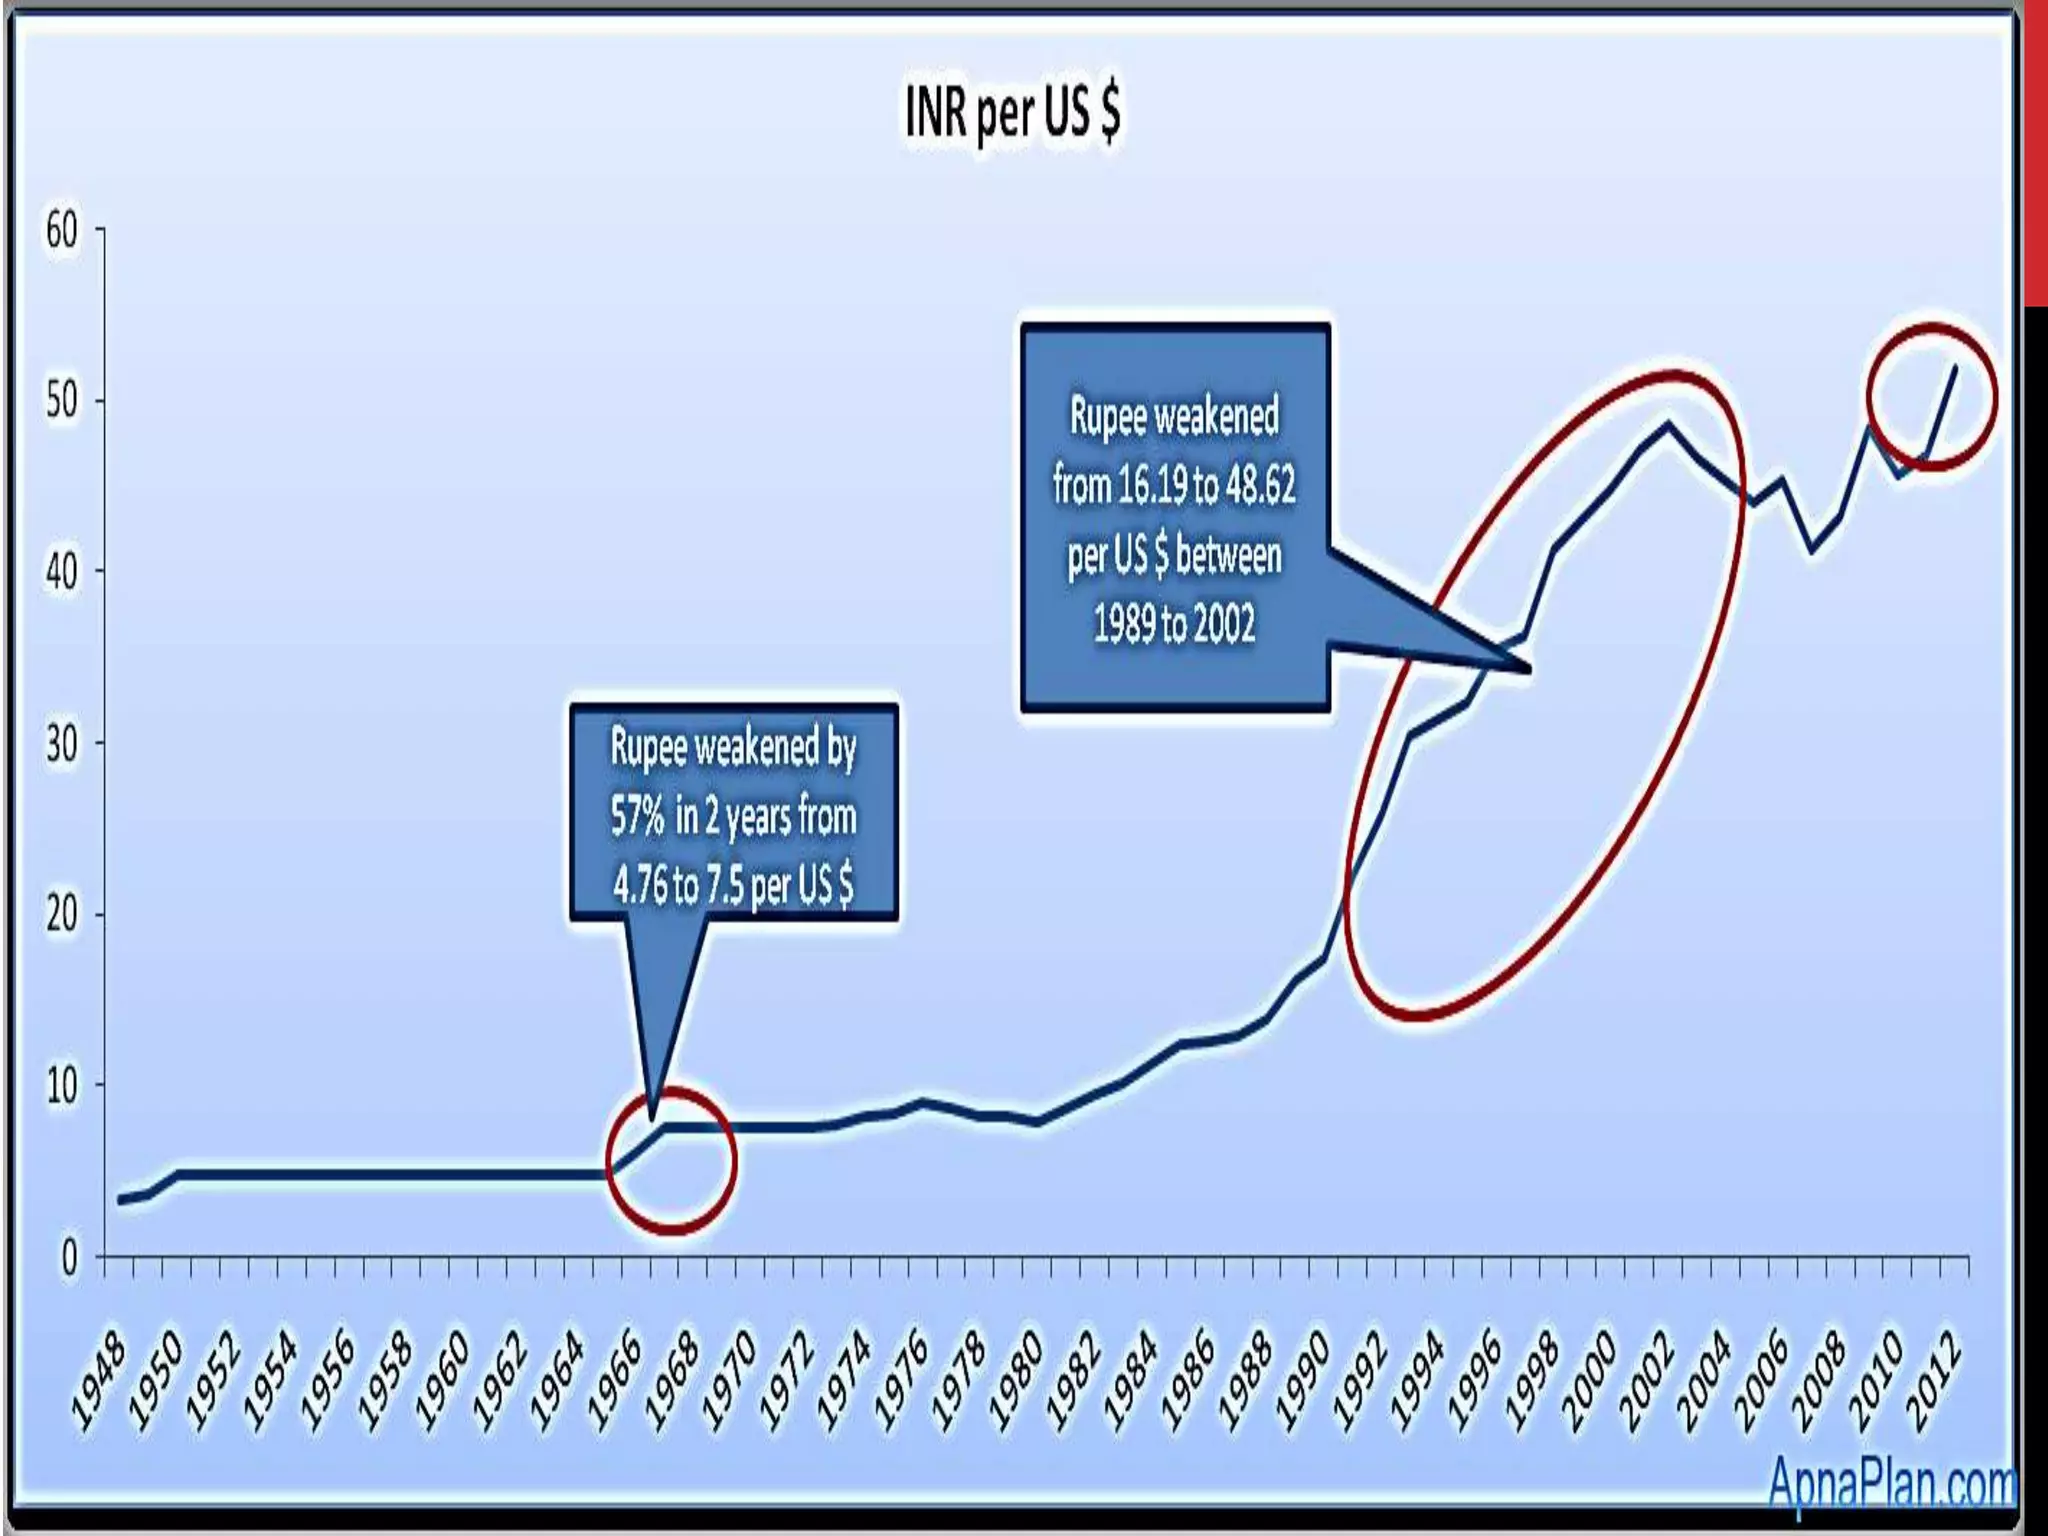
To understand what 35,000 Indian Rupees is worth in United States Dollars, one must look at historical and prevailing macroeconomic trading bands. Foreign exchange rates fluctuate due to interest rate differentials set by the Reserve Bank of India (RBI) and the U.S. Federal Reserve, inflation rates, trade deficits, and geopolitical events.
Because currency values change dynamically every business day, relying on static calculations can result in miscalculations for budgeting or international payments. To find the exact value at the exact moment of your transaction, you should reference a live currency feed or execute a rate calculation through a regulated financial provider.
To provide clarity on how different exchange rates impact your final amount, the following table illustrates potential outcomes based on various hypothetical market rates:
| Exchange Rate (INR to USD) | Gross USD Equivalent for 35,000 INR | Typical Fee Impact | Estimated Net USD Payout |
|---|---|---|---|
| 1 USD = 82.50 INR | $424.24 | Variable (1% to 3%) | $411.51 - $420.00 |
| 1 USD = 83.00 INR | $421.69 | Variable (1% to 3%) | $409.04 - $417.47 |
| 1 USD = 83.50 INR | $419.16 | Variable (1% to 3%) | $406.58 - $414.97 |
| 1 USD = 84.00 INR | $416.67 | Variable (1% to 3%) | $404.17 - $412.50 |
Note: The figures above are illustrative. Actual payouts depend entirely on the live mid-market rate and the fee schedule of your chosen provider at the exact time of execution.
Methods and Channels to Convert 35000 Indian Rupees to USD
When you need to perform this conversion, you have several primary channels available. Each option varies in speed, transparency, hidden costs, and overall convenience.
1. Specialized Money Transfer Services
Modern digital remittance platforms—such as Wise, Remitly, or OFX—often provide a more cost-effective alternative to traditional banks. These platforms typically use the true mid-market exchange rate or a very transparent small markup, combined with a clear, upfront transfer fee. For a sum like 35,000 INR, these services frequently yield a higher net USD amount than high street commercial banks.
2. Traditional Commercial Banks
Executing a wire transfer through major Indian banks (such as HDFC, ICICI, or State Bank of India) to a U.S. bank account is secure and compliant with regulatory frameworks. However, traditional banks often apply a dual-cost structure: an outward remittance fee, a correspondent bank fee, and a significant markup on the exchange rate. While reliable for large enterprise transactions, these cumulative costs can diminish the net USD return on a moderate amount like 35,000 INR.
3. Multi-Currency Accounts and Digital Wallets
If you frequently hold multiple currencies, digital wallets like PayPal or specialized multi-currency accounts allow you to receive, hold, and convert funds. While convenient for online commerce, PayPal and similar payment gateways carry higher currency conversion spreads (often ranging between 3% and 4% above the base rate), making them less economical for direct peer-to-peer or bank-to-bank transfers.
4. Physical Currency Exchange Bureaus
If your goal is to convert 35,000 INR into physical USD cash for travel, authorized dealers and airport exchange booths are available. Airport kiosks generally offer the least favorable exchange rates and high commission fees. Local, licensed money changers in major metropolitan areas usually offer better rates, though physical cash conversions almost always cost more than electronic bank transfers.
Step-by-Step Guide to Executing Your Conversion
To ensure your funds are transferred safely and economically, follow a structured process from start to finish:
- Verify the Live Mid-Market Rate: Check a trusted financial data source like Bloomberg or Reuters to establish the baseline exchange rate for INR to USD on the day of your transaction.
- Compare Provider Quotes: Check at least two or three digital transfer services and your bank to compare their total costs. Do not look only at the fee; check the exchange rate offered to see the total net USD you will receive.
- Gather Required Documentation: If you are sending funds internationally from India, compliance regulations under the Liberalised Remittance Scheme (LRS) or outward remittance rules require a PAN card, KYC verification, and a stated purpose of remittance (e.g., family maintenance, education, travel).
- Initiate the Transfer: Enter the recipient's details (such as IBAN, SWIFT/BIC code, and account number for a U.S. bank) and lock in the transfer rate if the provider offers a rate-locking feature.
- Monitor and Confirm: Keep track of the tracking number or reference code provided by your financial service until the funds clear in the destination account.
Common Mistakes to Avoid
Navigating currency exchange requires careful attention to detail. Avoid these frequent pitfalls to protect the value of your funds:
- Ignoring the Exchange Rate Markup: Focusing solely on a "zero transfer fee" promotion without checking the underlying exchange rate. A provider offering zero fees often recovers costs by embedding a heavy markup into the currency conversion rate.
- Failing to Account for Intermediary Bank Fees: For traditional wire transfers, correspondent banks situated between the sending and receiving institutions may deduct intermediary fees from the final payout amount.
- Overlooking Regulatory Compliance: Neglecting to declare the correct purpose of remittance or failing to provide accurate KYC documents, which can cause banks to freeze or delay the transaction.
- Timing Mismanagement: Submitting conversion requests during weekends or market holidays when foreign exchange liquidity is lower, which can sometimes result in wider spreads.
Frequently Asked Questions
What is the exact USD amount for 35000 INR?
Because foreign exchange markets trade continuously, the exact USD amount changes every second. You can determine the precise amount by multiplying 35,000 by the live mid-market exchange rate for the day, keeping provider fees and markups in mind.
Is it better to use a bank or an online transfer service for 35000 INR?
For a moderate amount like 35,000 INR, specialized online transfer services generally provide better exchange rates and lower overall fees compared to traditional commercial banks, resulting in a higher net USD payout.
Are there taxes or reporting requirements when sending INR abroad from India?
Yes. Outward remittances from India are subject to guidelines set by the Reserve Bank of India. Depending on the purpose of the remittance, Tax Collected at Source (TCS) may apply under specific financial thresholds. Consult a qualified tax professional or your bank's forex desk for compliance details.
How long does it take to convert and transfer 35000 INR to a U.S. bank account?
Depending on the provider, digital money transfer services typically complete the process within 24 to 48 hours. Traditional bank wire transfers can take anywhere from 2 to 5 business days, depending on intermediary banking networks and time zone differences.
Can I convert 35000 INR to USD cash at an airport?
Yes, airport currency exchange booths allow you to buy USD cash, but they almost universally offer the least favorable exchange rates and highest service fees. It is far more economical to use a local authorized dealer or withdraw USD from a multi-currency account abroad.
Conclusion and Next Actions
Converting 35,000 Indian Rupees to United States Dollars is a straightforward financial task, provided you look beyond surface-level fee claims and examine the net exchange rate. Your best course of action is to check the live mid-market rate, compare net payouts across two reputable digital remittance platforms and your bank, ensure your compliance documentation is ready, and execute the transfer during regular business hours to secure the most efficient rate possible.
Image Gallery
Select an image to open it in a new tab.


Zara El-Hashem
Sociocultural Dynamics and Academics Writer
