Understanding AARP Permanent Life Insurance: Features, Suitability, and Coverage

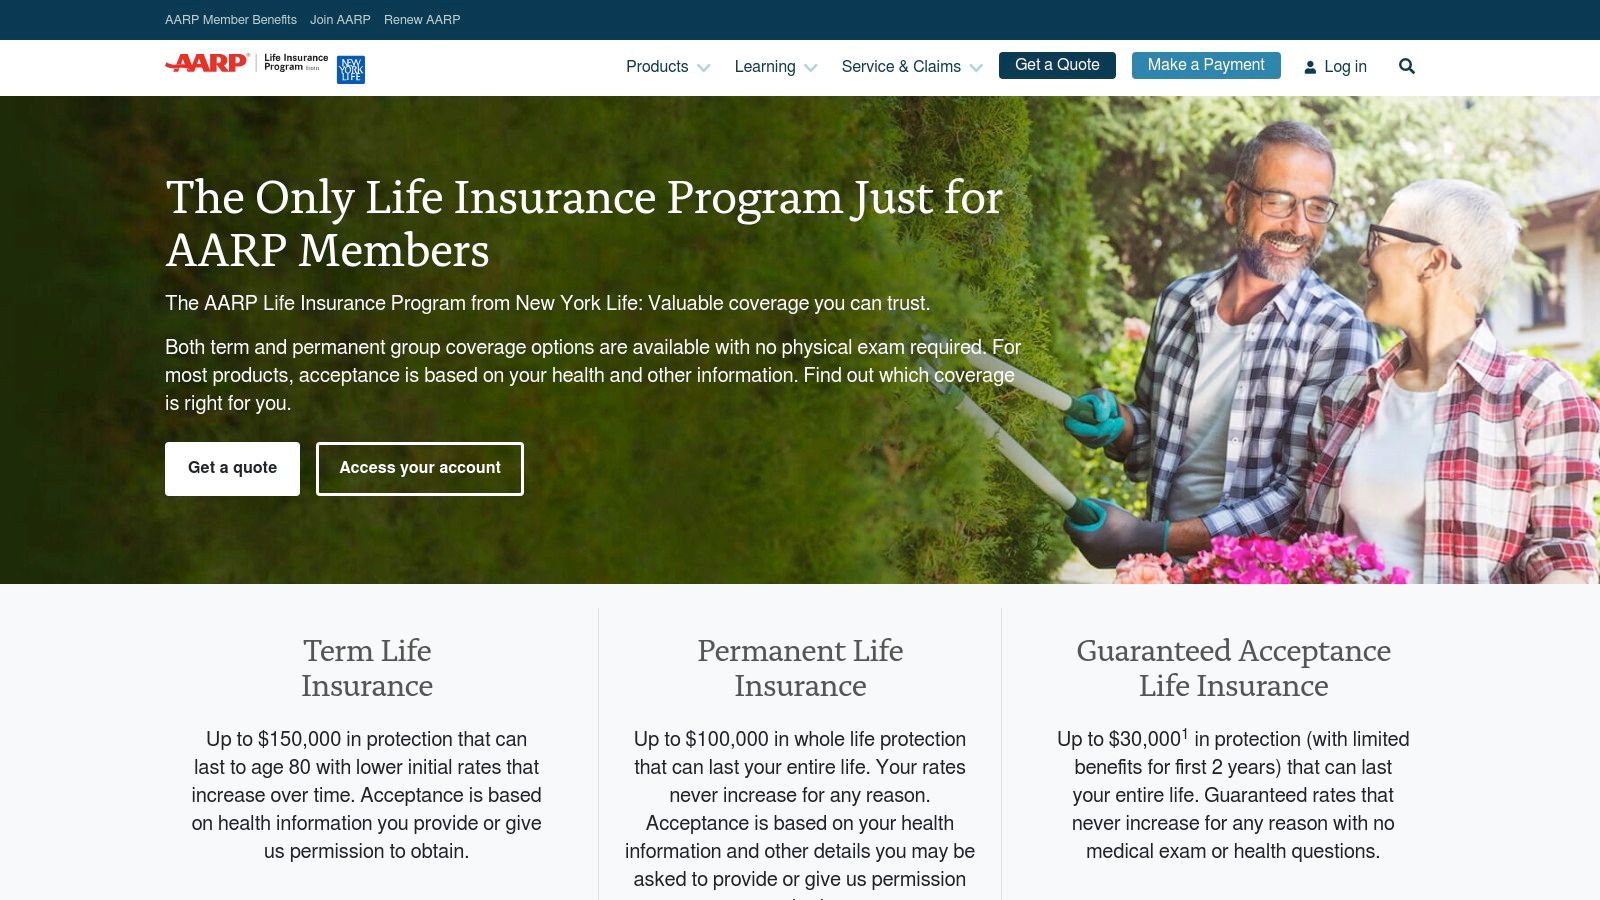
AARP Permanent Life Insurance, which is underwritten by New York Life Insurance Company, is a whole life insurance product designed for older adults. It provides guaranteed coverage for the remainder of the policyholder's life, builds cash value over time, and features level premiums that remain the same regardless of age or health changes after the policy is issued.
The Role of Permanent Life Insurance for AARP Members
Permanent life insurance—often referred to as "whole life"—differs significantly from term life insurance. While term insurance is designed to cover a specific period (such as until a mortgage is paid off or children reach adulthood), permanent insurance is intended to remain in effect until the end of the policyholder’s life, provided that the premiums are paid as required.
For the AARP program, the goal is to provide a financial safety net that covers end-of-life expenses. By offering a product that does not expire as long as the policy is in force, AARP aims to provide peace of mind to seniors who may be concerned about leaving behind debts, final medical bills, or funeral expenses. Because the policy is underwritten specifically for the AARP membership, it is tailored to address the unique needs of individuals in their 50s, 60s, and beyond.
How AARP Permanent Life Insurance Functions
The mechanics of this insurance are built on stability and predictability. When an individual purchases an AARP Permanent Life Insurance policy, they enter a contractual agreement where the insurer promises to pay a specific death benefit to the designated beneficiary upon the insured's passing.
- Guaranteed Level Premiums: One of the most critical aspects of this product is that the premium amount does not increase over time. If you enroll at age 60, the premium you pay is the same at age 80, provided the policy remains active. This is an essential feature for retirees living on fixed incomes who require predictable monthly or annual outlays.
- Death Benefit: The policy pays a tax-free lump sum to beneficiaries. This money can be used for any purpose, including settling estate taxes, covering funeral or burial costs, or providing a cash inheritance.
- Accumulated Cash Value: Unlike term insurance, which has no value if you outlive the policy term, this permanent policy includes a "cash value" component. A portion of the premiums paid contributes to a cash account that grows over time according to the policy's terms. Policyholders may be able to borrow against this cash value, which serves as a potential emergency financial resource.
Eligibility and Enrollment Requirements
To be eligible for an AARP-branded life insurance product, you must be a member of AARP. Membership is open to anyone age 50 or older, though younger individuals may join under specific circumstances.
Regarding the life insurance product itself, potential policyholders must meet age requirements typically ranging from 50 to 80 years old, depending on the specific state and underwriting guidelines. Unlike some simplified-issue or guaranteed-acceptance products that require no health questions, the underwriting process for AARP permanent life insurance may involve a health assessment. This does not necessarily require a full medical examination, but applicants will be asked to answer health-related questions.
The accuracy of these answers is paramount. Providing incomplete or incorrect information during the application process can lead to the denial of a claim later, or the cancellation of the policy.
Financial Considerations and Cost Structure
The cost of AARP Permanent Life Insurance is influenced by several variables, most notably the age at which the policy is purchased and the face amount (the total death benefit) requested.
- Age of Issuance: Buying a policy at age 55 will invariably result in a lower premium than purchasing the same amount of coverage at age 75. Because the premium is locked in for life, there is a distinct financial incentive to enroll as early as possible once the need for coverage is identified.
- Face Amount: The death benefit amount is chosen by the policyholder. Higher coverage amounts result in higher monthly premiums. It is important to calculate the actual need—covering funeral costs, for example, typically requires significantly less capital than providing an inheritance for heirs.
- Payment Frequency: Most policies offer flexibility in payment cycles, allowing policyholders to choose between monthly, quarterly, or annual payments, depending on their financial planning preferences.
Comparison Table: Term vs. Permanent Insurance
The following table outlines the key differences between these two common types of life insurance to help clarify why an applicant might choose one over the other.
| Feature | Term Life Insurance | Permanent (Whole) Life Insurance |
|---|---|---|
| Duration | Specific term (e.g., 10, 20 years) | Lifetime coverage |
| Premiums | Generally low, but rise if renewed | Fixed/Level for the life of the policy |
| Cash Value | None | Yes, accumulates over time |
| Primary Goal | Temporary financial protection | Permanent coverage & wealth transfer |
| Death Benefit | Only during the term | Guaranteed upon death |
Risks and Limitations
While permanent life insurance offers stability, it is not a "one-size-fits-all" solution. Prospective policyholders should be aware of the following limitations:
- Surrender Charges: If a policyholder decides to cancel the policy early, they may be subject to surrender charges, which can reduce or eliminate the cash value returned to them.
- Opportunity Cost: Because permanent insurance is significantly more expensive than term insurance, some financial advisors argue that the difference in premium could be better invested elsewhere. This depends entirely on the individual’s risk tolerance and financial goals.
- Fixed Benefit Amounts: Inflation can erode the "real" value of a fixed death benefit over many decades. A $25,000 policy purchased in 2026 may not cover the same amount of funeral services in 2046 as it does today.
Common Questions Regarding AARP Life Insurance
Does AARP offer life insurance directly? No. AARP does not act as the insurer. The policies are underwritten by New York Life Insurance Company. AARP provides the platform and endorsement, but the legal contract and insurance risk reside with New York Life.
Can I be denied coverage? Yes. While the program is designed to be accessible, it is not a "guaranteed issue" policy. Applicants must answer health questions, and coverage is subject to medical underwriting. Pre-existing conditions may affect eligibility or premiums.
What happens if I stop paying my premiums? If premiums are not paid within the grace period, the policy may lapse. Depending on the cash value accumulated, some policies may offer options like "reduced paid-up" insurance, which keeps a smaller death benefit in force without further premium payments. You should review your specific policy contract for these provisions.
How is the cash value accessed? Policyholders can generally take out policy loans against the cash value. Interest will be charged on these loans, and any outstanding balance will be deducted from the death benefit when the policyholder passes away.
Is the death benefit taxable? Generally, life insurance death benefits paid to beneficiaries are not subject to federal income tax. However, you should consult with a tax professional regarding your specific estate and financial situation, as local or inheritance tax laws may vary.
Next Actions for Prospective Policyholders
If you are considering AARP Permanent Life Insurance, your first step should be a thorough assessment of your financial goals. Identify exactly why you need the insurance. If your primary goal is to pay for funeral expenses, a smaller, lower-cost policy may suffice. If you wish to leave a legacy for your family, you may need a higher face amount.
Once your goals are defined, request a quote through the official AARP-sponsored channels or directly via New York Life. Carefully review the "Policy Summary" and "Prospectus" documents before signing. These documents outline the exact costs, benefits, and exclusions of the policy. Finally, ensure your beneficiaries are aware of the policy’s existence and know how to contact the insurer, as this will significantly streamline the claims process when the time comes.

Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
