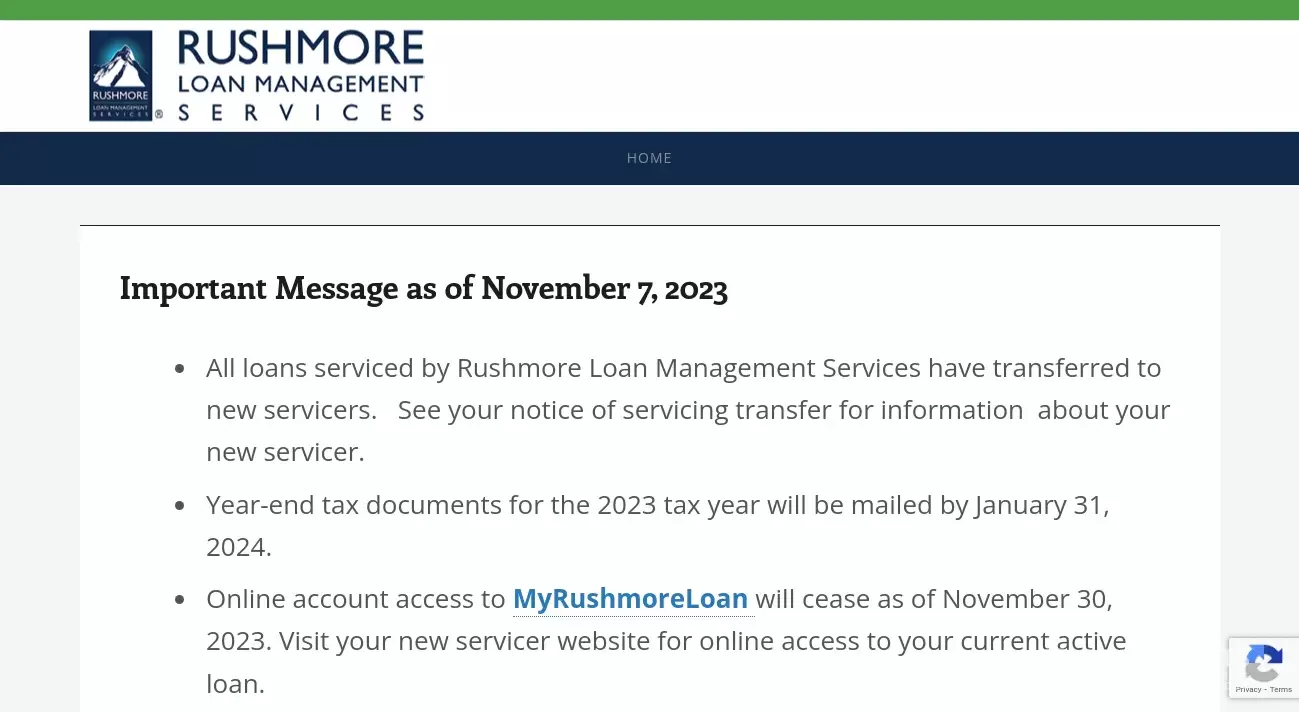
Rushmore Loan Services functions as a specialized mortgage loan servicer that manages home loans, processes monthly payments, and handles loss mitigation or default administration for properties across the United States, including local neighborhoods throughout Detroit, Michigan. For homeowners in Detroit navigating regional housing market fluctuations, localized economic shifts, or financial hardships, understanding how Rushmore operates provides clarity on payment processing, customer communication, escrow account management, and potential foreclosure prevention options.
The Core Functions of a Mortgage Servicer in the Housing Market
To understand the role of Rushmore Loan Services, it is first necessary to distinguish between a mortgage lender and a mortgage servicer. A lender originates the loan, provides the initial capital, and closes the transaction. Conversely, a servicer manages the ongoing administration of that loan throughout its lifecycle. Rushmore does not typically originate the original mortgage; rather, it acts as an intermediary between the borrower and the investor or trust that currently owns the mortgage-backed security.
For Detroit property owners, this distinction matters because interactions regarding monthly payments, escrow shortages, payoff statements, and hardship applications are directed to the servicer rather than the originating bank. When a mortgage is transferred, sold, or placed into a securitized pool managed by a specific trustee, companies like Rushmore are appointed to collect principal and interest, manage tax and insurance escrow accounts, and distribute funds to the appropriate financial institutions.
Key Responsibilities Managed by Rushmore Loan Services
- Payment Processing and Ledger Maintenance: Allocating incoming monthly payments toward principal, interest, hazard insurance, and property taxes, while maintaining accurate ledger histories.
- Escrow Account Administration: Managing property tax payments and homeowner's insurance premiums, which is particularly vital in Detroit given fluctuating municipal millage rates and local assessment practices.
- Customer Service and Account Inquiries: Providing communication channels for borrowers to obtain payoff quotes, request amortization schedules, or update contact and vesting information.
- Default Management and Loss Mitigation: Evaluating struggling borrowers for alternative repayment plans, loan modifications, forbearances, or short sales when financial distress occurs.
Navigating Property Taxes and Escrow in Detroit
Homeowners in Detroit face a distinct local tax landscape characterized by property assessment adjustments, specific municipal tax calendars, and historical efforts by the city to reform tax foreclosure rates. Rushmore Loan Services oversees escrow accounts to ensure that annual city and county property taxes, along with required hazard insurance, are paid on time to prevent tax liens or lapses in coverage.
When a borrower's escrow analysis reveals a shortage—often caused by rising property assessments or increases in local insurance premiums—Rushmore recalculates the monthly payment to spread the deficit over a 12-month period, or occasionally an alternative term depending on investor guidelines and state regulations. Detroit residents must monitor their annual property tax assessments issued by the City of Detroit Office of the Assessor and verify that escrow disbursements made by Rushmore align with local tax billing cycles to avoid unexpected adjustments.
Common Escrow Management Tasks
- Annual Escrow Analysis: Reviewing past disbursements and projected costs to determine if adjustments are required for the upcoming year.
- Tax Disbursement Tracking: Ensuring payments are remitted to the Wayne County Treasurer or the City of Detroit tax collection entities before statutory deadlines.
- Insurance Verification: Maintaining active hazard and flood insurance policies to protect the collateral against physical damage or environmental risks common to the region.
Loss Mitigation and Default Resolution Options
Financial instability, economic disruption, or personal hardship can lead borrowers to fall behind on their mortgage payments. When this occurs on a loan serviced by Rushmore, the company administers loss mitigation programs designed to evaluate whether the homeowner can retain the property or achieve an orderly transition out of it. Because Detroit has experienced distinct economic recovery cycles alongside periods of high foreclosure activity in past decades, structured loss mitigation is a central component of regional mortgage servicing operations.
Borrowers experiencing hardship must submit a complete loss mitigation application to be evaluated under Real Estate Settlement Procedures Act (RESPA) guidelines and specific investor rules. Rushmore reviews these applications to determine eligibility for various relief programs, ranging from short-term payment pauses to permanent restructuring of loan terms.
Loss Mitigation Programs Offered by Servicers
- Forbearance Agreements: Temporary suspension or reduction of monthly mortgage payments for a defined period, followed by a plan to make up the missed amounts.
- Repayment Plans: Spreading past-due amounts over a set number of months by adding a portion of the arrears to the regular monthly payment.
- Loan Modifications: Permanently altering the terms of the mortgage—such as extending the maturity date, lowering the interest rate, or capitalizing arrearages—to establish a sustainable monthly payment.
- Short Sales and Deeds-in-Lieu: Assisting borrowers who cannot afford to retain the property in selling the home for less than the balance owed or deeding it back to the lender to avoid a formal foreclosure sale.
The Mortgage Servicing Transfer Process
Homeowners frequently discover Rushmore Loan Services because their mortgage was transferred from another financial institution or subservicer. Under federal law, specifically the Truth in Lending Act (TILA) and RESPA, both the transferring servicer and the receiving servicer must provide written notices at least 15 days before the effective transfer date.
When a transfer occurs for a property in Detroit, borrowers receive a "Notice of Assignment, Sale, or Transfer of Servicing Rights." This document outlines the effective date, contact information for Rushmore, and assurances that the terms and conditions of the underlying promissory note and mortgage remain unchanged. During a transition, a 60-day grace period applies under federal law, ensuring that payments mistakenly sent to the previous servicer are not assessed late fees.
Steps to Take Upon Receiving a Servicing Transfer Notice
- Update Payment Portals: Register on the Rushmore online customer portal to set up electronic payments or verify automatic draft settings.
- Review Existing Direct Debits: Cancel automated clearing house (ACH) payments with the old servicer to prevent double-drafting errors.
- Confirm Escrow and Loan Terms: Compare the initial billing statement from Rushmore against your final statement from the previous servicer to verify that the remaining principal balance, escrow reserve, and interest rate match accurately.
Communication Channels and Account Verification
Effective communication with Rushmore Loan Services requires understanding the proper channels for submitting documentation, disputing billing errors, or requesting assistance. Borrowers should rely on official contact details found on monthly billing statements or verified corporate disclosures rather than unverified third-party sources or online forums.
When submitting formal inquiries or loss mitigation documents, sending certified mail with return receipt requested or utilizing secure messaging through the official online portal creates a verifiable paper trail. This documentation protects homeowners in the event of disputes regarding missing payments, processing delays, or misapplied escrow funds.
Summary of Mortgage Servicing Entities and Functions
| Entity Type | Primary Responsibility | Interaction Point for Detroit Homeowners |
|---|---|---|
| Originating Lender | Evaluates credit, issues funds, and closes the initial mortgage loan. | Limited after closing, unless holding portfolio loans. |
| Mortgage Servicer (e.g., Rushmore) | Collects payments, manages escrow, handles customer service, and processes loss mitigation. | Primary point of contact for daily management, payoffs, and hardship relief. |
| Investor / Trustee | Owns the beneficial interest in the mortgage-backed security or loan pool. | Rarely interacts directly with borrowers; establishes servicing guidelines. |
| Local Municipal Authority | Levies property taxes, enforces municipal codes, and records land titles (e.g., Wayne County). | Interacts via tax assessments and recorded deeds or liens. |
Frequently Asked Questions
What should I do if my mortgage was sold to Rushmore Loan Services?
Review the transfer notice carefully for the effective date, verify that your automatic payment setups are redirected to Rushmore, and log into their official portal to confirm your loan details, escrow balance, and contact information match your records.
How does Rushmore handle Detroit property taxes?
Rushmore collects a portion of your estimated annual property taxes with each monthly mortgage payment, holding those funds in an escrow account until local tax bills are due. They then remit payment directly to the appropriate municipal or county tax collection authority in Detroit.
What are my options if I cannot make my monthly payment to Rushmore?
Contact Rushmore's loss mitigation department immediately to request a loss mitigation application. Depending on your investor guidelines, you may qualify for a forbearance plan, a repayment plan, or a permanent loan modification.
Can Rushmore foreclose on a home in Detroit if payments stop?
Yes. Like all mortgage servicers, if a borrower defaults on the promissory note and fails to resolve the delinquency or secure a loss mitigation alternative, Rushmore can initiate foreclosure proceedings on behalf of the loan investor in accordance with Michigan state law and local judicial procedures.
How can I verify that my payment was credited correctly?
Log into the secure online customer portal provided by Rushmore or review your monthly billing statements. Ensure that payments are allocated correctly between principal, interest, and escrow, and keep transaction confirmation numbers for your records.
Next Actions for Homeowners
Homeowners in Detroit interacting with Rushmore Loan Services should proactively review their monthly statements, verify escrow account accuracy against municipal tax assessments, and maintain open communication if financial challenges arise. For complex disputes or formal legal questions regarding mortgage servicing rights or foreclosure defense, consult with a qualified housing counselor certified by the U.S. Department of Housing and Urban Development (HUD) or a licensed real estate attorney in Michigan.
Image Gallery
Select an image to open it in a new tab.

Simon Caldwell
Enterprise Technology and Systems Editor
