
The cash value landscape within New York Life (NYL) insurance policies represents a sophisticated financial reservoir built into permanent life insurance products. Primarily associated with whole life and universal life policies, this cash value serves as a tax-advantaged accumulation account that grows over time through guaranteed interest, market performance, or non-guaranteed dividends. In 2026, navigating this landscape requires a deep understanding of how New York Life’s mutual company structure influences growth, the specific mechanics of accessing funds, and the long-term tax implications of various policy maneuvers.
The Foundations of Cash Value at New York Life
To understand the New York Life cash value landscape, one must first recognize the institutional framework of the company. As a mutual insurance company, New York Life is owned by its policyholders rather than outside shareholders. This structure is the bedrock of their cash value proposition, particularly for whole life policyholders who are eligible to receive a portion of the company’s "divisible surplus" in the form of dividends.
Cash value is essentially the "living benefit" of a permanent life insurance policy. Unlike term life insurance, which only pays out upon the death of the insured, permanent policies allocate a portion of every premium payment toward an internal equity account. In the early years of a policy, a significant portion of the premium covers the cost of insurance (COI) and administrative fees. As the policy matures, the efficiency of the cash value accumulation typically increases, aided by the power of compound interest and, in the case of New York Life, consistent dividend payments.
The Mutual Advantage and Divisible Surplus
The "landscape" is heavily influenced by NYL's ability to remain financially robust. Because there are no stockholders to pay, the company directs excess profits—after meeting obligations, expenses, and contingency reserves—back to its participating policyholders. While dividends are never guaranteed, New York Life has paid them every year since 1854. This track record provides a level of predictability that is central to the financial planning strategies of many policyholders in 2026.
Types of New York Life Policies with Cash Value
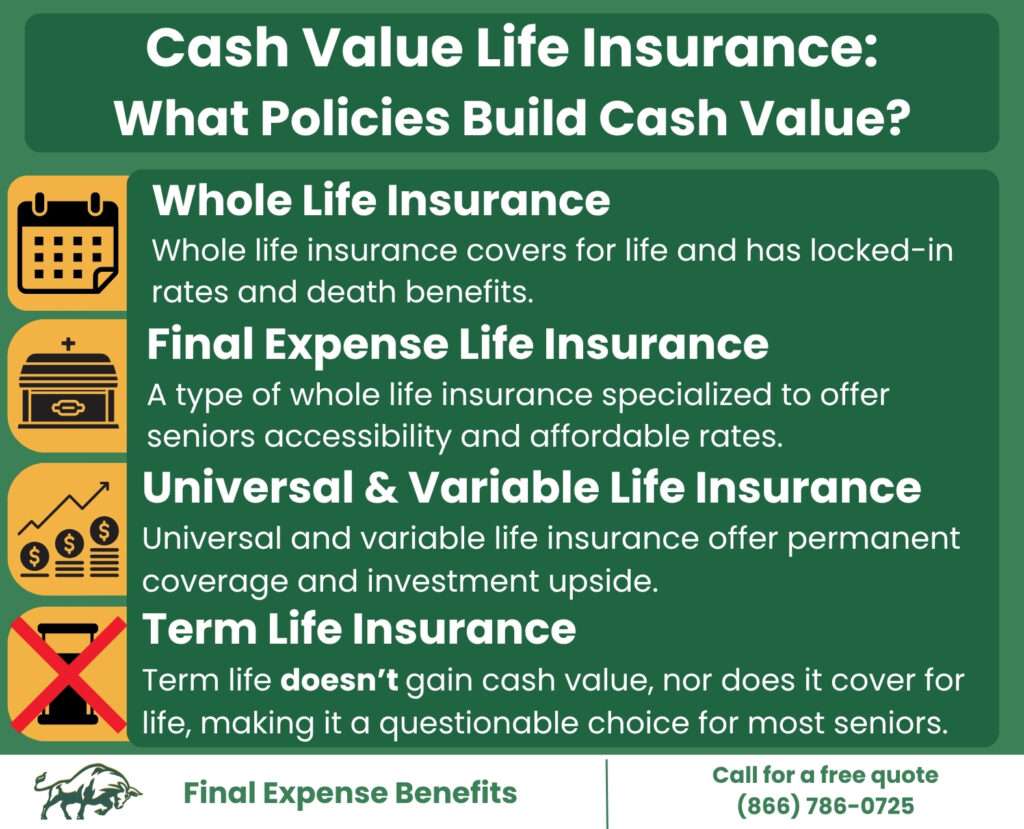
The mechanics of how cash value grows and is managed depend entirely on the specific product chosen. New York Life offers several "containers" for cash value, each with distinct risk profiles and growth engines.
Whole Life Insurance
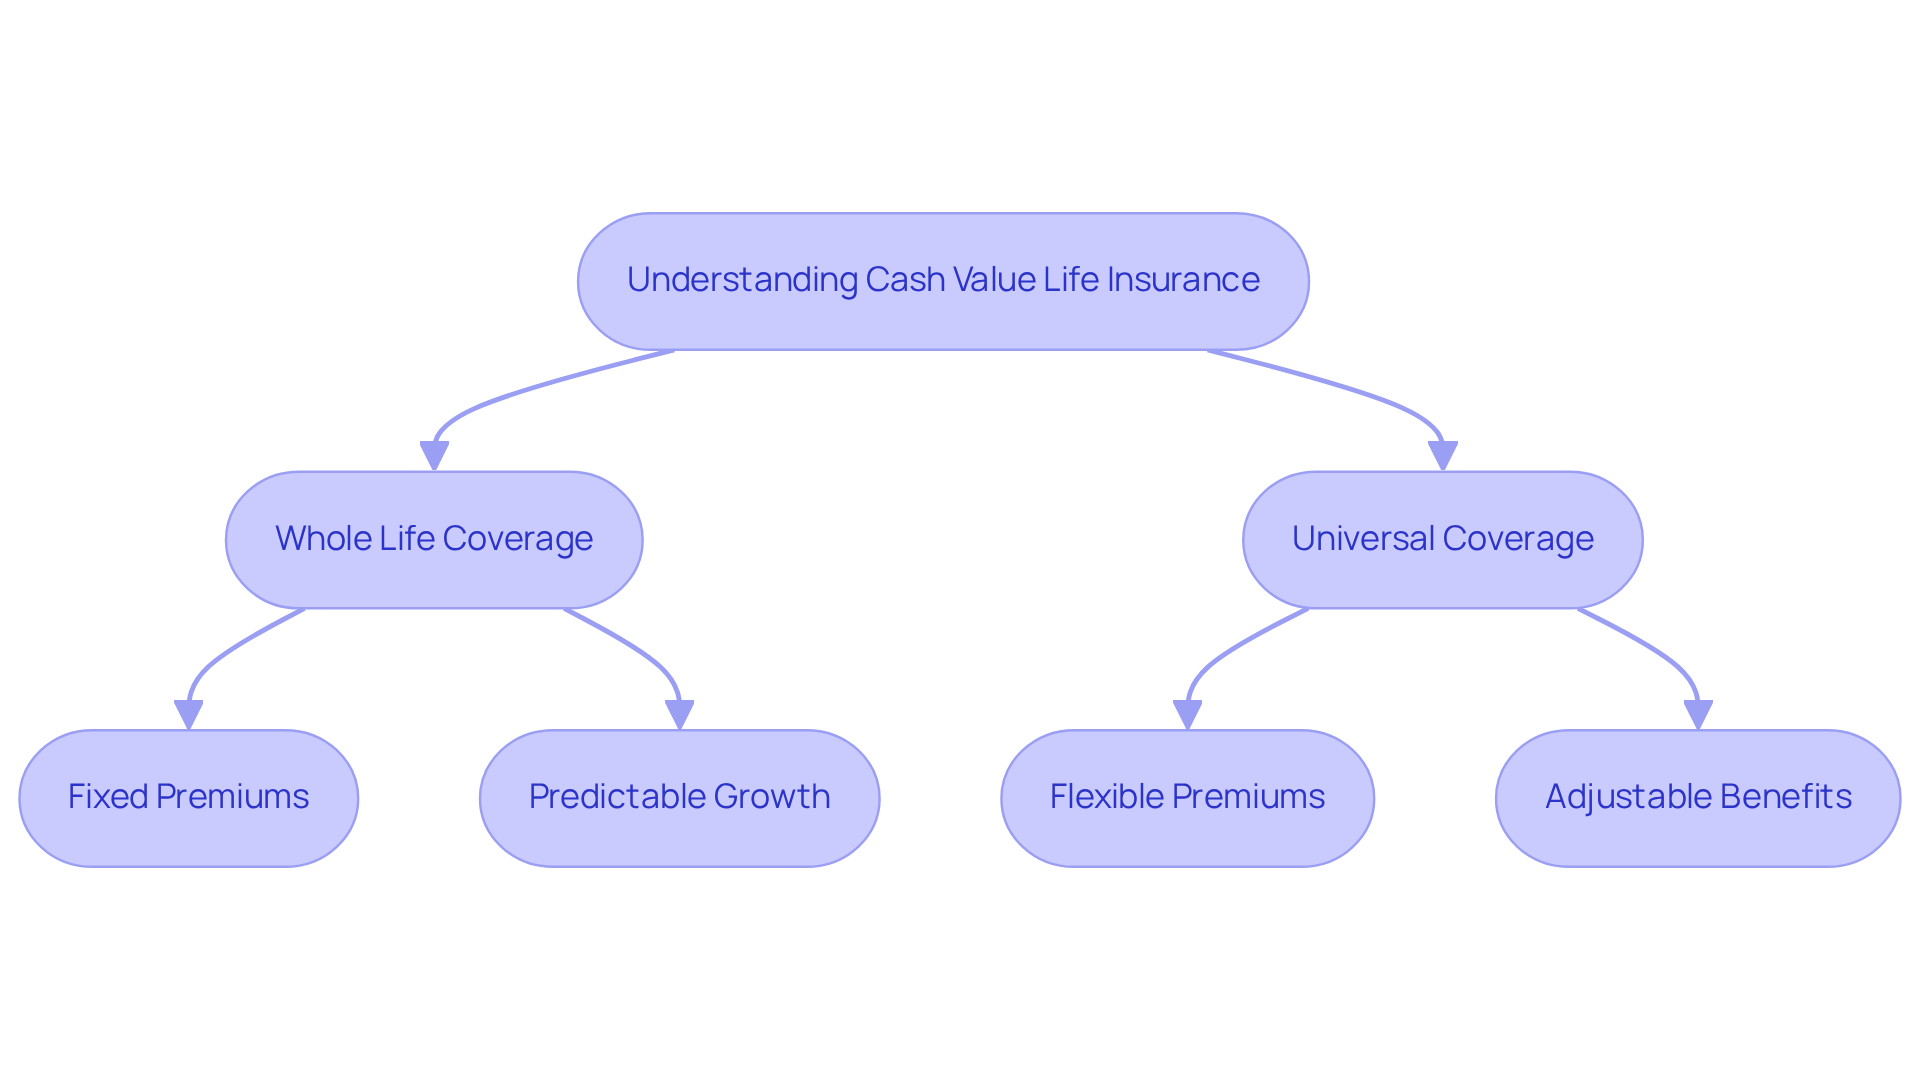
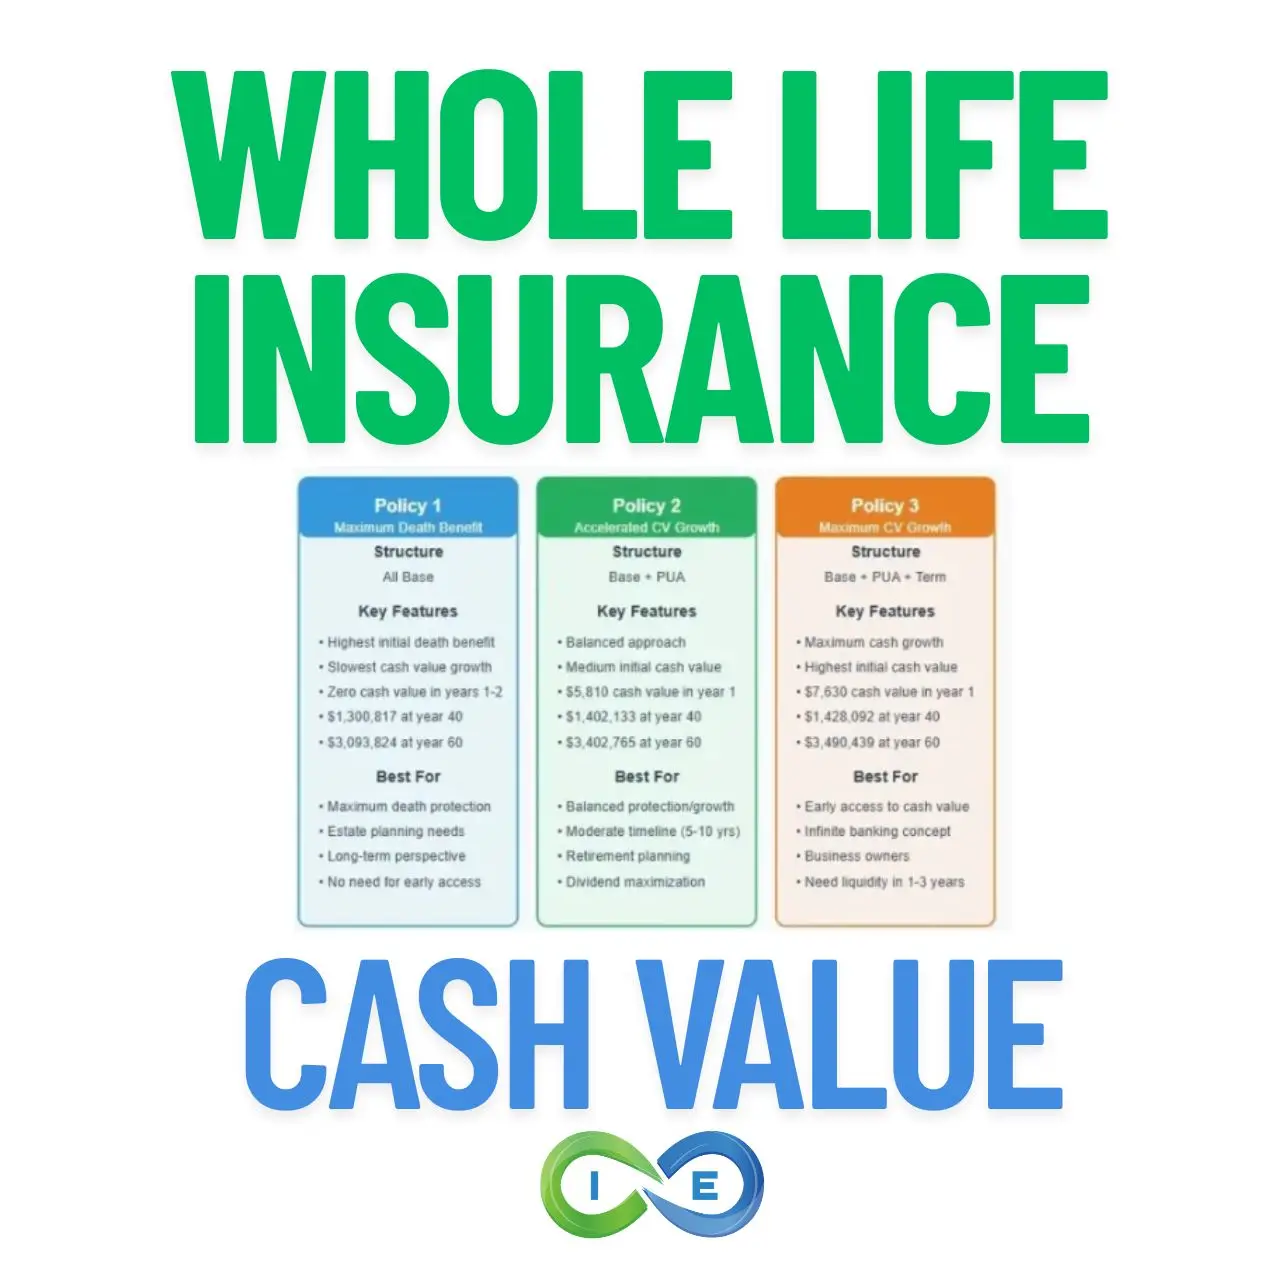
This is the flagship product of the NYL portfolio. It offers the highest level of guarantees. The cash value in a whole life policy grows at a guaranteed rate set by the company at the time of issuance. Furthermore, whole life policies are eligible for dividends. When these dividends are used to purchase Paid-Up Additions (PUAs), they increase both the death benefit and the cash value, creating a "snowball effect" of growth that is shielded from market volatility.
Custom Whole Life
A variation of the standard whole life product, Custom Whole Life allows policyholders to choose the duration of their premium payments (e.g., paying off the policy in 10, 15, or 20 years). This structure significantly alters the cash value landscape by front-loading the account. Because premiums are higher during the "pay-in" period, the cash value accumulates much faster than in a traditional whole life policy, making it a popular choice for those looking to use the policy as a supplemental retirement vehicle.
Universal Life (UL) and Variable Universal Life (VUL)
Universal Life policies offer more flexibility in premium payments and death benefits. The cash value growth is tied to current interest rates. Variable Universal Life (VUL), however, shifts the landscape into the equity markets. VUL policyholders can allocate their cash value across various sub-accounts (similar to mutual funds). While this offers the potential for much higher growth than whole life, it also introduces market risk; if the underlying investments perform poorly, the cash value can decrease, potentially requiring higher premium payments to keep the policy in force.

Mechanics of Cash Value Accumulation
The growth of cash value at New York Life is not a linear process. It is governed by several moving parts that interact over decades.
- Guaranteed Increase: Every whole life policy has a schedule of guaranteed cash value increases. This ensures that by the time the insured reaches age 100 or 121 (depending on the policy contract), the cash value will equal the original death benefit.
- The Dividend Scale: Each year, the Board of Directors at New York Life approves a dividend scale. This scale is influenced by the company's investment performance, mortality experience (death claims paid), and operational expenses. In 2026, the dividend scale remains a primary driver for policyholders seeking to outperform standard savings accounts or bonds.
- Policy Charges: It is critical to understand that the "gross" growth is offset by internal charges. These include the Cost of Insurance (which increases as the insured ages), premium taxes, and administrative fees. In the first 5 to 10 years of a New York Life policy, the surrender value (the amount you can actually take out) is often lower than the total premiums paid due to these front-loaded costs.
Accessing Your Cash Value: Methods and Consequences
One of the most attractive features of the New York Life landscape is the ability to access liquidity without necessarily surrendering the policy. However, each method of access has specific rules and potential downsides.
Policy Loans
New York Life allows policyholders to borrow against their cash value. Unlike a bank loan, there is no credit check, and there is no mandatory repayment schedule. The cash value itself acts as collateral. In 2026, New York Life typically offers both fixed and variable loan interest rates.
- The Impact: When you take a loan, the portion of the cash value used as collateral may earn a lower dividend rate or interest rate than the "unborrowed" cash value. Furthermore, if the insured dies with an outstanding loan, the balance is deducted from the death benefit paid to beneficiaries.
Partial Surrenders (Withdrawals)
Policyholders can also choose to withdraw a portion of their cash value. For many NYL products, withdrawals are treated on a FIFO (First-In, First-Out) basis for tax purposes. This means you can withdraw up to the "basis" (the total amount of premiums paid) without triggering an income tax liability.
- The Impact: Unlike a loan, a withdrawal permanently reduces the cash value and usually reduces the death benefit. If you withdraw more than your basis, the excess is taxed as ordinary income.
Surrender for Cash Value
If the policy is no longer needed, the owner can surrender the entire contract for its net cash value. This terminates the insurance coverage entirely.
- The Impact: This should be a last resort. If the cash value exceeds the total premiums paid, the gain is taxable. Additionally, the policyholder loses the death benefit protection that may be difficult or more expensive to replace later in life.
The Role of Dividends in 2026
As of 2026, New York Life continues to emphasize its long-term investment philosophy. The company’s general account is primarily invested in high-quality fixed-income securities, which provides the stability needed to support the dividend scale.
Policyholders have four primary options for how to receive their dividends:
- Cash: Receive a check annually (not recommended for growth).
- Premium Reduction: Apply the dividend toward the next year’s premium.
- Accumulate at Interest: Leave the money with NYL to earn a set interest rate (interest is taxable).
- Paid-Up Additions (PUAs): Use the dividend to "buy" more death benefit and cash value. This is generally considered the most efficient way to maximize the "landscape" of the policy, as PUAs have their own cash value and are eligible for future dividends, creating a compounding effect.
Comparative Overview: Cash Value Growth Models
The following table compares the typical characteristics of cash value across New York Life’s primary permanent products as they stand in 2026.
| Feature | Whole Life | Custom Whole Life | Universal Life | Variable Universal Life |
|---|---|---|---|---|
| Growth Engine | Guarantees + Dividends | Guarantees + Dividends | Current Interest Rates | Market Sub-accounts |
| Risk Level | Low | Low | Moderate | High |
| Premium Flexibility | None (Fixed) | High (Short-pay options) | High | High |
| Cash Access | Loans & Withdrawals | Loans & Withdrawals | Loans & Withdrawals | Loans & Withdrawals |
| Dividend Eligibility | Yes | Yes | No | No |
| Best For | Conservative growth | Accelerated funding | Flexibility | Long-term market upside |
Tax Implications and the MEC Rule
The tax-advantaged nature of the New York Life cash value landscape is one of its strongest selling points, but it is subject to federal regulations, specifically the Modified Endowment Contract (MEC) rules.
Under IRS Section 7702, there is a limit on how much money can be put into a life insurance policy relative to the death benefit within a certain timeframe (the "7-pay test"). If a policyholder overfunds their New York Life policy too quickly—common in some Custom Whole Life scenarios—the policy becomes a MEC.
- Consequences of a MEC: Once a policy is a MEC, it loses its FIFO tax status. Withdrawals and loans are taxed on a LIFO (Last-In, First-Out) basis, meaning the gains come out first and are taxed as ordinary income. Additionally, if the owner is under age 59½, they may face a 10% IRS penalty on the taxable portion of the withdrawal.
For non-MEC policies, the ability to take tax-free loans and tax-free withdrawals up to basis remains a cornerstone of the 2026 financial planning environment, particularly for those in high tax brackets.
Common Pitfalls and Strategic Considerations
Navigating the New York Life cash value landscape requires avoiding common mistakes that can erode the policy's value.
- Illustrations vs. Reality: When purchasing a policy, agents provide "illustrations" showing projected growth. It is vital to remember that the "non-guaranteed" columns are based on the current 2026 dividend scale. If interest rates or company performance change in 2028 or 2030, the actual cash value will differ from the original projection.
- Direct Recognition: New York Life utilizes "direct recognition" on some of its older products but generally offers "non-direct recognition" or specific loan regimes on modern products. Direct recognition means the company reduces the dividend on the portion of the cash value that has an outstanding loan. Understanding which version your policy uses is crucial for calculating the true cost of a loan.
- The "Corridor" Risk: In universal life products, if the cash value grows too quickly or the cost of insurance rises too sharply, the policy might require more premium than originally planned to prevent a lapse. This "premium "creep" can occur if interest rates remain low for extended periods.
FAQs
Can I lose money in a New York Life cash value account?
In a standard Whole Life or Custom Whole Life policy, you cannot lose your principal cash value or your guaranteed growth due to market fluctuations. However, in a Variable Universal Life (VUL) policy, your cash value is invested in sub-accounts tied to the stock and bond markets, meaning the value can decrease if those investments perform poorly. Furthermore, if you surrender any policy early (usually within the first 10 years), the surrender charges and initial costs may result in receiving less money than the total premiums paid.
How often are dividends credited to my New York Life policy?
Dividends are typically determined annually by the New York Life Board of Directors and are credited to participating policies on the policy anniversary date. While they have been paid every year for over 170 years, they are never legally guaranteed for the future.
What is the difference between cash value and surrender value?
The cash value is the total amount of equity built up within the policy. The surrender value is the amount the insurance company will actually pay you if you cancel the policy. In the early years of a policy, the surrender value is often lower than the cash value because of "surrender charges"—fees the company deducts to recoup the costs of issuing the policy. After a certain period (often 10 to 15 years), the surrender value usually equals the full cash value.
Can I use my cash value to pay my premiums?
Yes. At New York Life, once you have accumulated enough cash value or have sufficient dividends, you can use those funds to pay your premiums. This is often called "Automatic Premium Loan" or using "Dividends to Pay Premiums." In 2026, many policyholders use this strategy during retirement to maintain their coverage without out-of-pocket expenses, though it does slow the growth of the death benefit.
Does the cash value get paid to my beneficiaries in addition to the death benefit?
In a standard whole life policy, the answer is generally no. The insurance company keeps the cash value, and the beneficiaries receive the face amount (death benefit). However, if you have used your dividends to purchase Paid-Up Additions (PUAs), those additions increase the death benefit. Therefore, the "growth" of your policy is effectively passed on, even if the internal cash account itself is absorbed into the death benefit payout.
Practical Recommendation
When managing or entering the New York Life cash value landscape in 2026, the most effective strategy remains the long-term perspective. Permanent life insurance is a poor short-term investment due to high initial costs and surrender charges. However, as a 20- to 40-year asset class, it provides a unique combination of tax-advantaged growth, liquidity, and downside protection.
If your goal is maximum liquidity and safety, prioritize Whole Life with the Paid-Up Additions rider. If you are looking for a way to fund a policy quickly for retirement income, explore Custom Whole Life with a 10-year pay structure. Regardless of the path, ensure your policy is structured to avoid MEC status to preserve the tax-free access to your funds. Always request a "current in-force illustration" every two to three years to see how your actual cash value is performing compared to original expectations.
Image Gallery
Select an image to open it in a new tab.
Vivian Cho
Executive IT and Emerging Technologies Reporter
