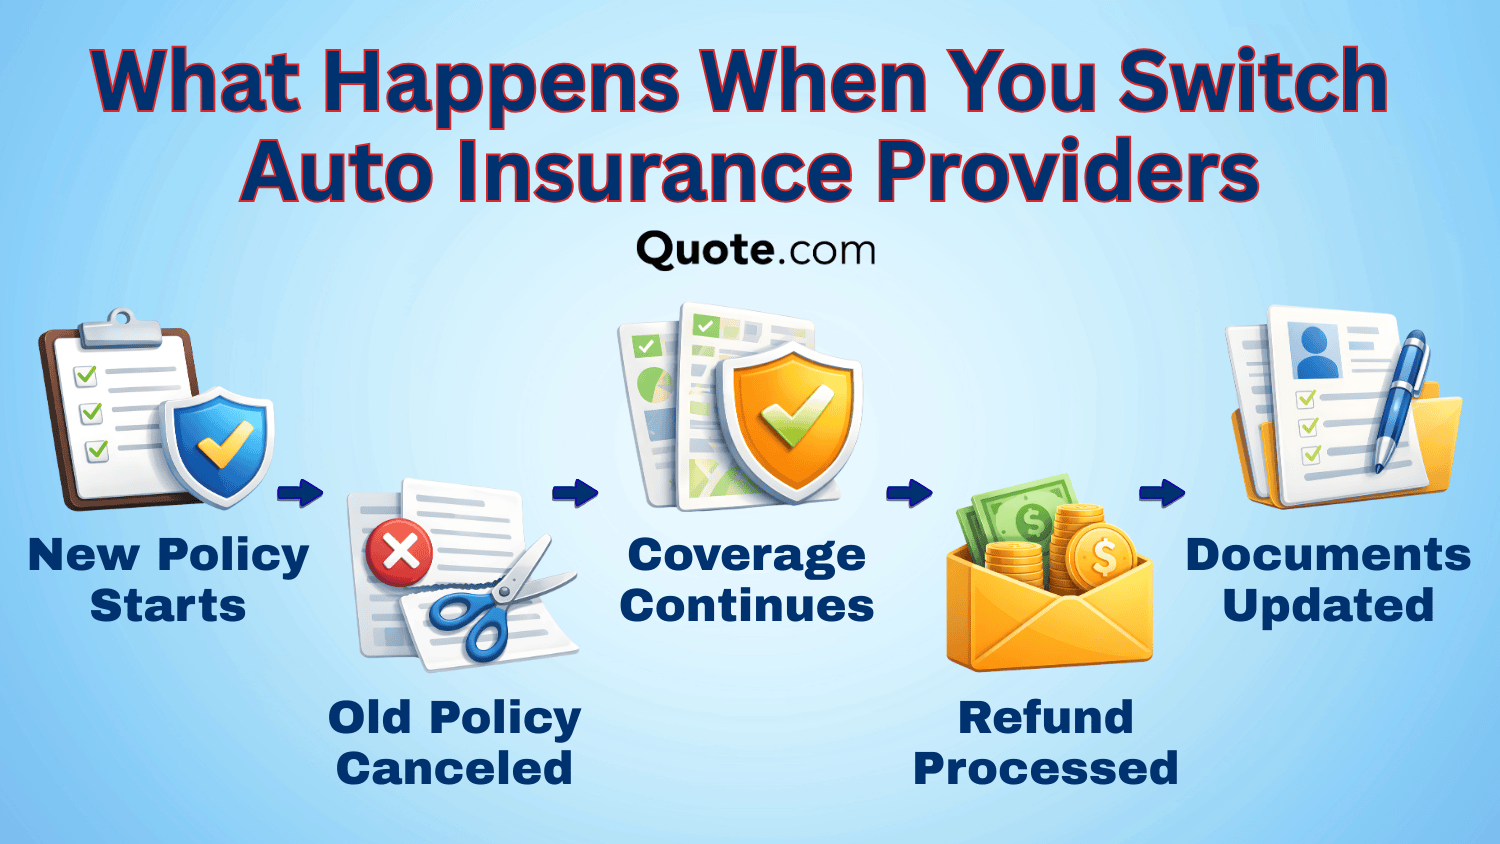
Yes, if you switch your auto insurance provider before your current policy term expires, you are generally entitled to a refund of the "unearned premium." This refund represents the portion of your premium that you paid in advance for coverage days that you will no longer use.
Navigating the transition between insurance carriers often raises questions about financial recovery, especially for drivers who pay their premiums in full or at the start of a monthly cycle. In 2026, the process of switching insurance is more streamlined than ever, but understanding the mechanics of insurance refunds remains essential to ensure you are not leaving money on the table. This guide explores the types of refunds available, the calculation methods insurers use, and the specific steps you must take to secure your funds.
Understanding the Concept of Unearned Premium
To understand why you get a refund, you must first understand how insurance companies account for your money. When you sign an insurance contract, you typically pay for coverage in advance. Whether you pay for six months upfront or pay a monthly installment on the first of the month, you are prepaying for protection during a future window of time.
The money you have paid for days that haven't happened yet is known as unearned premium. Legally and actuarially, the insurance company cannot "earn" that money until the day of coverage actually passes. If you cancel your policy on day 100 of a 182-day (six-month) policy, the insurer has only earned the premium for those first 100 days. The remaining 82 days of premium belong to you, minus any applicable administrative fees or "short-rate" penalties defined in your policy agreement.
In the current 2026 regulatory environment, most state insurance departments require carriers to return these funds within a specific timeframe, usually ranging from 15 to 30 days after the cancellation is finalized.
Pro-Rata vs. Short-Rate: How Your Refund is Calculated
Not all refunds are calculated equally. The amount of money you get back depends heavily on the cancellation method specified in your policy's fine print. There are two primary methods used by insurers: pro-rata and short-rate.
Pro-Rata Cancellation
Pro-rata is the most consumer-friendly calculation method. In a pro-rata cancellation, the insurer returns the full, exact portion of the unused premium without any penalties. For example, if you paid $1,200 for a 12-month policy and you cancel exactly halfway through (after six months), a pro-rata refund would be exactly $600.
Most major carriers in 2026 utilize pro-rata refunds, particularly if the consumer is switching because of a life change or a better rate. However, some states mandate pro-rata refunds only if the insurer cancels the policy, while allowing different rules if the consumer initiates the split.
Short-Rate Cancellation
A short-rate cancellation is less common but still exists in certain specialized or non-standard insurance markets. In this scenario, the insurer is permitted to deduct a percentage—often 10%—of the unearned premium to cover administrative costs and the "acquisition costs" of the policy.
Using the same example as above: if you had $600 in unearned premium, a short-rate penalty might cost you $60. Consequently, you would only receive a refund of $540. Short-rate penalties are more frequent with high-risk "non-standard" insurers or when a policy is canceled very early in its term (e.g., within the first 30 days).
The Step-by-Step Process of Switching and Getting Refunded
To ensure a smooth transition and a guaranteed refund, you must follow a specific sequence. Failing to do so can result in coverage gaps, which can lead to higher future premiums or legal penalties.
1. Secure Your New Policy First
Never cancel your old policy until your new policy is active and you have the digital or physical insurance ID cards in hand. Even a one-day gap in coverage can trigger a "lapse" on your record, which insurance algorithms in 2026 view as a significant risk factor. This lapse could negate the savings you gained by switching in the first place.
2. Determine the Effective Date
Coordinate the start date of your new policy with the end date of your old one. It is often safest to have them overlap by 24 hours. For example, if your new policy starts at 12:01 AM on June 15, set your old policy to cancel at 12:01 AM on June 15 or 16.
3. Formally Notify Your Current Insurer
Do not simply stop paying your premiums. If you stop payment on a monthly plan without formally canceling, the insurer may treat it as a "non-payment" cancellation. This is a negative mark on your insurance history and can lead to collections activity for the "earned" portion of the month you didn't pay for.
Call your agent or use the company’s mobile app to request a formal cancellation. You may be asked to provide your new policy number or a signed "Lost Policy Release" (LPR) form, which confirms you are intentionally ending the contract.
4. Confirm the Refund Method and Timeline
Ask the representative how the refund will be issued. In 2026, most refunds are processed back to the original payment method. If you paid via credit card or EFT (Electronic Funds Transfer), the money should appear there. If you paid by check or if the card on file has expired, the insurer will mail a physical check to your address on record. Verify that your mailing address is up to date before hanging up.
| Refund Type | How It's Calculated | Potential Fees | Common Usage |
|---|---|---|---|
| Pro-Rata | (Total Premium / Days in Term) × Days Remaining | None | Standard carriers, mid-term switches |
| Short-Rate | (Unearned Premium) - (Administrative Penalty) | 10% of remaining balance | Non-standard/High-risk carriers |
| Flat Cancellation | Full Refund of all premiums paid | None | Canceled before effective date |
| Minimum Earned Premium | Insurer keeps a fixed minimum amount | Varies by policy | Specialized or short-term policies |
Factors That Influence Your Refund Amount
Several variables can change the final number you see on your refund check. It is rarely as simple as dividing your total premium by the number of days.
Paid-in-Full Discounts
Many drivers pay for six or twelve months upfront to receive a "Paid-in-Full" discount, which can be as high as 5% to 10%. If you cancel early, some insurers will "charge back" that discount. They may recalculate your earned premium based on the standard, non-discounted rate, which slightly reduces the amount of your refund.
Bundle Adjustments
If your auto insurance was bundled with homeowners, renters, or life insurance, switching your auto policy will likely trigger a price increase for the remaining policies. The "multi-policy discount" will be removed. While you will still get a refund for the auto policy, you should be prepared for a higher premium bill on your home or renters insurance shortly after.
Policy Fees and Taxes
Most policies include non-refundable fees, such as an "installment fee" for monthly payments or state-mandated fire and safety assessments. These fees are generally not included in the refund calculation. Only the core "base premium" is typically refundable.
Endorsements and Recent Claims
If you recently added a new vehicle or driver to your policy before switching, the calculation becomes more complex. Furthermore, having an open claim does not prevent you from switching or getting a refund for unearned premiums, but the "earned" portion of your premium may be adjusted if the claim changed your risk rating mid-term.
How Timing Affects Your Refund
The time of the month or the time of the policy cycle when you cancel can drastically change your immediate cash flow.
- Canceling at the Start of the Cycle: If you pay monthly and cancel two days after your monthly payment was drafted, you are entitled to roughly 28 days of that payment back.
- Canceling at the End of the Cycle: If you cancel two days before your next payment is due, your refund will be negligible—perhaps only a few dollars.
- Canceling After a Renewal Notice: If you have already received your renewal notice but the new term hasn't started yet, you can usually cancel for a full refund of any renewal down payments you made. This is often referred to as a "flat cancellation" if the new term hasn't officially begun.
Common Pitfalls When Seeking a Refund
Even with clear regulations, consumers often encounter hurdles. Being aware of these can prevent delays.
1. Verification of New Insurance: Some states, like New York, have very strict "continuous coverage" laws. Your old insurer may refuse to process your cancellation (and thus your refund) until they receive electronic proof that you have secured insurance elsewhere. This is to prevent you from driving uninsured and to notify the DMV correctly.
2. Automatic Withdrawals: One of the most common issues is the "ghost payment." If you cancel your policy on the same day your automatic payment is scheduled, the bank may still process the draft. You will eventually get this money back as part of your refund, but it can create a temporary cash flow strain. It is best to cancel at least 3-5 business days before an automated draft is scheduled.
3. Address Mismatches: Many refunds are delayed because the driver moved and forgot to update their address with the old insurance company. If the refund is sent via physical check, it may be sent to your old residence. Always confirm your current address during the cancellation call.
Frequently Asked Questions
Can an insurance company refuse to give me a refund?
Generally, no. As long as there is unearned premium on the account, the insurer is legally obligated to return it. The only exceptions are "fully earned" policies, which are rare in personal auto insurance but common in specific commercial or high-risk niches. If you have a standard policy, you are entitled to your money back.
How long does it take to receive an auto insurance refund?
In 2026, electronic refunds are typically processed within 3 to 7 business days. If the company issues a paper check, it may take 2 to 4 weeks depending on the mail service and the insurer's internal processing cycle. Many states have laws requiring insurance refunds to be issued within 30 days.
Do I get a refund if I cancel my policy after a total loss accident?
Yes. If your car is totaled and the claim is settled, you no longer have an insurable interest in that vehicle. You can cancel the policy as of the date of the accident or the date the vehicle was salvaged. You will receive a refund for the premium paid from that date forward.
Should I wait until my policy expires to switch?
You do not have to wait, but it is often the "cleanest" way to switch. If you switch at the expiration date, there is no unearned premium to worry about, no potential for short-rate penalties, and no need to track down a refund check. However, if you find a significantly better rate mid-term, the savings usually outweigh the minor inconvenience of waiting for a refund.
What happens if I have an SR-22 and I switch?
If you have an SR-22 filing, you must be extremely careful. You must ensure the new insurer files the SR-22 with the state before the old insurer notifies the state that your policy has been canceled. While you are still entitled to a refund for the unearned premium on an SR-22 policy, any gap in filing can lead to a license suspension.
Practical Recommendation for Drivers
If you are planning to switch, the most efficient path is to utilize your new agent or company's "concierge" services. Many modern insurers in 2026 offer tools that can electronically notify your previous carrier and initiate the cancellation for you.
Before you finalize the switch, perform a quick "Refund Audit":
- Check your last payment date: Is it within the last week?
- Ask about the penalty: Specifically ask the agent, "Will this be a pro-rata or a short-rate cancellation?"
- Confirm the refund destination: Ensure it is going back to your preferred bank account or the correct address.
By proactively managing these details, you can ensure that the transition to a more affordable or better-suited insurance policy is financially beneficial from day one.
Image Gallery
Select an image to open it in a new tab.

Simon Caldwell
Enterprise Technology and Systems Editor
