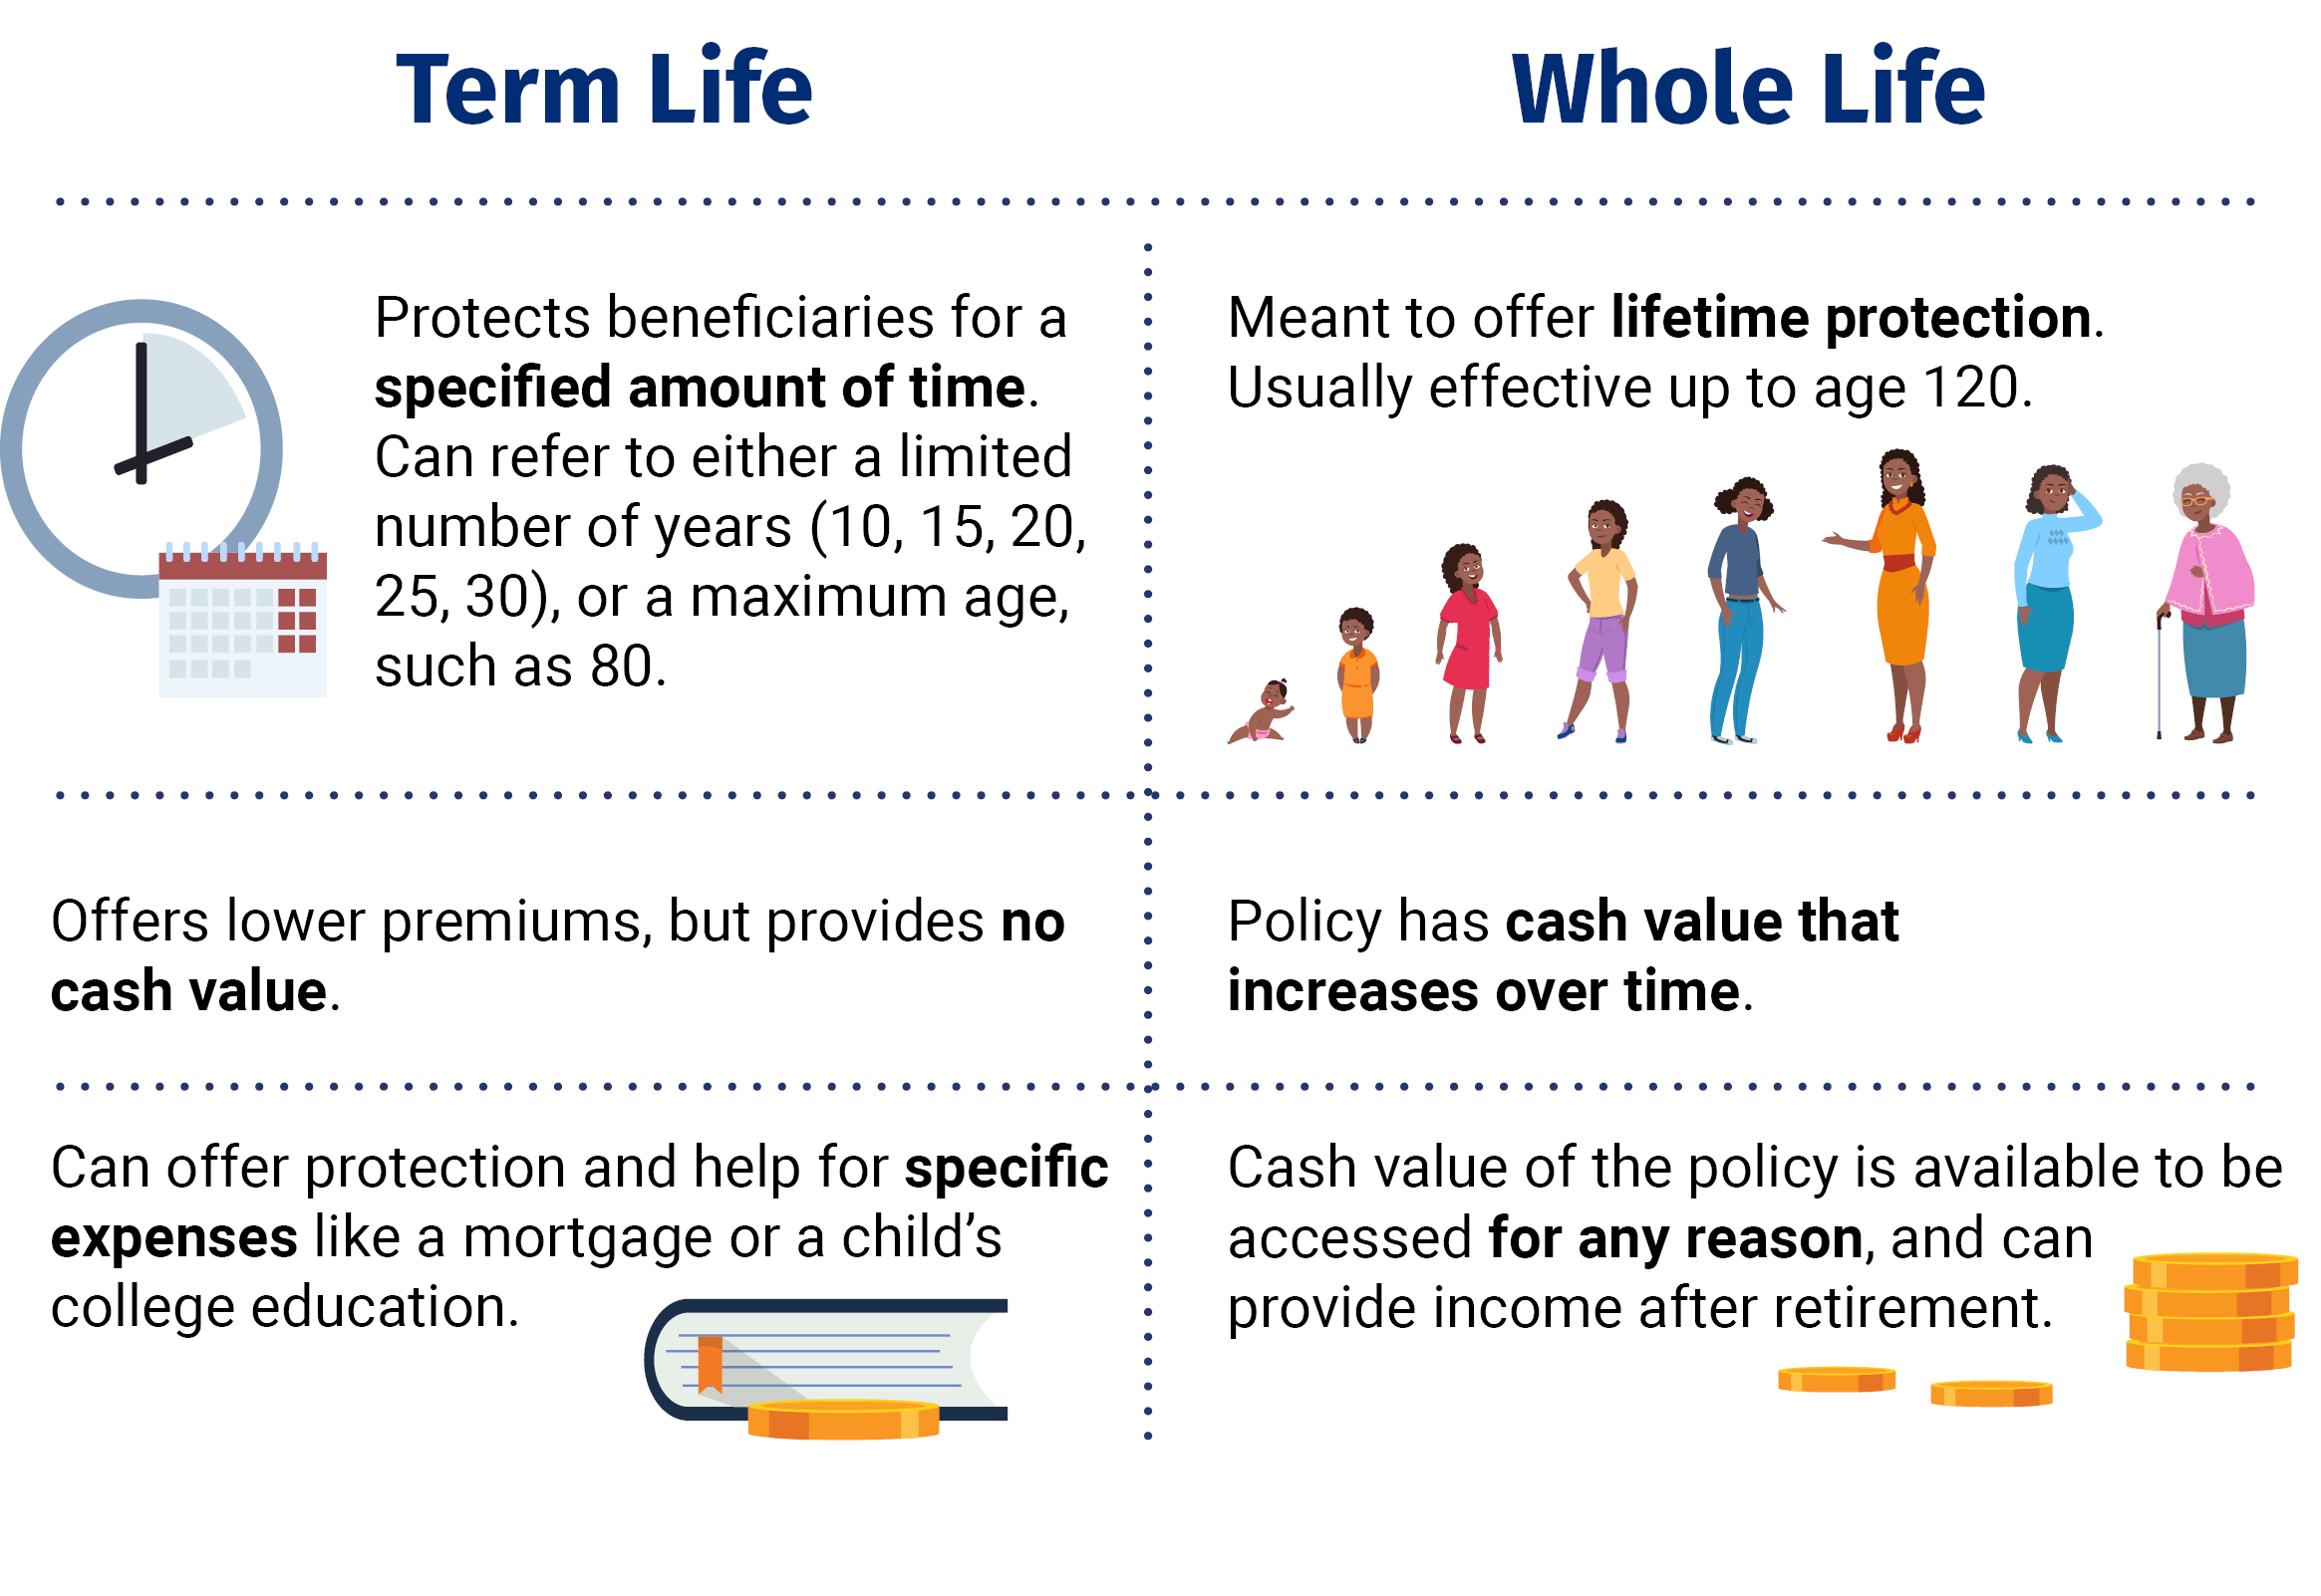
To convert a whole life policy to a tax-free life insurance vehicle, you must execute a Section 1035 exchange. This IRS-sanctioned maneuver allows you to transfer the accumulated cash value from your existing policy into a new, more efficient contract without triggering a taxable event on the gains, preserving its tax-advantaged status.
Understanding the Mechanics of the 1035 Exchange
In the landscape of 2026 financial planning, the "conversion" of a life insurance policy is technically a tax-free exchange under Section 1035 of the Internal Revenue Code. This provision is vital for policyholders who find themselves trapped in older whole life products that may have high internal costs or lower-than-market dividend yields.
A 1035 exchange is comparable to a 1031 exchange in real estate or a direct rollover in the world of 401(k)s. It allows for the replacement of an existing life insurance policy, endowment, or annuity with a "like-kind" product. When you perform this exchange, the cost basis—the total amount of premiums you have paid into the policy—moves over to the new policy. This ensures that any growth (the "gain") above your basis is not recognized as income for tax purposes at the time of the transfer.
The primary goal for most individuals seeking this conversion is to move "frozen" equity in a traditional whole life policy into a more modern structure, such as an Indexed Universal Life (IUL) or a Variable Universal Life (VUL) policy. These modern vehicles often provide better "tax-free" access to cash value through structured policy loans and withdrawals, often referred to as Life Insurance Retirement Plans (LIRPs).
Why Convert a Whole Life Policy Now?
Many whole life policies issued in the previous decades were designed for a different economic environment. By 2026, many policyholders are discovering that their legacy whole life contracts are "cash heavy" but "benefit light." There are several compelling reasons to initiate a conversion:
1. Enhanced "Living Benefits"
Older whole life policies primarily focused on the death benefit. Modern policies often include "living benefit" riders, such as chronic or terminal illness accelerators. Converting to a new policy allows you to access your death benefit while you are still alive if you require long-term care or face a critical health event. This effectively turns a passive asset into a functional component of a retirement healthcare strategy.
2. Improved Growth Potential
Traditional whole life policies rely on the insurer's general account performance and dividend declarations. If you are seeking higher growth to combat inflation in 2026, moving that cash value into an Indexed Universal Life (IUL) policy can provide exposure to market indices (like the S&P 500) while maintaining a "floor" against market losses. This shift can significantly increase the tax-free income potential of the policy.
3. Efficiency and Cost Reduction
Legacy policies often carry high administrative fees and mortality charges based on older actuarial tables. Newer policies utilize the most recent mortality data, which, given increased life expectancies, often results in lower internal costs for the same amount of coverage. By converting, you may be able to secure a larger death benefit for the same premium, or maintain the same death benefit while reducing your out-of-pocket costs.
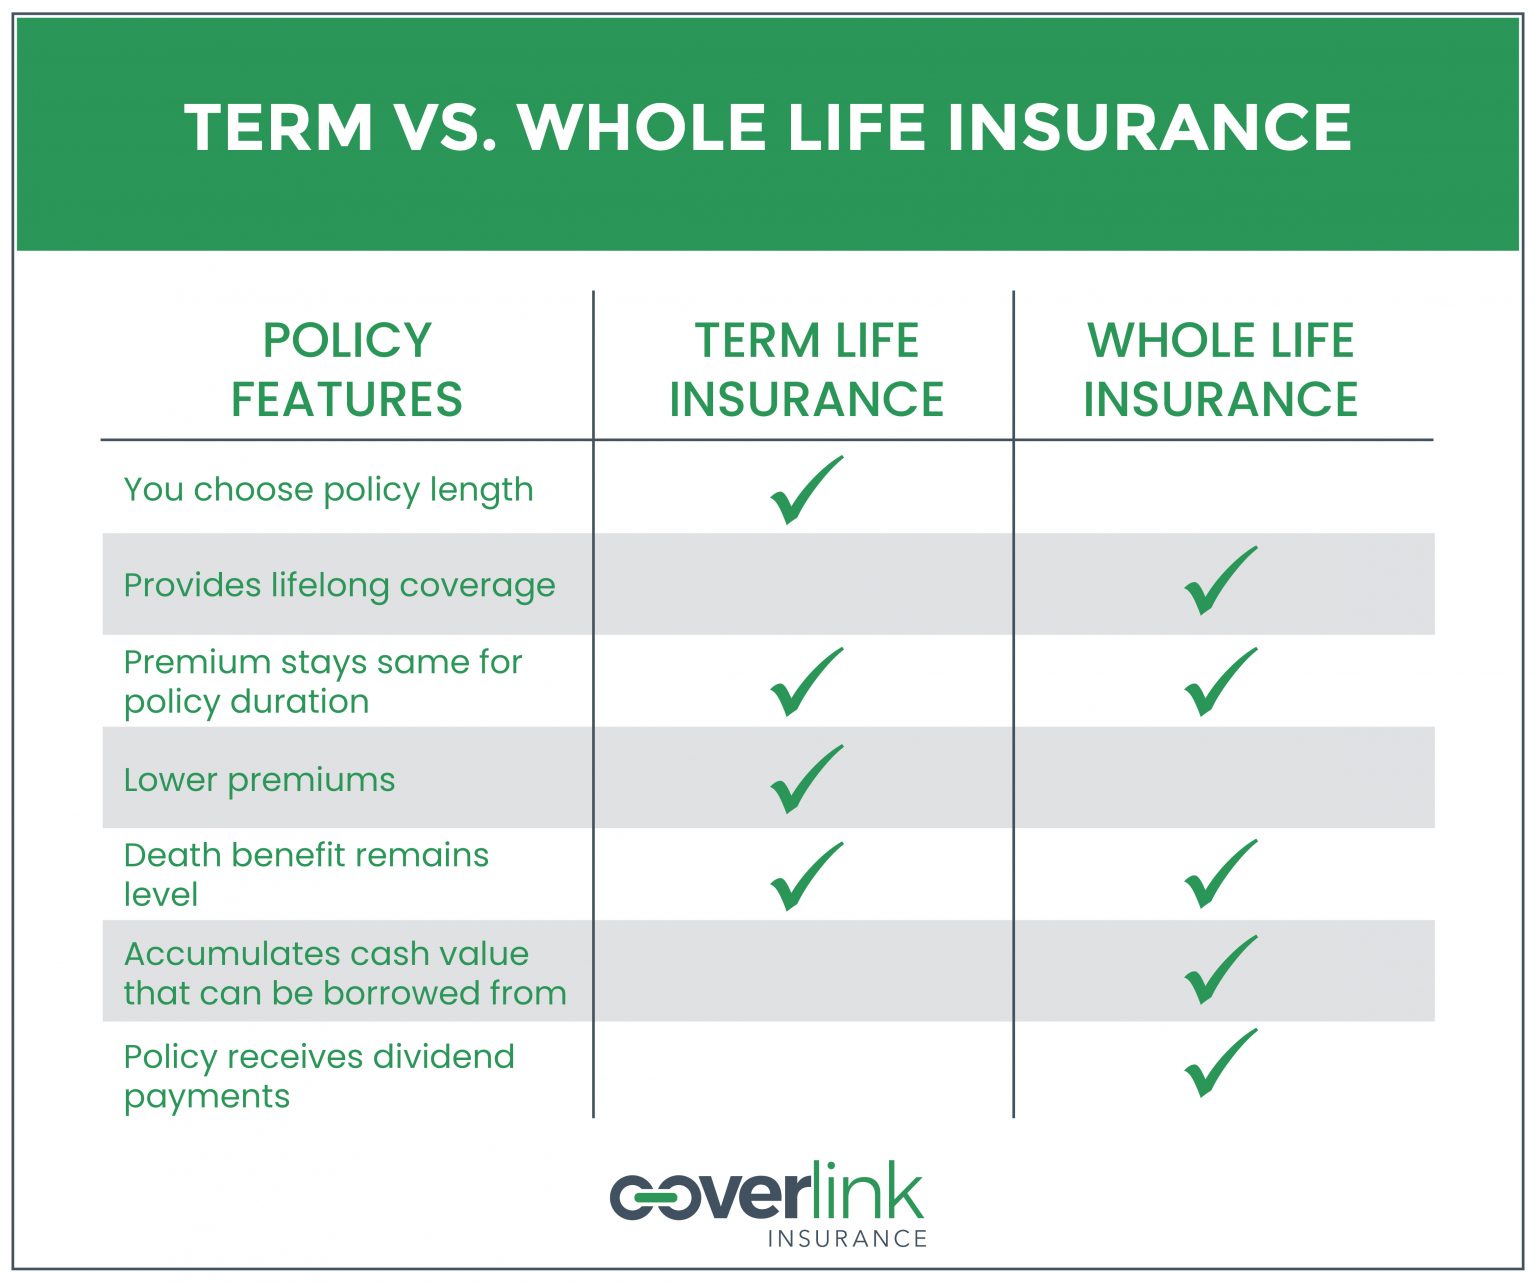
The Tax-Free Nature of Life Insurance Explained
When people speak of "tax-free life insurance," they are generally referring to three distinct tax advantages provided by the IRS under Section 101(a) and Section 7702.
- Income Tax-Free Death Benefit: Generally, the proceeds paid to beneficiaries upon the death of the insured are not subject to federal income tax.
- Tax-Deferred Growth: The cash value inside a life insurance policy grows without being subject to annual capital gains or income taxes.
- Tax-Free Access to Cash: Through a combination of withdrawals up to the policy's basis (FIFO—First In, First Out) and policy loans against the remaining gain, policyholders can access their capital without triggering an income tax bill.
However, to maintain these "tax-free" qualities, the policy must avoid becoming a Modified Endowment Contract (MEC). A MEC occurs when a policy is funded too quickly, exceeding the "7-pay test" limits set by the IRS. During a conversion, a skilled advisor must ensure the 1035 exchange is structured so that the massive influx of cash from the old policy does not cause the new policy to lose its favorable tax status.
Step-by-Step Guide to the Conversion Process
Converting a policy is a formal procedure that requires coordination between the old insurer (the "surrendering" company) and the new insurer (the "receiving" company).
Step 1: Perform a Policy Audit
Request an "In-Force Illustration" from your current provider. This document shows the current cash value, the surrender value (cash value minus penalties), the cost basis, and any outstanding loans. You cannot accurately convert a policy without knowing exactly how much "gain" exists in the contract.
Step 2: Determine Your New Objective
Are you looking for tax-free retirement income, or are you more concerned with long-term care protection? If you want income, an IUL might be the target. If you want a guaranteed death benefit for estate taxes, a Guaranteed Universal Life (GUL) or a more modern Whole Life policy might be appropriate.
Step 3: Apply for the New Policy
Before you cancel your old policy, you must be approved for the new one. This typically involves medical underwriting. In 2026, many carriers offer "accelerated underwriting," which uses data from your medical records and prescription history to provide an approval within days without a physical exam.
Step 4: Initiate the 1035 Exchange Paperwork
Once approved, you will sign a 1035 Exchange Form provided by the new insurance company. This form authorizes the new company to request the funds directly from the old company. Important: You must never take a check for the cash value yourself. If the funds touch your personal bank account, the IRS considers it a surrender, and you will be taxed on all gains immediately.
Step 5: Transfer and Allocation
The old company sends the funds directly to the new company. This process can take anywhere from three to six weeks. Once the funds arrive, they are allocated into the new policy's accounts (fixed or indexed) according to your instructions.
Comparing Traditional Whole Life vs. Modern Tax-Advantaged Policies
| Feature | Traditional Whole Life (Legacy) | Modern Indexed Universal Life (IUL) | Modern Whole Life (High-Early Cash Value) |
|---|---|---|---|
| Growth Mechanism | Declared Dividends | Market Index Performance (with Caps/Floors) | Dividends + PUA Riders |
| Flexibility | Rigid Premiums | Flexible Premiums | Semi-Flexible |
| Access to Cash | Policy Loans (Fixed Rates) | Variable/Participating Loans | Participating Loans |
| Living Benefits | Usually None or Limited | Comprehensive LTC/Chronic Illness | LTC/Chronic Riders (Modern) |
| Death Benefit | Fixed/Slow Growth | Potential for High Growth | Compound Growth via Dividends |
Potential Pitfalls: MECs, Loans, and Surrender Charges
While the prospect of tax-free conversion is appealing, there are several technical traps that can negate the benefits of the move.
The Modified Endowment Contract (MEC) Trap
As mentioned, if you move a large sum of cash into a new policy with a death benefit that is too small, the policy becomes a MEC. In a MEC, any money you take out is taxed as "gain first" (LIFO), and if you are under age 59 ½, you may face a 10% penalty from the IRS. A specialized agent must "right-size" the death benefit of the new policy to accommodate the incoming 1035 funds while keeping the policy compliant with Section 7702.
Outstanding Policy Loans
If your current whole life policy has an outstanding loan, the conversion becomes significantly more complex. If the loan is "forgiven" or extinguished during the exchange, the IRS may treat the amount of the forgiven loan as a taxable distribution. To avoid this, you must either pay off the loan before the exchange or perform a "loan carryover" 1035 exchange, which only a limited number of insurance carriers are equipped to handle.
New Surrender Charge Periods
Almost all new permanent life insurance policies come with a new surrender charge period, often lasting 10 to 15 years. This means that while your money is working for you tax-free, you will face penalties if you try to cancel the policy and walk away with the cash in the early years. You must view the conversion as a long-term commitment.
The Role of Financial Professionals in 2026
In 2026, the regulatory environment for life insurance has become increasingly focused on "best interest" standards. Converting a whole life policy is not a DIY project. It requires a sophisticated understanding of IRS codes and the internal pricing models of different carriers.
An experienced advisor will use specialized software to run "comparison illustrations." These models project the internal rate of return (IRR) on both the old policy and the proposed new policy. If the new policy doesn't clearly outperform the old one after accounting for new fees and surrender charges, the conversion may not be in your best interest.
Furthermore, tax laws regarding the Internal Revenue Code Section 7702 are subject to change. Professionals stay abreast of these changes to ensure your "tax-free" plan remains compliant with the latest federal mandates.
Frequently Asked Questions
Can I convert my whole life policy to a tax-free annuity?
Yes, a 1035 exchange allows you to move funds from a life insurance policy to an annuity tax-free. However, the reverse is not allowed. You cannot move funds from an annuity to a life insurance policy without paying taxes on the gains. Moving to an annuity may provide tax-deferred growth, but the death benefit will generally not be income tax-free in the same way a life insurance death benefit is.
Will I lose my original cost basis in the exchange?
No. One of the primary advantages of the 1035 exchange is that your original cost basis (the total of all premiums paid into the original policy) carries over to the new policy. This is critical because it allows you to withdraw that amount from the new policy tax-free at a later date.
What happens if the company holding my whole life policy refuses the transfer?
Legally, an insurance company cannot refuse a 1035 exchange request, as it is a policyholder right under the tax code. However, they may delay the process with administrative hurdles. Having a dedicated representative from the new insurance company to follow up on the transfer is usually the best way to resolve these delays.
Do I have to undergo a medical exam to convert?
In most cases, yes. Because you are moving to a new life insurance contract, the new company is taking on a new risk. However, by 2026, many carriers offer "fluidless" underwriting for healthy individuals up to certain coverage limits (often up to $2 million or $3 million), meaning they will use digital records rather than blood and urine samples.
Is it possible to partially convert a policy?
Yes, the IRS allows for "partial 1035 exchanges." You can move a portion of the cash value from your whole life policy into a new vehicle while leaving the original policy in force. This is a complex maneuver that requires precise calculation of the basis and gain for both resulting "pieces" of the original contract.
Final Recommendation
Converting a whole life policy to a more efficient "tax-free" life insurance structure is a powerful way to revitalize a stagnant financial asset. By utilizing a 1035 exchange, you protect your hard-earned gains from the IRS while gaining access to modern features like market-linked growth and long-term care riders.
Your next step should be to request an In-Force Illustration from your current carrier and consult with a tax professional or an independent insurance advisor who specializes in high-cash-value life insurance. They can help you determine if the long-term tax savings and increased benefits outweigh the costs of making the switch.
Image Gallery
Select an image to open it in a new tab.


Vivian Cho
Executive IT and Emerging Technologies Reporter
