Why Electric Auto Insurance Quotes Are Often Cheaper Than You Think
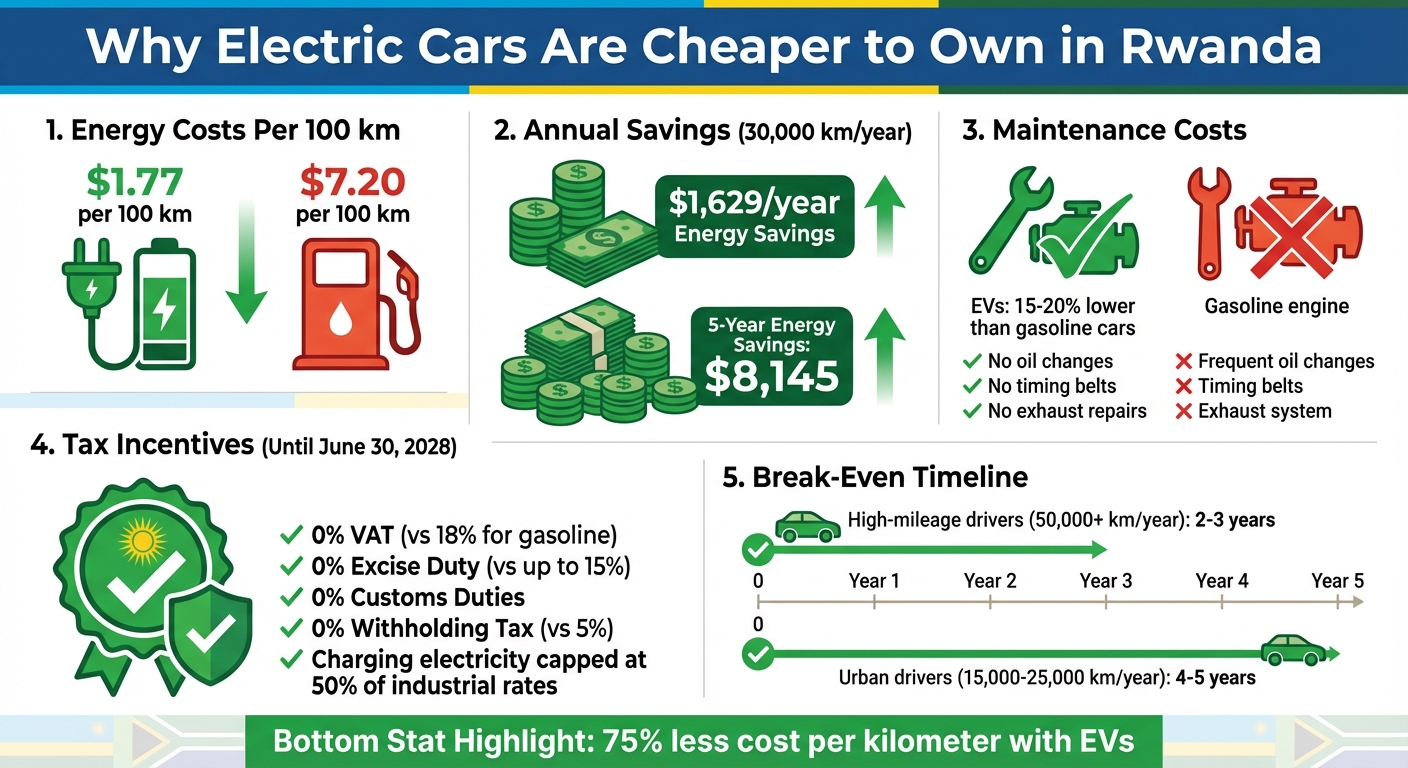
Electric vehicle ownership often comes with a surprising sticker shock when shoppers first look at monthly protection costs, but electric auto insurance quotes frequently turn out to be much more affordable than initial industry rumors suggest. While insuring a battery electric vehicle historically carried a steep premium due to scarce repair infrastructure and specialized components, evolving underwriting models, shifting safety data, and targeted discounts are closing the gap between gas-powered cars and electric alternatives.
The assumption that electric vehicle (EV) insurance is prohibitively expensive stems largely from early claims data. In the nascent stages of mass-market EV adoption, insurers faced high costs for minor collisions because battery packs required complete replacement or specialized handling, and certified repair technicians were few and far between. However, as manufacturers scale production, expand certified repair networks, and integrate structural safety advancements, insurers are adjusting their risk assessments. Understanding how providers calculate these rates, what specific discounts apply, and how to shop effectively can reveal quotes that align closely with, or even beat, traditional vehicle coverage.
Deconstructing EV Insurance: Why Early Quotes Felt So High
When electric vehicles first gained widespread popularity, property and casualty insurers treated them as unpredictable, high-risk assets. Actuaries lacked long-term actuarial tables for battery longevity, collision outcomes, and autonomous driver-assistance system repair costs. Consequently, initial quotes carried a substantial safety buffer to account for unforeseen expenses.
Furthermore, early EV models were predominantly luxury vehicles. Insuring a high-end luxury sedan or crossover naturally incurs higher costs than insuring a standard compact car, regardless of whether the powertrain relies on gasoline or electricity. This created a statistical distortion where vehicle class and price point were conflated with the powertrain itself. As mainstream automakers introduce affordable electric hatchbacks, compact crossovers, and family sedans, the baseline cost of vehicles entering the insurance pool has normalized.
The Role of Specialized Repair Networks and Parts
A major driver of historical EV insurance quotes was the complexity of collision repair. Traditional body shops lacked the equipment, high-voltage safety gear, and specialized training required to handle damaged electric vehicles safely. A fender bender that might cost a few thousand dollars to repair on an internal combustion engine (ICE) vehicle could result in an expensive total loss or lengthy specialty-shop downtime for an EV.
However, manufacturer-certified collision repair networks have expanded significantly. Major automakers have invested heavily in training independent and dealership-affiliated shops, reducing labor bottlenecks. Additionally, improvements in battery pack design now allow for modular repairs in many modern EVs, meaning technicians can replace individual cell modules rather than the entire battery assembly, drastically reducing claim payouts for minor rear or side impacts.
Safety Ratings and Driver Demographics: The Hidden Advantages
Insurance pricing relies heavily on statistical risk modeling, and modern electric vehicles possess distinct advantages in safety engineering and driver demographics that often lower quotes behind the scenes.
Advanced Safety Features and Collision Avoidance
Electric vehicles are inherently heavy due to their massive battery packs, but this weight distribution, combined with a low center of gravity, significantly reduces the likelihood of rollover accidents. Moreover, virtually all modern EVs come standard with advanced driver-assistance systems (ADAS), such as automatic emergency braking, lane-keeping assist, and blind-spot monitoring.
Insurers reward these technologies. Vehicles equipped with robust, factory-installed active safety suites experience fewer at-fault collisions, translating directly to lower liability and collision premiums. While repairing these intricate sensors and cameras after an accident can be costly, the statistical reduction in accident frequency often outweighs the severity factor in actuarial tables.
The Demographic Factor
Actuarial science heavily weighs the profile of the primary driver. Statistically, early and current adopters of electric vehicles skew toward demographic groups with lower historical risk profiles, such as homeowners, individuals with higher credit scores, and mature, experienced drivers who commute predictable distances. Insurers factor this aggregate risk pool into their base rates. As a demographic profile associated with lower claims frequency, EV owners benefit from favorable group-level pricing adjustments.
Comparing Insurance Costs: Gas vs. Electric Vehicles
To understand how electric auto insurance quotes compare in practice, it is helpful to look at how different vehicle categories stack up against one another. While luxury EVs still command high premiums due to replacement costs, mainstream models often match or underprice comparable internal combustion vehicles.
| Vehicle Type / Category | Average Repair Complexity | Standard Safety Suite Availability | Typical Premium Trend Compared to ICE |
|---|---|---|---|
| Mainstream Compact EVs | Moderate | High (Standard) | Comparable or slightly lower |
| Luxury Performance EVs | High | High (Standard) | Moderately higher due to replacement value |
| Mid-Size Electric SUVs | Moderate to High | High (Standard) | Comparable |
| Standard Gas Sedans | Low to Moderate | Variable (Often Optional) | Baseline reference standard |
As shown in the comparison, vehicles that feature comprehensive, standard safety suites often offset the higher cost of parts through a lower frequency of claims. When shopping for quotes, looking beyond the powertrain to the vehicle's safety rating and replacement parts availability provides a clearer picture of expected costs.
Unlocking Hidden Discounts and Incentives for Electric Vehicles
Many drivers miss out on lower quotes because they fail to ask about green vehicle incentives and specialized carrier discounts. Insurance companies frequently update their discount structures to capture the growing EV market share.
Green Vehicle and Alternative Fuel Discounts
Numerous national and regional insurance providers offer dedicated green vehicle discounts. These programs typically shave a percentage—often between 5% and 10%—off comprehensive and collision coverage for drivers of hybrid, plug-in hybrid, and fully electric vehicles. Insurers implement these discounts to attract environmentally conscious drivers who statistically exhibit lower-risk driving behaviors.
Telematics and Usage-Based Insurance
Many modern EV owners drive fewer annual miles than traditional commuters, especially if they work remotely or utilize public transit for city travel. Telematics programs—which monitor driving habits and mileage via a mobile app or plugged-in device—allow low-mileage drivers to capitalize on their actual usage. Because many EVs are second household vehicles or driven on shorter local routes, usage-based insurance often yields significantly lower quotes than traditional flat-rate policies.
Common Mistakes That Inflate EV Quotes
When gathering electric auto insurance quotes, drivers frequently make avoidable errors that drive up their projected premiums. Navigating the quoting process effectively requires avoiding these common pitfalls:
- Comparing Against the Wrong Baseline: Comparing a luxury electric SUV quote directly to an economy gas sedan skews expectations. Ensure you are comparing vehicles of similar size, MSRP, and class.
- Failing to Update Vehicle Safety Features: Some online quote generators do not automatically apply every advanced safety discount available on specific EV trims. Verify that all standard crash-mitigation systems are explicitly listed in the profile.
- Overlooking Specialized Coverage Options: While bundling home charging station equipment under homeowners insurance is common, some policies require specific endorsements to cover portable EV charging cables and wall-mounted Level 2 chargers against theft or power surge damage.
- Limiting the Carrier Search: Specialized insurers or traditional carriers with aggressive EV acquisition strategies often provide much better rates than your current provider, making cross-shopping essential.
Frequently Asked Questions
Are electric cars more expensive to insure across all categories?
No. While luxury and high-performance electric vehicles often carry higher insurance premiums due to their elevated replacement costs and expensive specialty components, mainstream electric hatchbacks and mid-size crossovers frequently feature insurance quotes comparable to or even lower than their gas-powered equivalents.
Do insurance companies charge extra for EV battery coverage?
Generally, battery coverage is included under standard comprehensive and collision protection. You do not typically need a separate policy rider for the battery pack, as damage resulting from a covered peril like a collision, fire, or flood falls under standard automotive definitions.
How do I find out if my insurer offers a green vehicle discount?
The most reliable method is to contact your insurance agent directly or review the discount section of your provider's online portal. Not all green discounts are automatically applied during automated online quoting processes, so explicitly asking about alternative-fuel incentives is vital.
Does public charging station use affect my auto insurance?
No. Using public Level 3 DC fast chargers or municipal Level 2 chargers does not impact your auto insurance rates. However, if your home charging equipment is vandalized or damaged in your driveway, claims typically fall under your homeowners insurance policy rather than your auto policy.
Why do some insurers quote significantly higher rates for the same EV?
Insurance companies use proprietary underwriting algorithms that weight risk factors—such as local repair labor rates, regional accident statistics, and historical claims data for specific zip codes—differently. This is why gathering quotes from multiple national and regional carriers is essential to finding the best rate.
Securing Your Policy: Next Actions
Getting an accurate and affordable electric auto insurance quote requires looking past generalized assumptions and actively leveraging your vehicle's specific safety features, low-mileage habits, and green vehicle discounts. Begin by gathering the exact Vehicle Identification Number (VIN) of the model you intend to purchase, as trim levels directly influence safety equipment classification. Next, request comparative quotes from at least three distinct carriers, ensuring you ask specifically for alternative-fuel and telematics discounts. By approaching the quoting process equipped with accurate data, you can secure protection that keeps your electric vehicle ownership costs manageable from day one.
Image Gallery
Select an image to open it in a new tab.
Mateo Castillo
Decentralized Finance and E-Payments Strategist
