How a Debt Consolidation Loan Can Streamline Your Payments and Simplify Your Finances
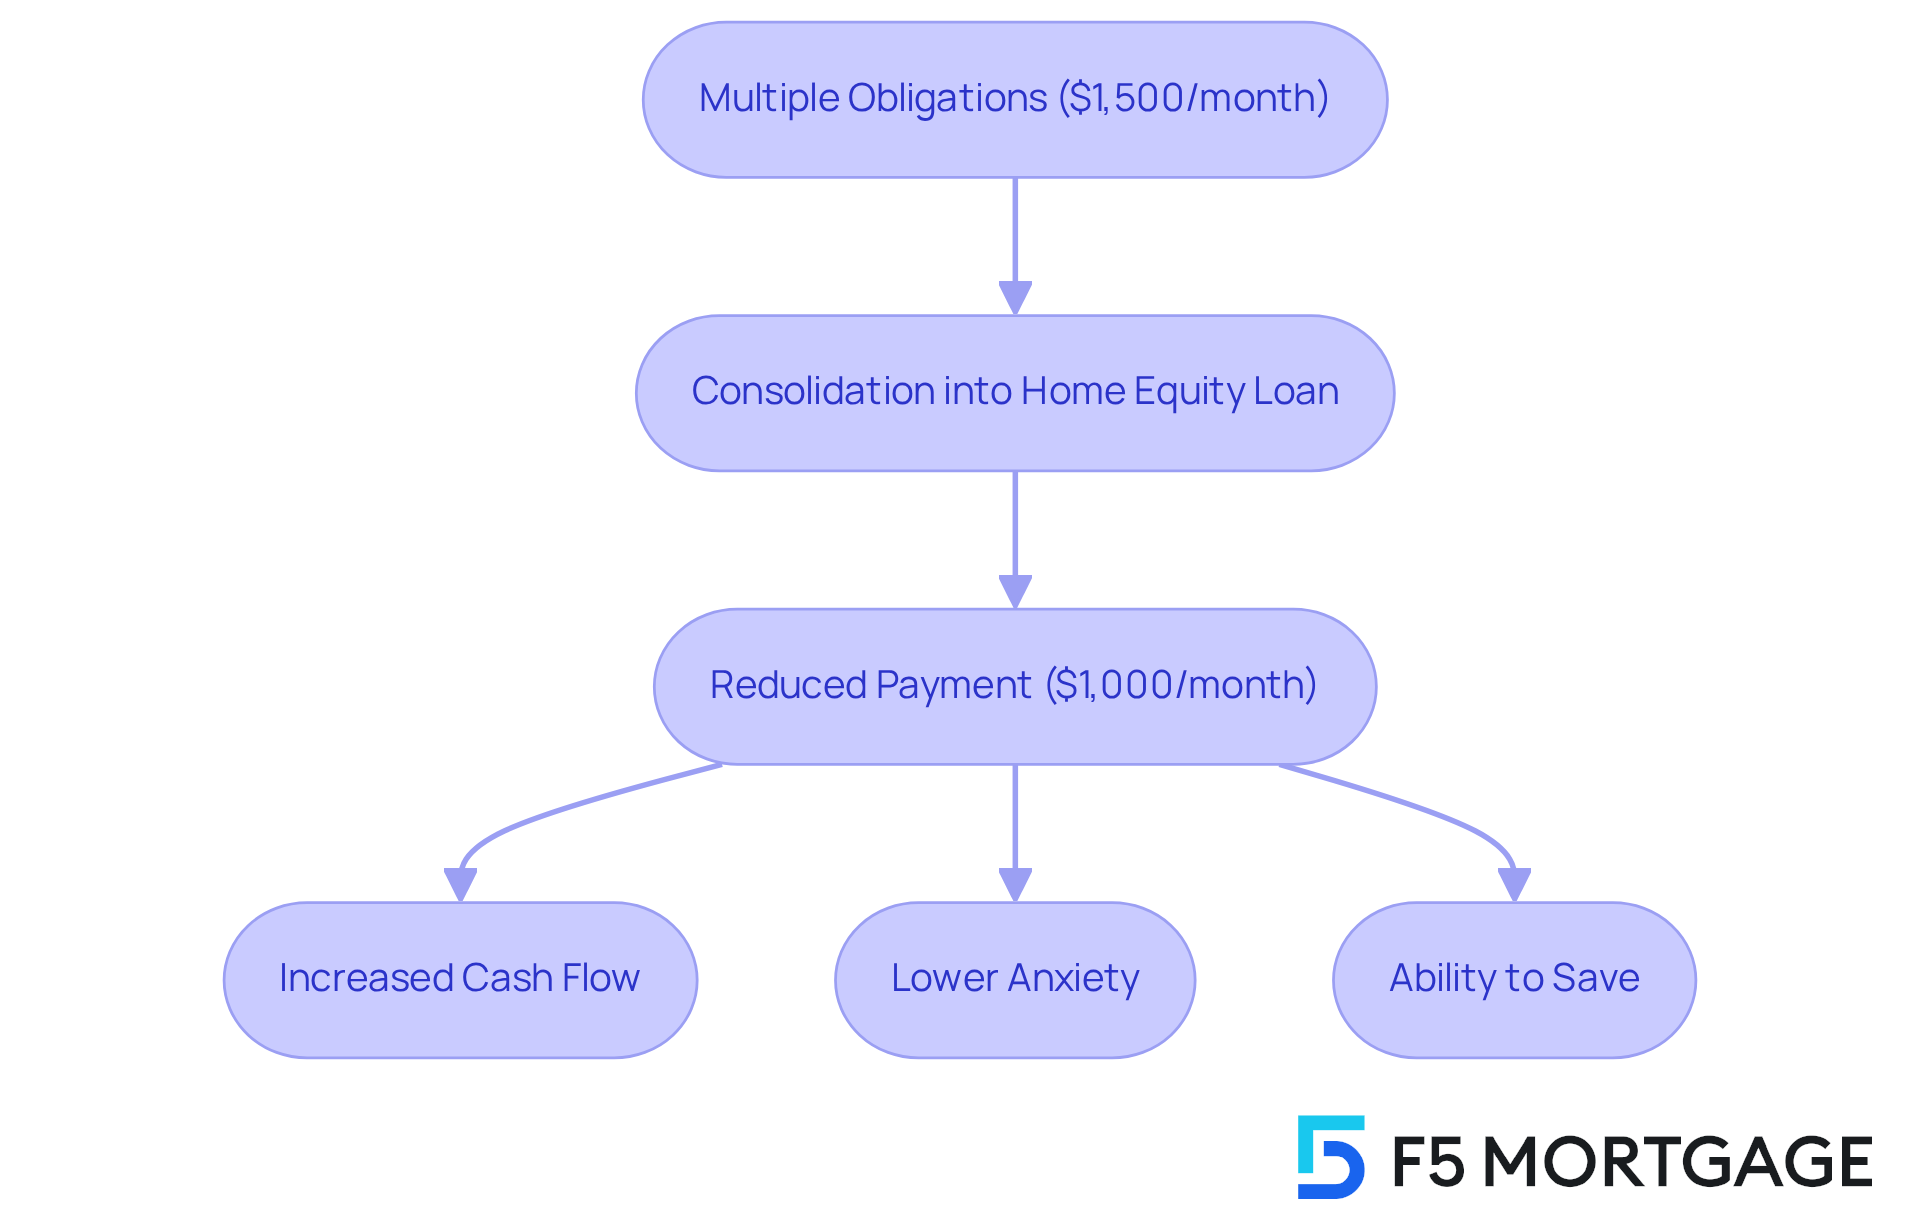
Managing multiple debts with varying interest rates, different due dates, and separate monthly bill payments can quickly become an overwhelming logistical burden. A debt consolidation loan can streamline your payments by combining all of your existing unsecured liabilities into a single, predictable monthly obligation with one fixed interest rate and one specific due date. This financial tool does not erase what you owe, but it fundamentally restructures how you interact with your debt, reducing administrative friction and providing a clear path toward long-term financial stability.
Navigating the world of personal finance requires a precise understanding of how various credit products function. For individuals juggling credit cards, personal loans, medical bills, and other unsecured debts, the daily mental load of tracking multiple payment deadlines increases the risk of missed payments, late fees, and credit score damage. Consolidating these obligations transforms a chaotic web of liabilities into a single, manageable transaction. However, achieving success with this strategy demands careful preparation, realistic budgeting, and an awareness of the underlying costs and qualifying requirements.
Understanding the Mechanics of Debt Consolidation
At its core, debt consolidation involves taking out a new loan to pay off several smaller debts. Rather than sending payments to three, four, or five different creditors every month, you send one payment to a single lender. That lender then distributes the funds or provides you with the cash payoff amount to clear your previous balances. Once the process is complete, your old accounts show a zero balance, and you are left with only the new consolidation loan.
This strategy is specifically designed for unsecured debt—obligations not tied to physical collateral like a home or a car. Common examples include credit card balances, personal lines of credit, and medical debt. Secured debts, such as mortgages and auto loans, are rarely included in standard consolidation loans because doing so would risk forfeiting major assets and often incurs prohibitive refinancing costs.
By shifting multiple balances into a single account, you effectively replace a complex matrix of revolving credit terms with a structured installment loan. This change brings predictability. Installment loans feature fixed monthly payments, fixed interest rates, and a predetermined payoff date, unlike revolving credit cards where minimum payments fluctuate and balances can linger indefinitely.
Key Benefits of Consolidating Your Debt
The primary advantage of consolidating your liabilities is administrative simplification. Remembering a single due date each month eliminates the cognitive burden of tracking multiple calendars and logging into various financial portals. This operational clarity significantly reduces the likelihood of human error, such as forgetting a payment or miscalculating a minimum due amount.
Beyond organizational ease, consolidation often provides significant financial benefits through interest rate optimization. Many consumers accumulate high-interest credit card debt, where annual percentage rates (APRs) can easily exceed 20% to 25%. If you qualify for a personal consolidation loan with a significantly lower APR, a larger portion of your monthly payment goes toward reducing the actual principal balance rather than servicing high interest charges.
Furthermore, extending your repayment term through a consolidation loan can lower your immediate monthly cash outflow. While stretching out a loan over a longer period may increase the total interest paid over the life of the loan, it can provide crucial short-term breathing room for households facing tight monthly cash flow constraints.
Comparison of Debt Management Approaches
| Feature | Multiple Credit Cards / Unsecured Debts | Traditional Debt Consolidation Loan | Debt Management Plan (DMP) |
|---|---|---|---|
| Number of Payments | Multiple per month | Exactly one per month | One consolidated payment via credit counseling agency |
| Interest Rates | Variable, often very high (20%+ APR) | Usually fixed, based on creditworthiness | Often reduced via creditor concessions |
| Credit Score Impact | High utilization can lower scores | Temporary dip from hard inquiry; improves long-term utilization | May require closing accounts, moderate initial impact |
| Fixed Payoff Timeline | Open-ended (revolving) | Fixed term (e.g., 3 to 5 years) | Fixed term (typically 3 to 5 years) |
| Collateral Required | None (unsecured) | None (unsecured personal loan) | None (informal agreements with creditors) |
Evaluating Eligibility and Prerequisites
Qualifying for a favorable debt consolidation loan depends heavily on your credit health, income stability, and overall debt-to-income (DTI) ratio. Lenders review these metrics to assess risk and determine the interest rate they will offer.
Credit Score and History
Your credit score is the primary driver of loan approval and pricing. Borrowers with good to excellent credit scores (typically 690 and above) have access to the lowest interest rates and most favorable terms. Those with fair or poor credit may still qualify for consolidation loans, but the interest rates offered might be high enough to negate the financial benefits of combining the debts.
Income and Debt-to-Income Ratio
Lenders require proof of stable income to ensure you can comfortably manage the new monthly payment. They calculate your DTI ratio by dividing your total monthly debt obligations by your gross monthly income. A lower DTI ratio indicates that you have adequate room in your budget to absorb the new loan payment without defaulting.
Fees and Origination Costs
Before committing to a loan, you must examine all associated costs. Many financial institutions charge origination fees—ranging from 1% to 8% of the total loan amount—which are often deducted directly from the disbursed funds. Additionally, you should check for prepayment penalties, which charge you a fee if you pay off the loan ahead of schedule. Choosing a lender with transparent, low-fee structures protects the financial gains you hope to achieve.
Step-by-Step Process to Consolidate Your Debts
Executing a successful debt consolidation strategy requires a methodical approach. Skipping steps or failing to audit your existing liabilities can lead to unexpected financial shortfalls.
- Audit Your Existing Debts: Compile a comprehensive list of all unsecured debts you intend to consolidate. Note the exact payoff amounts, current interest rates, and monthly payment requirements for each account.
- Check Your Credit Report: Obtain your credit reports and scores. Review them for errors and ensure your financial profile is accurate before applying for new credit.
- Shop and Compare Lenders: Research multiple financial institutions, including traditional banks, credit unions, and reputable online lenders. Compare APRs, loan terms, origination fees, and customer reviews.
- Apply for the Loan: Submit a formal loan application with your chosen lender, providing required documentation such as pay stubs, tax returns, and proof of identity.
- Directly Pay Off Previous Creditors: Once the loan funds are disbursed, immediately pay off the targeted credit cards and loans. To ensure a clean break, confirm with each old creditor that their respective accounts show a zero balance and are officially closed or set to zero.
- Establish a Sustainable Budget: With your new consolidated payment in place, design a monthly budget that prevents you from accumulating new revolving debt on the newly cleared credit cards.
Common Pitfalls and How to Avoid Them
While a debt consolidation loan provides an effective structural reset, it is not a cure-all for underlying spending habits. Recognizing common mistakes helps ensure long-term success.
The most dangerous pitfall is treating consolidation as a license to spend. Once credit card balances are paid off through the loan, those cards sit with available credit limits once again. If a borrower continues old spending habits and racks up new balances on those cards while still paying off the consolidation loan, they double their financial burden and face an even deeper debt crisis.
Another miscalculation is failing to secure an interest rate lower than the weighted average of current debts. If the new loan carries an APR higher than what you are currently paying across your existing balances, consolidation will cost more money over time. Always calculate the total cost of borrowing before signing a loan agreement.
Relying on predatory lenders represents a final major hazard. Borrowers desperate for financial relief may fall victim to subprime lenders advertising guaranteed approvals alongside exorbitant interest rates and hidden fees. Sticking with verified financial institutions, regulated credit unions, and transparent lending platforms safeguards your financial well-being.
Alternative Debt Relief Strategies
Debt consolidation loans are only one option among several structured debt relief methods. Depending on your financial severity and credit standing, other pathways might be more appropriate.
- Balance Transfer Credit Cards: Moving high-interest credit card debt to a new card offering a 0% introductory APR for a promotional period (often 12 to 21 months) allows you to pay down principal interest-free. This requires a strong credit score to qualify and usually incurs a 3% to 5% balance transfer fee.
- Debt Management Plans (DMPs): Administered by accredited non-profit credit counseling agencies, a DMP involves working with counselors to negotiate lower interest rates and fee waivers with your creditors. You make a single monthly payment to the agency, which distributes funds to your creditors.
- Debt Settlement: This involves negotiating with creditors to accept a lump-sum payment that is less than the total amount owed. While this can reduce total debt, it often requires stopping payments to creditors while building a cash reserve, which severely damages your credit score and can trigger tax liabilities on forgiven debt.
- Bankruptcy: As a legal last resort, Chapter 7 or Chapter 13 bankruptcy provides court-supervised debt discharge or restructuring for individuals facing insurmountable insolvency.
Frequently Asked Questions
Will a debt consolidation loan hurt my credit score?
Applying for a consolidation loan requires a hard credit inquiry, which causes a temporary, minor dip in your credit score. However, over the medium to long term, consolidating debt can improve your credit score by lowering your credit utilization ratio, establishing a history of on-time installment payments, and eliminating delinquent accounts.
Can I consolidate my debts if I have bad credit?
Yes, some lenders specialize in bad credit personal loans. However, these loans typically feature higher interest rates and stricter terms. If your credit score is very low, the costs may outweigh the benefits, making credit counseling or alternative debt relief strategies a safer choice.
Should I close my credit card accounts after consolidating them?
Closing credit cards can temporarily lower your credit score by reducing your total available credit and shortening your average credit history length. However, if you lack the discipline to keep the cards open without accumulating new charges, closing them may be necessary to prevent falling back into debt.
What is the difference between debt consolidation and debt settlement?
Debt consolidation involves paying off your full debt balance using a new, lower-interest loan, preserving your credit standing. Debt settlement involves negotiating with creditors to forgive a portion of what you owe in exchange for a lesser lump sum, which significantly harms your credit score and remains on your credit report for years.
Are there tax implications when taking out a debt consolidation loan?
No. A debt consolidation loan is simply a new form of borrowing and is not considered taxable income. Conversely, debt settlement programs that result in forgiven debt may treat the forgiven amount as taxable income under certain circumstances.
Practical Next Actions
If you find yourself struggling to track multiple due dates and paying high interest across various accounts, evaluate your current financial standing today. Pull your credit reports, calculate the total sum of your unsecured liabilities, and determine your current debt-to-income ratio. Research reputable lenders to compare loan offers without committing to a hard credit pull initially. By approaching debt consolidation with careful planning and financial discipline, you can successfully streamline your payments, reduce your interest costs, and regain control of your financial future.
Image Gallery
Select an image to open it in a new tab.


Simon Caldwell
Enterprise Technology and Systems Editor
