Determining the best Chase credit card depends entirely on your primary spending patterns and your goals for rewards redemption. Whether you seek to maximize travel experiences through the Ultimate Rewards ecosystem, build credit, or minimize interest payments with a 0% introductory APR period, Chase offers a tiered suite of products tailored to distinct financial profiles.
Understanding the Chase Ecosystem and Your Spending Profile
The "best" card is not a universal designation but a functional fit for your lifestyle. Chase manages a portfolio of credit cards that generally fall into three categories: everyday cash-back cards, travel-focused rewards cards, and specialized business products. Before selecting a card, you must assess your monthly budget and identify which categories consume the largest portion of your income.
For example, a high-spender in the grocery and dining categories will benefit significantly more from a card that offers 3x or 5x points on those purchases than a card that provides flat-rate rewards. Conversely, if your goal is simplicity, a flat-rate card is often superior to managing complex bonus categories. In 2026, Chase continues to utilize its Ultimate Rewards portal as the central hub for points, allowing users to consolidate earnings from multiple cards into a single pool. This is a critical factor for long-term strategy, as pairing cards—often referred to as a "Chase trifecta"—can drastically increase the value of your points when transferred to airline or hotel travel partners.
Assessing Your Credit Eligibility
Before applying for any credit product, you must account for Chase’s internal underwriting policies. The most notable of these is the "5/24 rule." While not an official, publicly published law, historical data and industry consensus confirm that Chase will generally deny an application for a new card if you have opened five or more personal credit cards from any bank within the preceding 24 months.
Beyond this, you must have a credit score that aligns with the specific product requirements. Premium cards, such as the Sapphire Reserve, typically demand an excellent credit score (generally considered 740 or higher) and a history of responsible credit management. If you are new to building credit or have a limited credit history, you may need to look at entry-level or secured credit options that focus on responsible usage rather than aggressive rewards.
Comparison of Primary Chase Credit Card Tiers
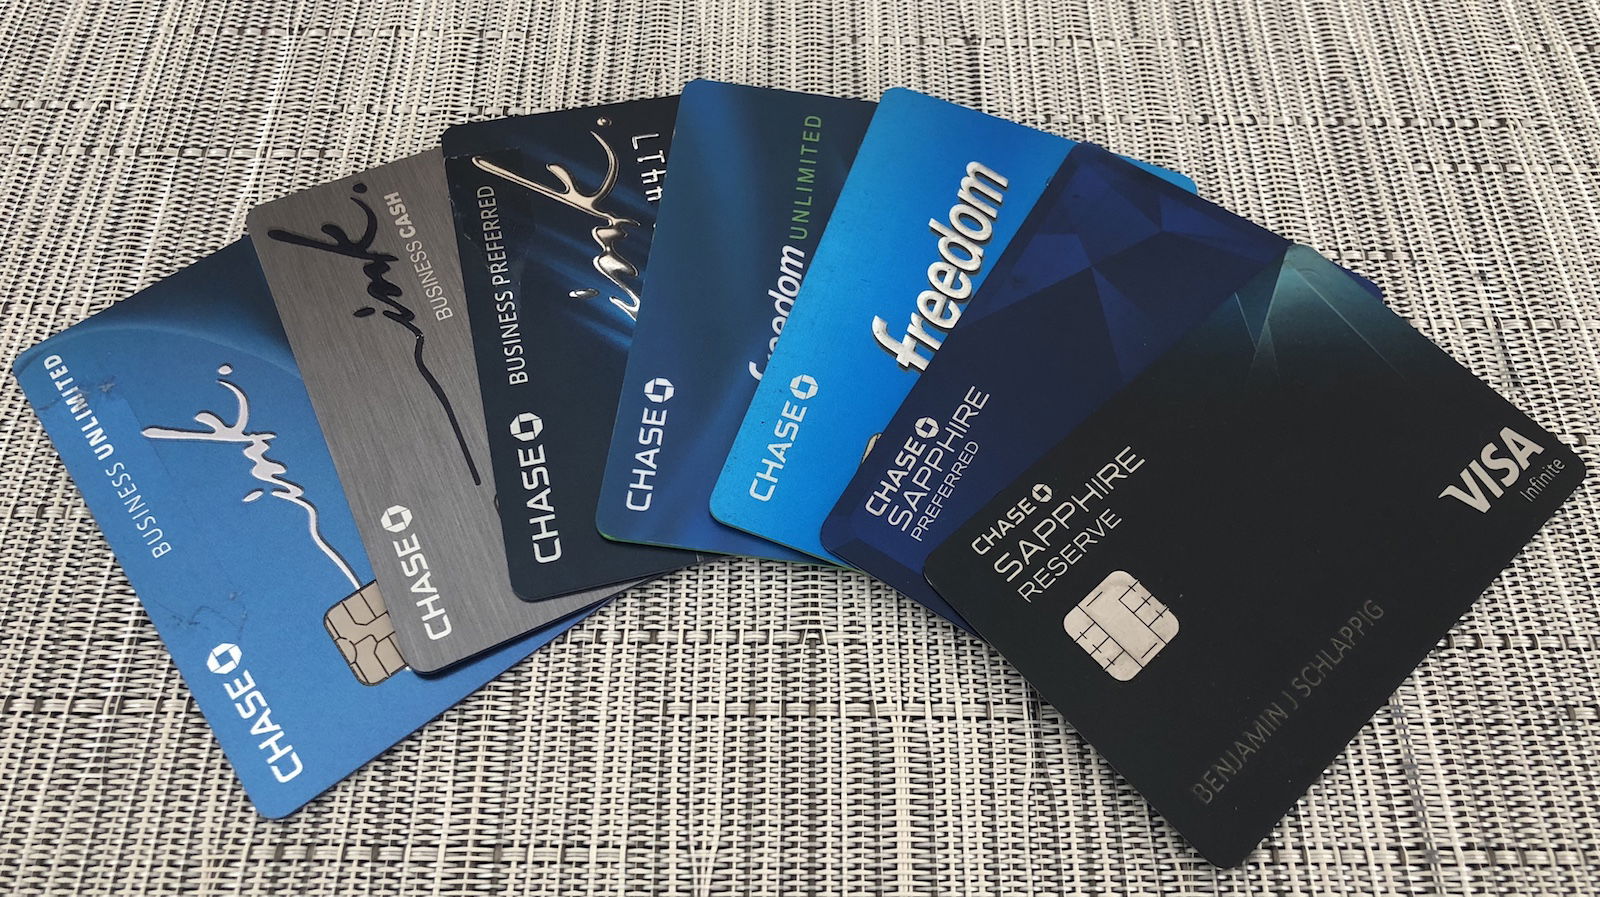
The following table outlines the key distinctions between common Chase products as of 2026. This comparison helps clarify which card provides the highest utility for your specific financial behaviors.
| Card Name | Best For | Annual Fee | Key Earning Structure |
|---|---|---|---|
| Chase Freedom Unlimited | Everyday Expenses | $0 | 1.5% to 5% cash back on categories |
| Chase Sapphire Preferred | Travel Rewards | $95 | 2x to 5x points on travel/dining |
| Chase Sapphire Reserve | Premium Travel | $550 | 3x to 10x points on travel/dining |
| Chase Freedom Flex | Bonus Categories | $0 | Rotating 5% quarterly categories |
| Chase Ink Business Cash | Small Business | $0 | High rates on office supplies/utilities |
Maximizing Your Rewards Strategy
Once you have selected a card, the next step is optimizing your point generation. If you hold multiple cards, understand which card to use for specific transactions. Many cardholders use the Freedom Flex for its rotating 5% categories, the Freedom Unlimited for general "everything else" purchases, and a Sapphire card for dining and travel.
Transferring points is where Chase cards gain significant value. Instead of redeeming points for statement credits—which often yields a value of 1 cent per point—transferring points to travel partners such as United MileagePlus, Hyatt, or Southwest Rapid Rewards can frequently yield a value exceeding 1.5 or 2 cents per point. This, however, requires more effort and planning, as you must research award availability and transfer timelines.
Common Mistakes to Avoid
Selecting a credit card based solely on the "sign-up bonus" is a common error. While these bonuses are lucrative, they only provide value if the card remains useful to you long-term. Always prioritize the card's ongoing earning potential and features, such as travel insurance, purchase protection, or extended warranties, which provide value regardless of whether you hit the sign-up bonus threshold.
Another frequent pitfall is carrying a balance. High-interest rates on credit cards can quickly negate any rewards earned. If you find yourself unable to pay your balance in full each month, prioritize a card with a low-interest or 0% introductory APR offer rather than a rewards-focused card. Additionally, be wary of the annual fees associated with premium cards. Only opt for a card with a high annual fee if your annual spending and travel habits will generate enough points or statement credits to offset that cost.
Managing Your Account and Troubleshooting
Once your account is open, proactive management is required to maintain your credit health and maximize benefits. Log in to the Chase mobile app or desktop portal regularly to check for "activated" bonus categories. Some cards, particularly the Freedom Flex, require you to manually activate your 5% quarterly bonus categories; if you fail to do so, you will only earn 1% on those purchases.
If you encounter technical issues or have questions about specific transactions, Chase’s customer service is reachable via secure message, phone, or in-branch visits. Keep in mind that for financial disputes, you have rights under the Fair Credit Billing Act to challenge erroneous charges. Documenting your transactions and maintaining records of your spending can assist in resolving disputes quickly.
FAQ: Solving Common Uncertainties
1. Can I upgrade my Chase card to a premium version later? Yes, you can often "product change" your card. If you start with a no-annual-fee card and later decide you want the travel benefits of a Sapphire card, you can request a product change. However, be aware that doing so may disqualify you from earning the sign-up bonus associated with that premium card, as those are usually reserved for new applicants.
2. How does the 5/24 rule affect my ability to get a business card? The 5/24 rule typically counts personal cards from any issuer, but business cards from some issuers may not report to your personal credit report. However, Chase usually counts any new account you have opened in the last 24 months toward the limit, regardless of whether it is a personal or business card.
3. What happens if I miss a payment? Missing a payment can lead to late fees and damage your credit score. If you miss multiple payments, your interest rate may increase, and you could lose access to your rewards. Always set up automatic payments for at least the minimum amount due to ensure your account remains in good standing.
4. Are Chase points transferable to other people? Yes, you can transfer your Ultimate Rewards points to a spouse or domestic partner who is also a Chase cardholder. This can be a useful strategy if one person has a premium card that offers better redemption values than the other person's card.
5. Is the Chase Sapphire Reserve worth the $550 fee? It is worth it only if you utilize the $300 annual travel credit, the airport lounge access, and the higher points valuation for travel bookings. If you do not travel frequently or do not spend enough on dining and travel to bridge the gap between the fee and the benefits, a card with a lower annual fee may be more cost-effective.
Next Steps for Your Selection
To decide which Chase card is right for you, perform a simple audit of your previous three months of spending. Total your expenditures in categories like dining, groceries, travel, and gas. Compare these totals against the rewards structures of the cards listed in this guide. Once you identify the card that aligns with your highest spending categories, check your current credit score to ensure you meet the issuer's baseline criteria. Applying for the card that matches your actual behavior, rather than the one with the most marketing, ensures you derive long-term financial utility from your choice.
Image Gallery
Select an image to open it in a new tab.



Celine Dubois
Contemporary Living and Global Arts Columnist
