
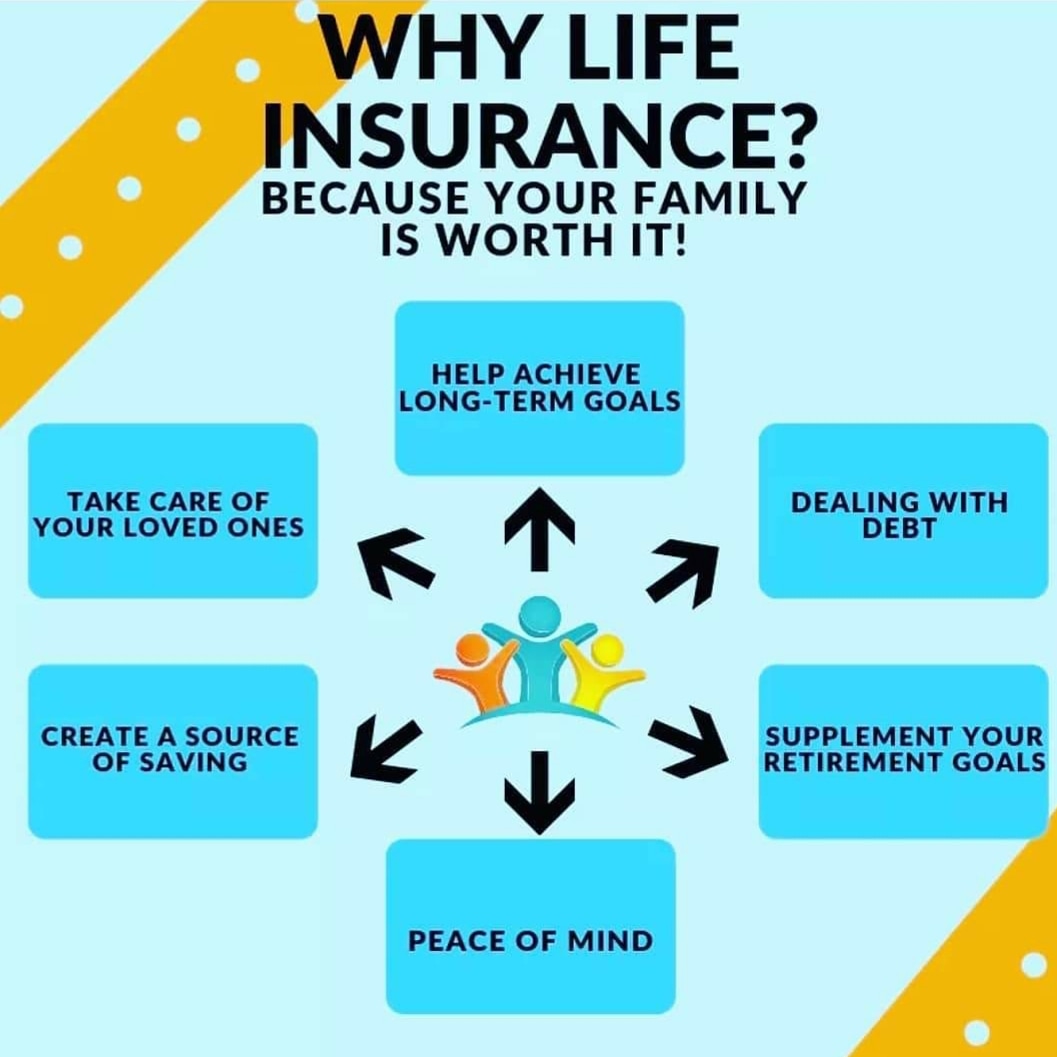
Personal life insurance provides a tax-free financial payout to beneficiaries upon the policyholder’s death, ensuring essential income replacement and debt coverage. Beyond basic protection, modern 2026 policies offer "living benefits," such as tax-deferred cash value accumulation, supplemental retirement income, and accelerated payouts for chronic or terminal illnesses, making it a foundational asset for comprehensive wealth management.
The Fundamental Role of Life Insurance in Financial Planning
In the financial landscape of 2026, personal life insurance has evolved from a simple "death benefit" tool into a sophisticated financial instrument. At its core, life insurance is a contract between an individual and an insurer, where the insurer guarantees a sum of money to named beneficiaries in exchange for premium payments. However, the true value of these policies lies in their ability to mitigate the various risks associated with human capital—the present value of an individual's future earnings.
For many families, the primary breadwinner’s income is the engine that drives everything from daily mortgage payments to long-term retirement savings. The sudden removal of that engine can lead to immediate financial insolvency. Personal life insurance acts as a self-completing financial plan. If the policyholder lives, they continue to fund their goals; if they pass away prematurely, the insurance policy provides the capital necessary to reach those same milestones. This "liquidity on demand" is a unique characteristic that other asset classes, such as real estate or traditional brokerage accounts, cannot replicate with the same speed or tax efficiency.
Direct Financial Benefits: The Death Benefit and Beyond
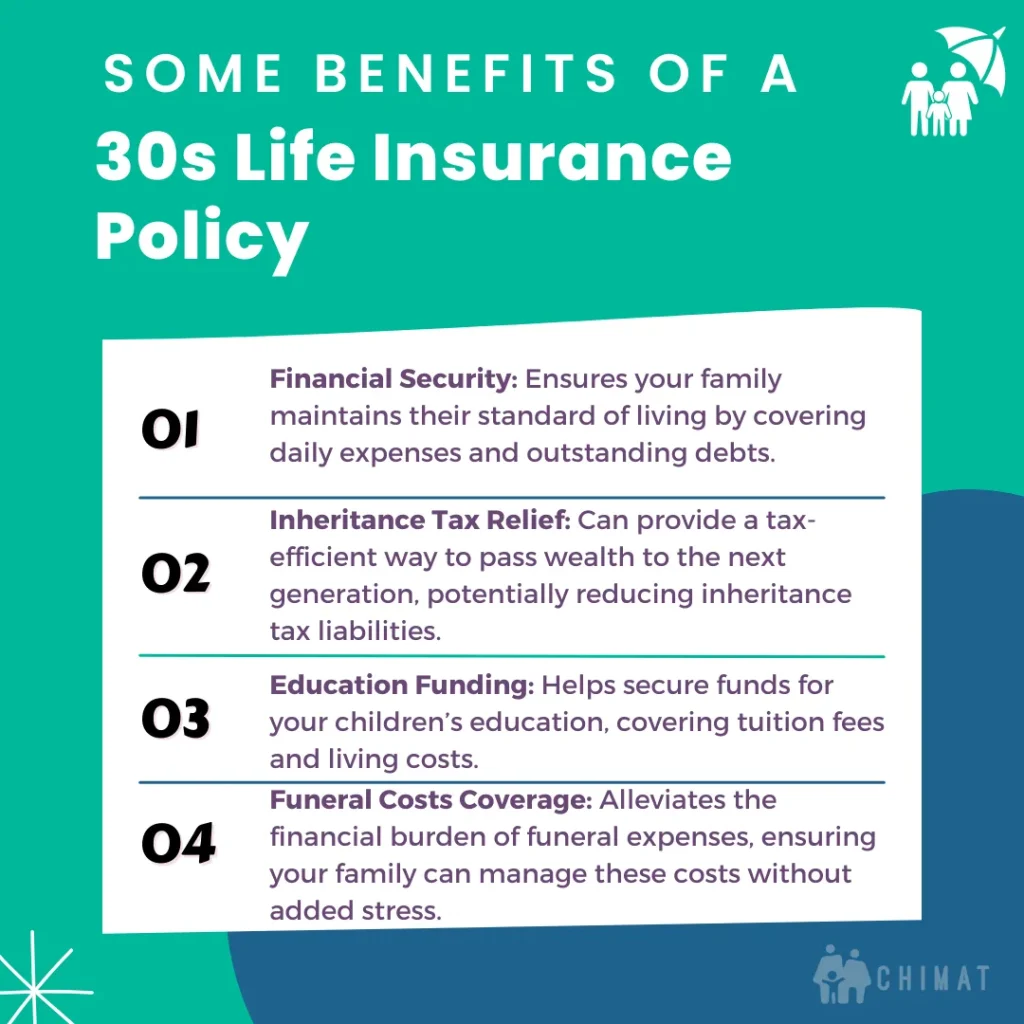
The most immediate and well-known benefit of personal life insurance is the death benefit. This lump-sum payment serves multiple roles, each critical to the survival of the family unit or the stability of an estate.
Immediate Income Replacement
Income replacement is often the primary motivator for purchasing personal life insurance. Experts generally suggest a coverage amount ranging from 10 to 15 times an individual’s annual salary. In 2026, this calculation has become more nuanced due to shifting inflation rates and the cost of living. The death benefit replaces the "lost" years of work, allowing a surviving spouse to maintain their standard of living, fund household operations, and avoid the necessity of selling assets in a down market.
Income replacement is not just about replacing a paycheck; it is about replacing the opportunity that paycheck provides. This includes the ability to continue contributing to retirement accounts (like 401ks or IRAs) and the funding of a spouse's future social security credits.
Debt Elimination and Mortgage Protection
Personal life insurance is frequently used to "self-insure" major liabilities. A mortgage is typically the largest debt a household carries. A dedicated life insurance policy ensures that the family home remains a secure asset rather than a liability that must be liquidated. Furthermore, it covers secondary debts such as auto loans, personal lines of credit, and credit card balances. By clearing these debts, the death benefit ensures that the remaining inheritance is not eroded by creditors, providing a clean slate for the beneficiaries.
Funding Educational Goals
For parents, life insurance provides a guarantee that their children’s education will be funded regardless of the parent’s presence. With the cost of higher education continuing to climb in 2026, the death benefit can be earmarked for 529 plans or direct tuition payments. This ensures that the next generation’s upward mobility is not compromised by an untimely family tragedy.
The Tax Advantages of Personal Life Insurance
The Internal Revenue Code provides significant tax advantages to life insurance that are rarely matched by other financial products. These benefits are codified under sections like IRC Section 101(a), which generally excludes life insurance proceeds from the beneficiary’s gross income.
Tax-Free Death Benefits
The primary tax advantage is that death benefits are typically paid out to beneficiaries 100% income-tax-free. This is a massive "multiplier" effect. If a beneficiary receives $1,000,000 from a life insurance policy, they keep the full amount. In contrast, a $1,000,000 withdrawal from a traditional 401(k) or IRA would be subject to federal and potentially state income taxes, leaving the beneficiary with significantly less. This tax-free nature makes life insurance one of the most efficient ways to transfer wealth between generations.
Tax-Deferred Accumulation
Permanent life insurance policies—such as Whole Life, Universal Life, and Variable Universal Life—contain a "cash value" component. The growth of this cash value is tax-deferred, meaning the policyholder does not pay taxes on the interest, dividends, or capital gains earned within the policy each year. Over decades, this tax-free compounding can lead to substantial wealth accumulation that is shielded from the drag of annual taxation.
Tax-Free Access to Cash Value
Policyholders can often access their cash value tax-free through a combination of basis withdrawals and policy loans. As long as the policy remains in force and is not classified as a Modified Endowment Contract (MEC), loans taken against the cash value are not considered taxable income. This provides a flexible source of capital for emergencies, business opportunities, or supplemental retirement income.
Living Benefits: Accessing Value While Alive
The modern 2026 approach to personal life insurance emphasizes "living benefits." These are provisions that allow the policyholder to utilize the policy’s value or the death benefit while they are still alive, addressing risks that go beyond mortality.
Cash Value Accumulation and Liquidity
Permanent policies act as a "forced savings" vehicle. A portion of every premium payment is directed into the cash value account. In 2026, many individuals use this as a "Tier 1" asset—a safe, liquid reservoir of capital that is not correlated with the volatility of the stock market. This liquidity can be used for:
- Down payments on property: Using policy loans to fund real estate investments.
- College funding: Supplementing or replacing traditional student loans.
- Business capital: Providing quick access to funds for entrepreneurs without the need for bank credit checks.
Accelerated Death Benefit (ADB) Riders
One of the most impactful developments in recent years is the widespread inclusion of Accelerated Death Benefit riders. These allow the policyholder to access a portion of the death benefit if they are diagnosed with a terminal, chronic, or critical illness. In 2026, where long-term care costs have become a major concern for aging populations, these riders provide a vital safety net. If a policyholder cannot perform two of the six "Activities of Daily Living" (ADLs), they can trigger these benefits to pay for home healthcare, nursing home stays, or medical bills, preserving other family assets.
Comparing Personal Life Insurance Policy Structures
Choosing the right policy depends on the specific goals of the individual. The following table compares the most common types of personal life insurance available in 2026.
| Policy Type | Coverage Duration | Cash Value Component | Premium Structure | Primary Benefit |
|---|---|---|---|---|
| Term Life | Temporary (10–30 years) | None | Fixed for the term | Low-cost, pure protection for high-need years. |
| Whole Life | Permanent (Lifetime) | Guaranteed growth | Level premiums | Lifetime protection with guaranteed equity. |
| Universal Life | Permanent (Flexible) | Market-linked or fixed | Flexible premiums | Adaptable coverage that can change with life stages. |
| Indexed Universal Life | Permanent (Flexible) | Tied to market index (e.g., S&P 500) | Flexible premiums | Upside market potential with a guaranteed 0% floor. |
| Variable Universal Life | Permanent (Flexible) | Direct market investment | Flexible premiums | Maximum growth potential for risk-tolerant owners. |
Modern Underwriting and Accessibility in 2026
The process of obtaining personal life insurance has been transformed by technology. In 2026, "Accelerated Underwriting" is the standard for many healthy individuals. By using big data, medical prescription histories, and even wearable device data (with consent), insurers can often issue policies within minutes or hours, bypassing the traditional "paramedical exam" that required blood draws and physicals.
This increased accessibility means that younger individuals can lock in low rates early. Since age and health are the primary drivers of premium costs, the benefit of starting a personal policy early is compounded over time. Furthermore, many modern term policies are "convertible," meaning the owner can switch to a permanent policy later without a new medical exam, protecting their insurability even if their health declines.
Estate Planning and Wealth Transfer
For high-net-worth individuals, personal life insurance is a critical tool for estate equalization and liquidity.
Estate Tax Liquidity
While federal estate tax thresholds are high, they are subject to legislative change. Life insurance provides the immediate cash necessary to pay estate taxes, legal fees, and administrative costs. This prevents the "fire sale" of family businesses or illiquid real estate assets to satisfy the IRS.
Estate Equalization
In families where a primary asset (like a family farm or a business) is being left to one child who is active in the operation, life insurance can be used to provide an "equal" inheritance to other children who are not involved. The active child receives the business, while the other children receive an equivalent value via the life insurance death benefit. This helps maintain family harmony and ensures a fair distribution of wealth.
Charitable Giving
Life insurance allows individuals to leave a much larger legacy to a charity than they might be able to through a simple cash donation. By naming a 501(c)(3) organization as the beneficiary, the policyholder can leverage relatively small premium payments into a significant, transformative gift for the organization upon their death.
Selecting the Right Coverage: A Strategic Guide
When evaluating the benefits of personal life insurance, it is essential to follow a structured approach to ensure the policy aligns with long-term financial goals.
- Conduct a Needs Analysis: Determine the total amount of debt, future income requirements for survivors, and educational goals. Subtract existing assets to find the "coverage gap."
- Determine the Duration of Need: If the need is temporary (e.g., until the kids graduate or the mortgage is paid), term insurance is the most cost-effective. If the need is permanent (e.g., estate taxes or final expenses), a permanent policy is required.
- Evaluate Cash Flow: Ensure the premiums are sustainable. A policy that lapses because it is too expensive provides no benefit.
- Review Riders: Consider adding riders for Waiver of Premium (which pays the premium if you become disabled) or Long-Term Care (LTC) to add layers of protection.
Frequently Asked Questions
What is the "7-Pay Test" and why does it matter?
The 7-pay test is a calculation used to determine if a life insurance policy is "overfunded" according to IRS rules. If a policyholder puts too much money into a policy within the first seven years, it becomes a Modified Endowment Contract (MEC). Once a policy is a MEC, loans and withdrawals are taxed as "income first" and may be subject to a 10% penalty if taken before age 59.5, losing some of the policy’s tax-free "living benefits."
Can I have both group life insurance and personal life insurance?
Yes, and it is often recommended. Group life insurance through an employer is a great benefit but is usually limited to 1x or 2x your salary, which is rarely enough for a family's needs. Furthermore, group insurance is typically not portable; if you leave your job, you lose the coverage. Personal life insurance stays with you regardless of your employment status.
How does the "Waiver of Premium" rider work?
A Waiver of Premium rider is an optional add-on that protects the policyholder in the event of a total disability. If you become disabled and cannot work (usually for six months or more), the insurance company pays the premiums on your behalf to keep the policy in force. This ensures your family remains protected even when you lose your earning capacity.
Are life insurance dividends guaranteed?
No, dividends in a participating whole life policy are not guaranteed. They represent a return of part of the premium paid and are based on the insurance company's performance, including their mortality experience, investment returns, and expenses. However, many top-tier mutual insurers have a history of paying dividends every year for over a century.
What is "Convertible" term insurance?
A convertible term policy allows the policyholder to exchange their term coverage for a permanent policy (like Whole Life) without undergoing a new medical exam. This is a crucial benefit because it allows you to lock in protection while you are young and healthy, with the option to secure permanent coverage later even if you develop a health condition that would otherwise make you uninsurable.
Practical Recommendation
For most individuals in 2026, the most effective strategy is a "layered" approach. Start by securing a large Term Life policy to cover high-responsibility years (mortgage and child-rearing) and supplement it with a smaller Permanent Life policy to build a cash value reserve and cover final expenses. This combination provides maximum death benefit protection during the years you need it most while creating a long-term, tax-efficient financial asset for the future. Always consult with a licensed financial professional to ensure the policy structure meets specific jurisdictional and tax requirements.
Image Gallery
Select an image to open it in a new tab.
Celine Dubois
Contemporary Living and Global Arts Columnist
