
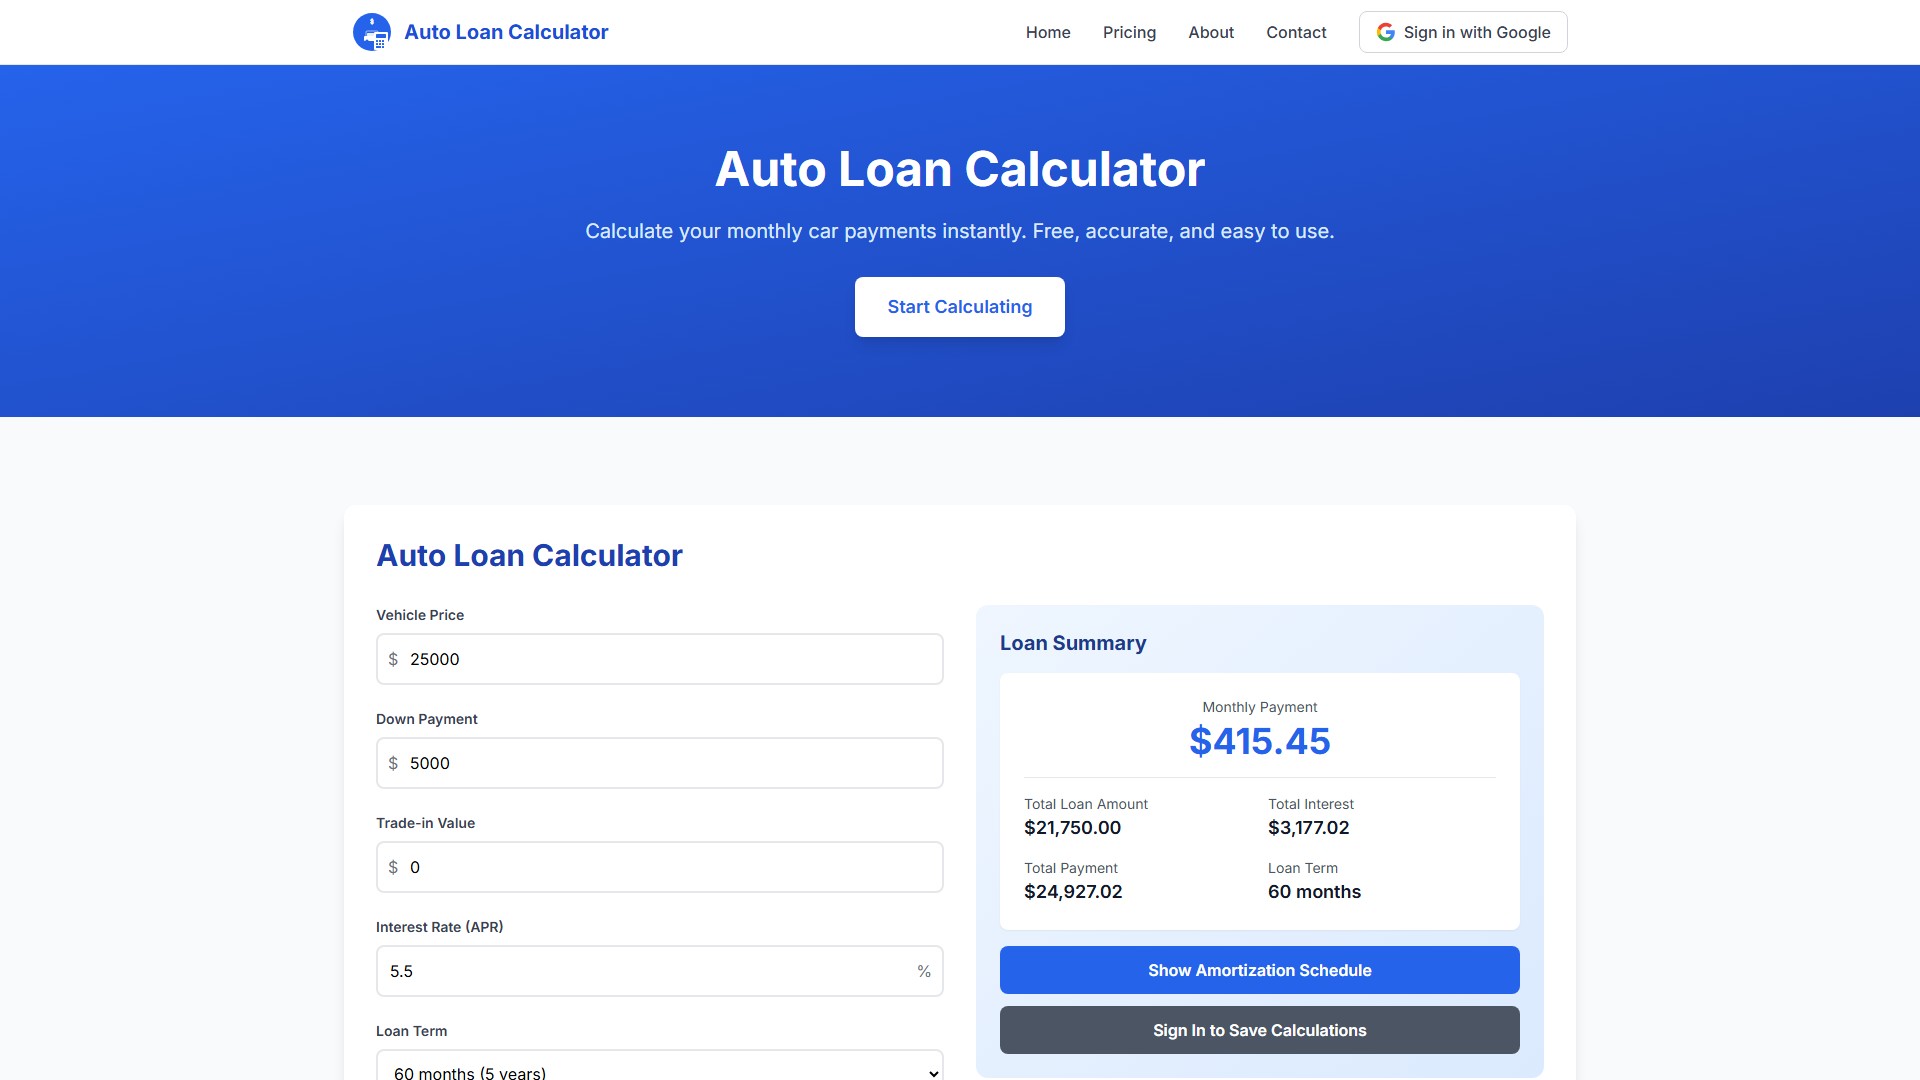
The SchoolsFirst Federal Credit Union auto loan calculator is a digital financial tool designed to help prospective borrowers estimate monthly payments, understand the impact of interest rates, and determine the total cost of financing a vehicle. By inputting variables such as the loan amount, interest rate (APR), and repayment term, users can project their financial obligations and assess the affordability of a prospective car purchase before applying for credit.
The Role of Digital Financial Calculators in Auto Financing
In the modern lending landscape, transparency is a critical component of consumer financial health. When a member of SchoolsFirst Federal Credit Union considers financing a vehicle, they are faced with a complex array of variables that determine the long-term feasibility of the loan. Digital calculators serve as the primary interface for navigating these variables.
Unlike static interest tables, a dynamic calculator allows for real-time adjustments. If a user discovers that their monthly budget cannot accommodate a five-year loan term, they can instantly toggle to a six-year term to see how the payment changes. This immediate feedback loop is essential for managing personal financial expectations. By providing this tool, the credit union enables members to perform "what-if" analyses, reducing the likelihood of payment shock after the loan is finalized.
Core Components of the Calculator
To effectively use the SchoolsFirst auto loan calculator, one must understand the relationship between the inputs and the output. Every loan calculation is a mathematical function of four primary variables:
1. The Loan Amount
This is the total principal you intend to borrow. It is important to note that this figure often differs from the sticker price of the vehicle. If you are rolling in taxes, title fees, or negative equity from a trade-in, these costs must be added to the base price of the car to reach your true loan amount. Failing to account for these "out-the-door" costs is a common error that leads to an underestimation of the monthly payment.
2. The Annual Percentage Rate (APR)
The APR represents the annual cost of the loan, including interest and certain fees. A lower APR reduces the interest paid over the life of the loan. SchoolsFirst, like other credit unions, typically offers competitive rates based on the borrower’s credit profile, the age of the vehicle, and the loan term. It is helpful to use the "representative" or "starting-at" rates provided by the institution to obtain a conservative estimate.
3. The Loan Term
The term is the length of the loan, usually expressed in months (e.g., 36, 48, 60, or 72 months). Shorter terms result in higher monthly payments but lower total interest charges. Longer terms provide more "breathing room" in the monthly budget but increase the total cost of borrowing due to prolonged interest accumulation.
4. The Monthly Payment
This is the output generated by the calculator. It represents the fixed amount due each month to satisfy the debt. It is critical to remember that this figure is generally principal and interest only; it does not include ongoing costs like auto insurance, registration renewals, or fuel.
Strategic Application of Calculator Results
Once you have generated an estimate, the data should be used to inform your broader financial strategy. Using the tool effectively goes beyond simple math; it requires a realistic assessment of your household budget.
Assessing Debt-to-Income (DTI) Impact
A significant part of your financial health is the ratio of your monthly debt payments to your gross monthly income. Financial experts generally suggest that a total auto payment—including insurance—should not exceed 10% to 15% of your take-home pay. By using the calculator to find a monthly payment that fits this threshold, you protect your ability to save for other goals, such as retirement or emergency funds.
Comparing New vs. Used Vehicle Financing
SchoolsFirst Federal Credit Union may offer different interest rates for new versus used vehicles. By running two sets of calculations—one for a new vehicle at a lower rate and one for a used vehicle at a potentially higher rate—you can determine if the lower purchase price of a used car is offset by the higher interest expense.
The True Cost of "Extended" Terms
Many borrowers are tempted by 72 or 84-month terms because they lower the monthly payment. However, the calculator reveals the long-term cost. Use the tool to compare two different terms for the same loan amount. You will likely notice that while the monthly payment drops on the longer term, the "total cost of loan" increases significantly. This is a vital metric for determining if you are buying "more car" than you can actually afford.
Comparative Overview of Loan Structures
The following table demonstrates how changing the loan term affects the monthly payment and total interest paid for a hypothetical $30,000 loan at a 6.00% APR.
| Loan Term (Months) | Monthly Payment | Total Interest Paid | Total Cost of Loan |
|---|---|---|---|
| 36 | $912.66 | $2,855.76 | $32,855.76 |
| 48 | $704.55 | $3,818.40 | $33,818.40 |
| 60 | $579.99 | $4,799.40 | $34,799.40 |
| 72 | $498.44 | $5,887.68 | $35,887.68 |
Note: The figures in this table are estimates for illustrative purposes. Actual loan terms and interest rates are subject to credit approval and specific member eligibility at the time of application.
Common Mistakes When Estimating Auto Loans
Even with a precise calculator, users often fall into traps that skew their projections. Avoiding these errors is essential for accurate planning.
- Ignoring Taxes and Fees: As mentioned, many users calculate based on the dealer's advertised price. Always add 8% to 10% to that price to account for sales tax, documentation fees, and registration costs to get a more accurate loan principal.
- Assuming the Best Rate: Calculators often allow you to input an interest rate. If you input the lowest advertised rate found on a website, you may be disappointed if your credit profile qualifies you for a higher tier. It is safer to run a "high-end" interest scenario to ensure you can afford the payment even if you don't receive the "perfect credit" rate.
- Overlooking Down Payments: A down payment is a powerful tool to lower the principal. Many people forget that they can adjust the "Loan Amount" input in the calculator to reflect the price of the car minus their down payment. This reduces the total interest paid and lowers the monthly obligation.
Integrating Calculator Data with Credit Union Requirements
Before relying on your calculations, you must recognize that SchoolsFirst, like all financial institutions, will perform its own underwriting. The calculator provides a simulation, but the final offer depends on several institutional factors.
Credit Score Sensitivity
Your credit score is the primary driver of the APR you will receive. If your credit score has fluctuated recently, the APR used in your calculation might be inaccurate. It is wise to check your credit report periodically and use a conservative estimate for your APR when using the calculator.
Vehicle Eligibility
Credit unions often have specific policies regarding the age and mileage of vehicles they will finance. A very high-mileage used car may not qualify for the same rates as a newer pre-owned model. Before finalizing your budget, confirm with the credit union if the specific vehicle you are eyeing meets their financing criteria.
Frequently Asked Questions
Does using the calculator affect my credit score?
No. Using the SchoolsFirst auto loan calculator is an informational activity and is not a formal application for credit. It does not trigger a hard inquiry on your credit report.
Why is my calculated monthly payment different from what the dealer offered?
The dealer may be including add-ons like extended warranties, gap insurance, or service contracts in the loan principal. Ensure your manual calculation includes all these "back-end" products if you intend to finance them.
Can I include my trade-in value in the calculation?
Yes. To calculate properly, subtract your estimated trade-in value from the purchase price of the new vehicle. Input the resulting amount as your "Loan Amount."
How often should I re-run the numbers?
You should re-run your numbers every time there is a change in your financial status, a significant change in interest rates, or once you have a firm "out-the-door" price from a dealer.
Does the calculator account for sales tax?
Most basic auto loan calculators do not automatically include sales tax. You must calculate the tax based on your local jurisdiction and add that amount to your loan principal before inputting it into the tool.
What should I do if the calculator shows I can't afford the car?
If the numbers don't work, you have three options: increase your down payment, choose a less expensive vehicle, or opt for a longer term—though the latter is usually discouraged due to the increased total interest expense.
Next Actions and Recommendations
To move from the planning phase to the acquisition phase, follow these logical steps:
- Gather Your Documents: Before visiting a dealer or applying online, have your recent pay stubs and proof of employment ready to verify your income.
- Run the Calculator with Multiple Scenarios: Do not settle for one set of numbers. Test a "best case" scenario (good rate, high down payment) and a "realistic case" scenario (moderate rate, standard down payment) to see the range of potential payments.
- Get Pre-Approved: Instead of relying on dealer financing, visit the SchoolsFirst official platform or a branch to seek pre-approval. This gives you a concrete interest rate and budget to work with, turning your "calculated" estimate into a firm financial offer.
- Confirm Fees: When you receive a purchase agreement from a dealer, verify that the total loan amount matches the figures you used in your calculator. If the dealer adds unexpected fees, stop and recalculate to ensure the monthly payment remains within your 10% to 15% target range.
By treating the calculator as a decision-support tool rather than just a simple math utility, you can ensure that your next vehicle purchase is a financially sound decision that aligns with your long-term goals.
Image Gallery
Select an image to open it in a new tab.


Declan O'Connor
Higher Education and Campus Culture Reporter
