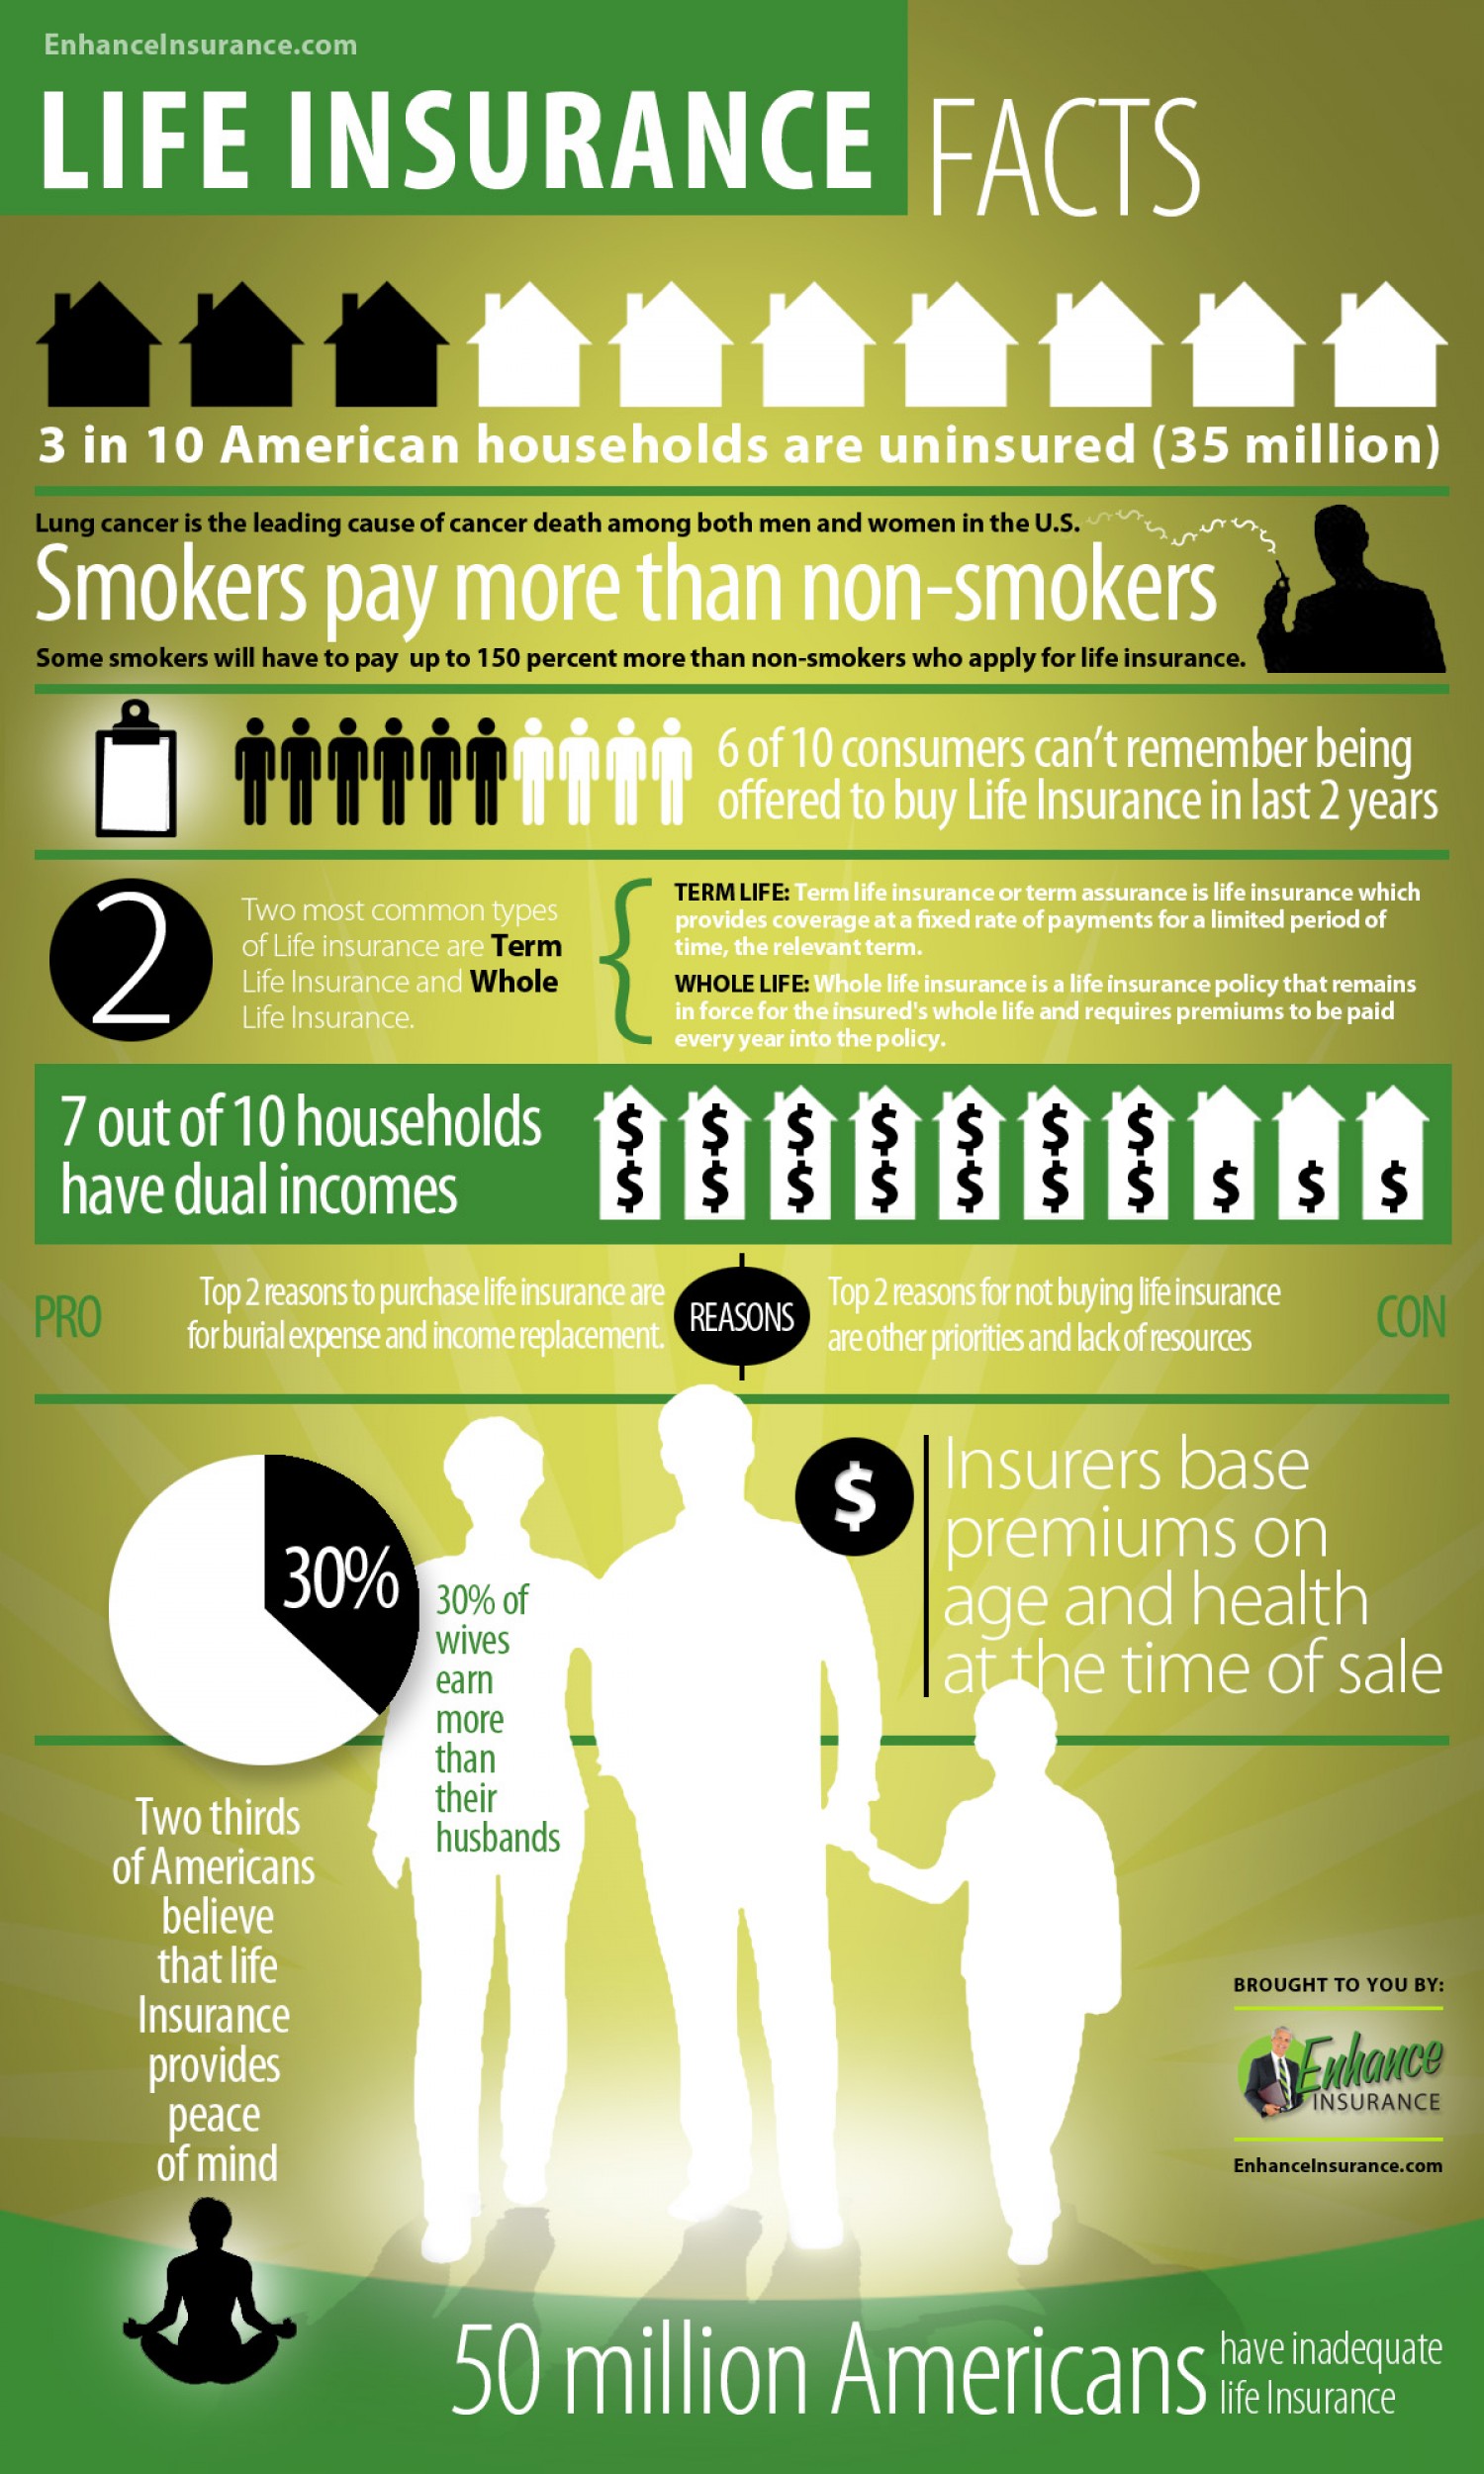
Determining the right amount of life insurance requires balancing your current financial obligations with the future needs of your beneficiaries. Most financial experts recommend a death benefit equal to 10 to 15 times your gross annual income. However, a precise calculation should account for existing debts, mortgage balances, and anticipated costs like college tuition.
Determining the ideal life insurance death benefit is one of the most significant financial decisions an individual will make. It is not merely a matter of picking a round number that feels sufficient; it is a calculated effort to ensure that, in the event of your passing, your family’s standard of living remains uninterrupted. As of 2026, the economic landscape—characterized by evolving housing markets and shifting education costs—makes a "one size fits all" approach increasingly obsolete. A practical overview of coverage requires a deep dive into various methodologies, ranging from simple heuristics to complex capital needs analyses.
The primary purpose of life insurance is to act as a financial safety net. It replaces the economic value of a human life, providing liquidity when it is needed most. Without adequate coverage, survivors may be forced to make drastic lifestyle changes, such as selling a family home, uprooting children from schools, or depleting retirement savings to cover immediate funeral and living expenses. To avoid these outcomes, you must look beyond the immediate future and project financial requirements decades into the distance.
The Rule of Thumb: 10 to 15 Times Income
For many years, the standard recommendation has been to purchase a policy worth roughly 10 times your annual salary. In 2026, many advisors have adjusted this upward to 15 times income to account for sustained inflation and the rising cost of healthcare and services. This "Income Replacement" method is popular because it is easy to calculate and provides a significant cushion.
The logic behind this rule is rooted in the concept of "capital preservation." If a beneficiary receives a payout of $1.5 million (15 times a $100,000 salary) and invests that sum conservatively at a 4% to 5% return, they could theoretically generate $60,000 to $75,000 in annual income indefinitely without ever touching the principal. This ensures the family has a perpetual stream of revenue that mimics the lost paycheck. However, this method has limitations. It does not account for specific debts, such as a large remaining mortgage, nor does it factor in the unique needs of families with many children versus those with none.
While the income-multiple approach is an excellent starting point, it should be viewed as a floor rather than a ceiling. For younger individuals with many decades of earning potential ahead of them, a higher multiple is often necessary. Conversely, those nearing retirement with significant accumulated assets might find that a lower multiple suffices.
The DIME Formula: A Targeted Approach
A more comprehensive way to calculate coverage is the DIME formula, which stands for Debt, Income, Education, and Mortgage. This method moves away from broad generalizations and looks at the specific "buckets" of expense your family would face.
Debt and Final Expenses
The first step is totaling all outstanding consumer debt. This includes credit card balances, personal loans, and auto loans. You should also include a budget for final expenses, such as funeral costs and medical bills not covered by insurance. In 2026, the average cost of a traditional funeral and burial often exceeds $12,000. By including these in your coverage amount, you ensure your family isn't hit with a massive bill during an already difficult emotional period.
Income Replacement
This is often the largest component of the DIME formula. Determine how many years your family will need to rely on your income. If you have young children, you might want to provide coverage until the youngest turns 18 or 22. If you are the sole breadwinner for a spouse, you may want to provide income for a much longer duration. Multiply your annual take-home pay by the number of years you wish to provide support.
Mortgage
For most households, the mortgage is the largest recurring expense. Including the full payoff amount of your mortgage in your life insurance policy provides your family with the ultimate security: a debt-free home. This significantly reduces the monthly income required for survivors to stay afloat. Even if your survivors choose not to pay off the mortgage immediately, having the capital to do so provides flexibility and peace of mind.
Education
The cost of higher education continues to be a major variable in financial planning. If you intend to fund college for your children, you must estimate these future costs. According to data from the College Board, the price of tuition, room, and board has historically outpaced general inflation. When calculating this for a 2026 policy, it is prudent to factor in the projected costs for the year your child will likely enter university, rather than today’s prices.
Human Life Value vs. Capital Needs Analysis
Beyond the DIME formula, professional financial planners often use more technical methods: the Human Life Value (HLV) approach and the Capital Needs Analysis.
The Human Life Value approach calculates the total amount of income you are expected to earn during your remaining working years. It considers your current age, your expected retirement age, your current earnings, and projected raises. This total is then discounted to "present value" to account for the fact that a dollar today is worth more than a dollar twenty years from now. This method is particularly useful for high-earners whose lifestyle is tied to a specific career trajectory.
The Capital Needs Analysis is more granular. It calculates the immediate cash needed at death (taxes, debts, funeral) and adds it to the present value of the family’s ongoing income needs. It then subtracts all available assets—such as existing savings, 401(k) balances, Social Security survivor benefits, and other insurance policies. The resulting "gap" is the amount of life insurance you should purchase. This is generally considered the most accurate method because it accounts for the resources you already have.
Factoring in Inflation and 2026 Economic Realities
In 2026, inflation protection is a critical component of any "practical overview." If you buy a $1 million policy today, that million dollars will have significantly less purchasing power in 2046. When calculating your coverage, it is wise to add an "inflation buffer."
For example, if your DIME calculation suggests you need $1.2 million, you might consider rounding up to $1.5 million or $2 million. This extra cushion ensures that the "Income Replacement" portion of the policy maintains its value over time. Some modern policies also offer "cost-of-living adjusters" or "guaranteed insurability riders," which allow you to increase your coverage at specific intervals without undergoing a new medical exam. These are highly valuable in an era of fluctuating economic stability.
Special Considerations for Different Life Stages
Your coverage needs are not static; they evolve as you move through different phases of life. A policy that was perfect when you were 25 and single will likely be woefully inadequate when you are 35 with a mortgage and two children.
- Young Singles: Many believe they don't need insurance, but this is the best time to lock in low rates. Coverage should focus on funeral costs and any co-signed debts (like student loans) for which parents might be liable.
- Families with Young Children: This is the period of "peak need." Coverage must be high because the years of dependency are long. Income replacement and education funding are the priorities.
- Empty Nesters: As children become independent and mortgages are paid down, the need for a massive death benefit often decreases. At this stage, insurance might shift toward estate planning or covering potential long-term care costs.
- Stay-at-Home Parents: A common mistake is failing to insure the non-earning spouse. If a stay-at-home parent passes away, the surviving spouse will face massive costs for childcare, household management, and transportation. The economic value of these services must be insured.
Comparing Coverage Needs by Household Type
The following table illustrates how coverage needs might vary based on typical 2026 household profiles. These are estimates intended to show the relationship between life stage and policy size.
| Household Profile | Primary Goal | Recommended Coverage Range | Key Factors |
|---|---|---|---|
| Single Professional | Debt & Funeral | $100,000 – $250,000 | Student loans, co-signed debt, final expenses. |
| Young Couple (No Kids) | Mortgage & Debt | $500,000 – $1,000,000 | Protecting spouse from mortgage burden. |
| Family (2 Kids, 1 Earner) | Total Income Replacement | $1,500,000 – $3,000,000 | 15x income + education + mortgage. |
| Dual Income Family | Supplement Income | $1,000,000 – $2,000,000 | Maintaining standard of living for survivor. |
| Established Empty Nesters | Estate & Final Needs | $250,000 – $750,000 | Burial, taxes, leaving an inheritance. |
The Role of Employer-Provided Insurance
Many people rely solely on the group life insurance provided by their employers. While this is a valuable benefit, it is rarely sufficient. Most employer plans offer a death benefit equal to one or two times your salary. As we have established, this falls far short of the recommended 10 to 15 times income.
Furthermore, group coverage is usually not portable. If you change jobs, get laid off, or leave the workforce due to illness, you often lose your coverage. Relying on an employer policy leaves you vulnerable. It is best to treat employer insurance as a "bonus" and build your primary coverage through a private, individual policy that you own and control.
Common Mistakes in Calculating Coverage
Avoiding pitfalls is just as important as getting the math right. One of the most frequent errors is underestimating the "hidden" costs of death. People often forget to account for the taxes that may be due on certain types of inheritances or the high cost of health insurance for the surviving family members if the primary earner’s job provided those benefits.
Another mistake is failing to account for the "lost opportunity" of the stay-at-home parent. As mentioned earlier, replacing the labor of a caregiver is extremely expensive. In 2026, full-time childcare and household management can easily exceed $40,000 to $60,000 per year.
Finally, many people buy for today instead of tomorrow. They calculate their needs based on their current lifestyle but forget that their expenses will likely grow. A promotion, a move to a bigger house, or the birth of another child can quickly make a policy obsolete. It is often cheaper to buy a larger policy while you are young and healthy than to try to add coverage later.
When to Review Your Coverage
A life insurance policy is not a "set it and forget it" product. To maintain a practical level of coverage, you should review your policy annually or whenever a major life event occurs. The National Association of Insurance Commissioners (NAIC) suggests reviewing your needs during the following events:
- Marriage or Divorce: Changing beneficiaries and adjusting income replacement needs.
- Birth or Adoption: Adding education and childcare costs to the calculation.
- Home Purchase: Ensuring the mortgage can be fully paid off.
- Significant Pay Raise: Adjusting the 10-15x income replacement calculation to reflect a higher standard of living.
- Inheritance or Windfall: You may actually be able to reduce coverage if your personal wealth has increased significantly.
Frequently Asked Questions
Can you have too much life insurance?
While it is technically possible, "over-insuring" is rare because insurance companies have financial underwriting guidelines that prevent individuals from buying policies far exceeding their economic value. However, you can have more than you need, which results in paying unnecessary premiums. If your premiums are preventing you from contributing to retirement accounts or paying down high-interest debt, you should re-evaluate your coverage level.
Does my coverage need to be all in one policy?
No. Many people use a "laddering" strategy. For example, you might have a 30-year term policy for $1 million to cover the mortgage and kids' education, and a smaller 10-year policy for $500,000 to cover the years when your income is at its highest and your expenses are peaked. This can be more cost-effective than one large, long-term policy.
Should I get term or whole life insurance for my coverage?
For the purpose of pure protection and meeting high coverage needs (like the 10-15x income rule), term life insurance is usually the most practical choice. It provides the largest death benefit for the lowest premium. Whole life or permanent insurance is typically reserved for those with specific estate planning needs or those who have already maximized other tax-advantaged investment vehicles.
Is Social Security included in the calculation?
Social Security survivor benefits can provide a meaningful monthly payment to a surviving spouse with young children. You can find your estimated survivor benefits by logging into your account at the Social Security Administration (SSA). While these benefits help, they are rarely enough to cover all expenses, so they should be viewed as a supplement to, rather than a replacement for, private life insurance.
How does my health affect how much coverage I should get?
Your health affects the cost (premium) rather than the amount of coverage you need. However, if you have health issues that make insurance expensive, you may have to prioritize your needs (e.g., covering the mortgage first) to fit the premiums into your budget. If you are in excellent health, you should take advantage of lower rates to buy the full amount recommended by your needs analysis.
Practical Recommendation
To find your ideal coverage amount, start by using the DIME method to establish a baseline. Total your debts, calculate 10 years of income replacement, add the remaining balance of your mortgage, and include projected college costs for all children. Once you have this number, compare it to your current liquid assets and existing insurance. The difference is the amount of new coverage you should seek. In 2026, with the availability of online calculators and digital underwriting, obtaining a quote for a term policy that fits these needs is a straightforward process. Secure your coverage while you are healthy to ensure the most competitive rates and provide your family with lasting financial security.
Image Gallery
Select an image to open it in a new tab.


Akira Tanaka
International Academic Trends Correspondent
