The portion of your paycheck withheld for taxes is determined by your federal income tax bracket, state and local tax requirements, and mandatory payroll contributions like Social Security and Medicare. While most workers see between 20% and 30% of their gross earnings deducted, your specific burden depends on your filing status, total annual income, geographic location, and tax-deferred benefit elections.
The Anatomy of a Paycheck Deduction
When you look at your pay stub, you are seeing a mix of mandatory government levies and optional or employer-sponsored contributions. To determine exactly how much of your check goes to taxes, you must first distinguish between "taxes" (compulsory payments) and "deductions" (benefits or voluntary savings).
Federal, state, and local taxes are generally non-negotiable. They are calculated based on your W-4 form settings and statutory requirements. Payroll taxes, specifically FICA (Federal Insurance Contributions Act), are also fixed percentages set by federal law. Understanding these individual components is the first step toward effective financial planning.
Mandatory Payroll Taxes: FICA
The most consistent deductions from your paycheck are for Social Security and Medicare. These are universal for most U.S. employees and are not influenced by your personal tax bracket or deductions.
- Social Security Tax: As of 2026, the Social Security tax rate for employees is 6.2% of your gross wages. This is applied up to an annual wage base limit, which is adjusted periodically by the Social Security Administration based on national average wage growth. Earnings above this threshold are generally not subject to the 6.2% Social Security tax.
- Medicare Tax: The Medicare tax rate is 1.45% of your total gross wages. Unlike Social Security, there is no wage base limit for the standard Medicare tax. If you are a high earner, you may also be subject to an Additional Medicare Tax of 0.9% on earnings exceeding specific thresholds based on your filing status.
Because these rates are static, they provide a baseline for your "automatic" tax burden. When calculating your total take-home pay, you should always account for this 7.65% (or higher, depending on the Additional Medicare Tax) reduction before considering federal or state income tax.
Federal Income Tax Withholding
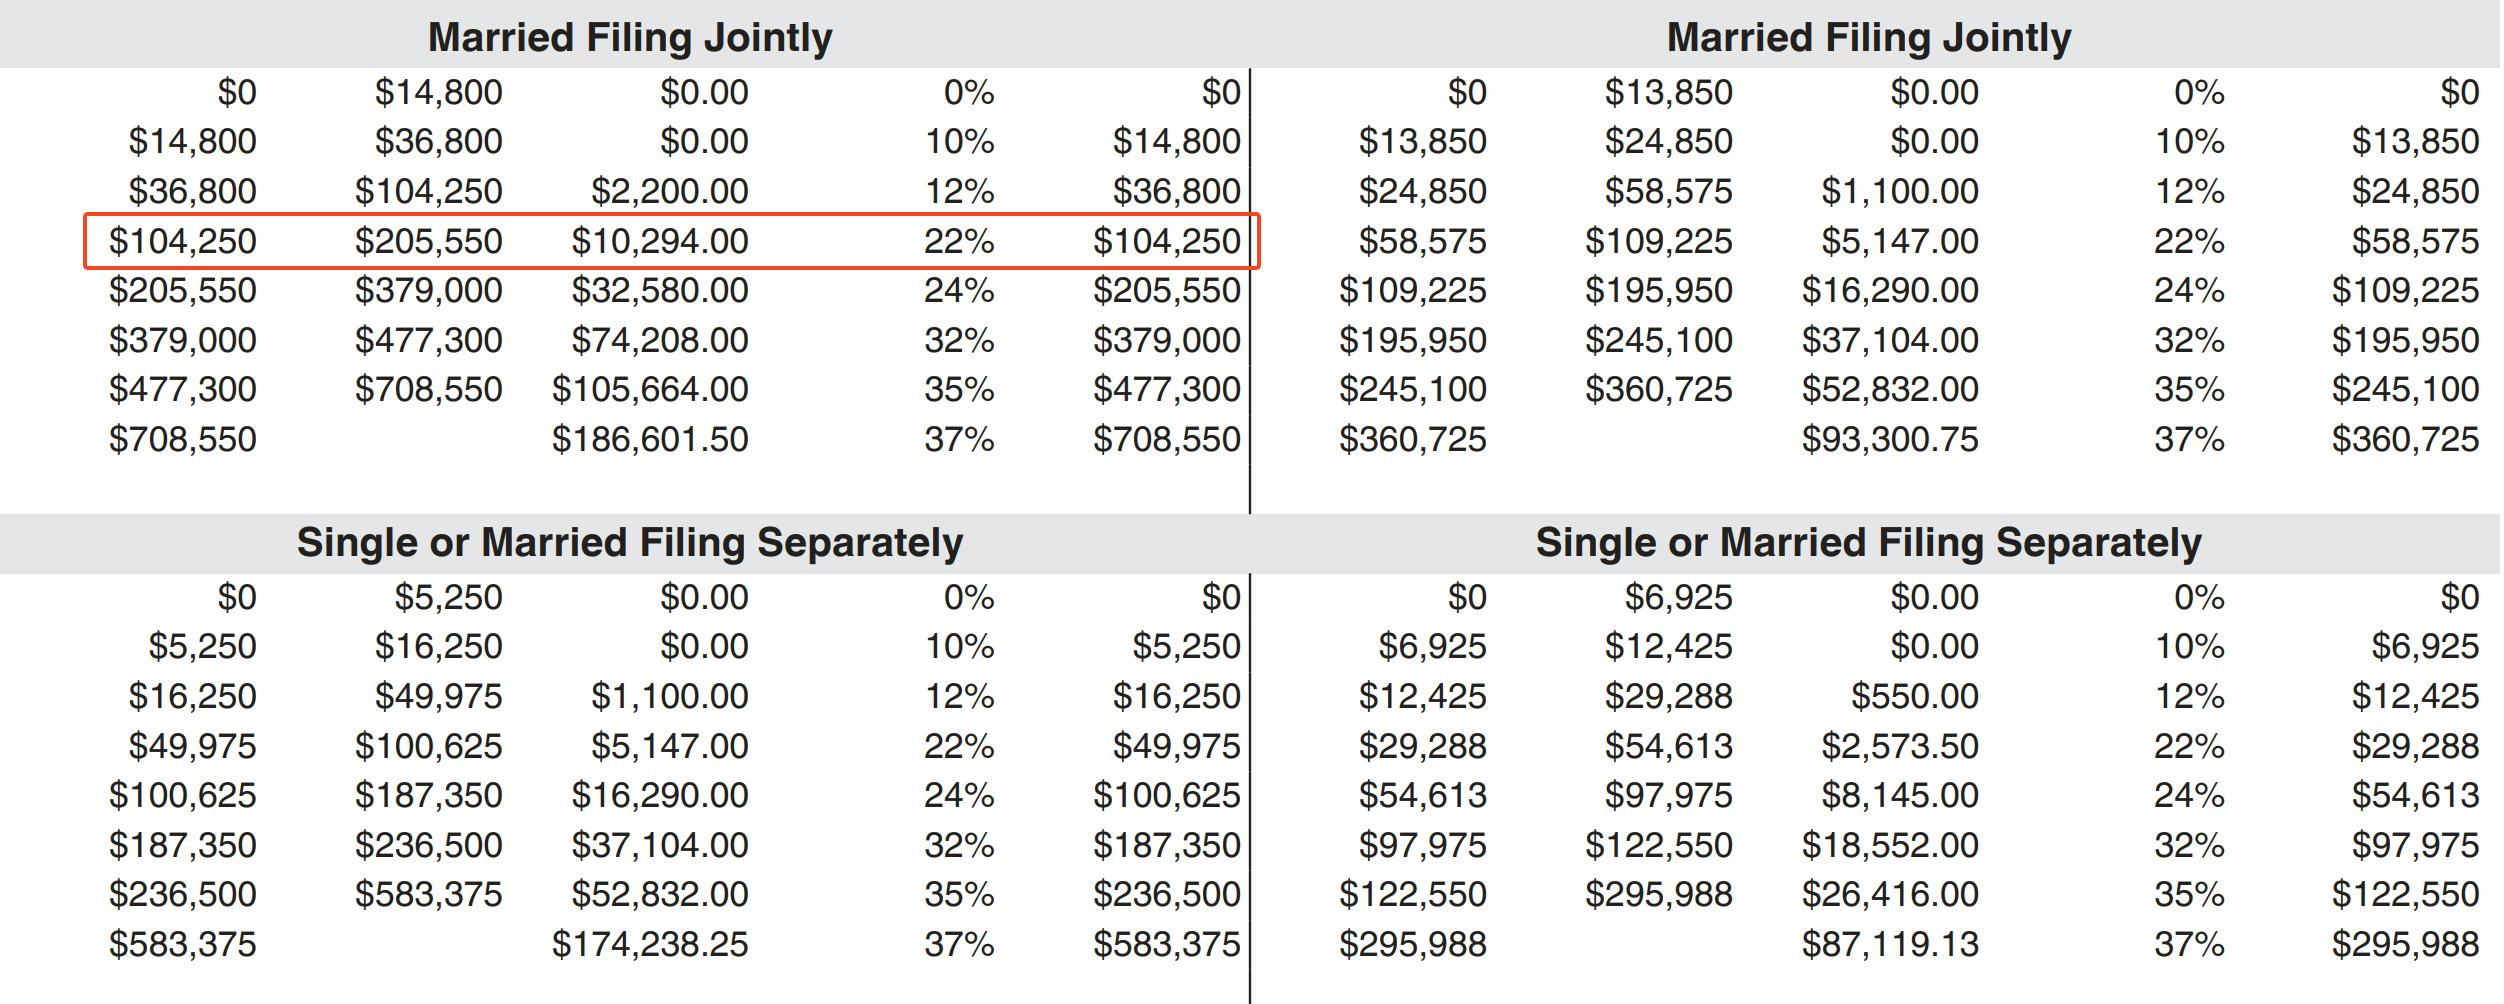
Federal income tax is progressive, meaning your tax rate increases as your income moves into higher brackets. The amount withheld from your paycheck is an estimate of your annual tax liability, calculated based on the information you provided to your employer on your Form W-4.
Your withholding is influenced by:
- Filing Status: Whether you file as Single, Married Filing Jointly, Married Filing Separately, or Head of Household.
- Tax Brackets: The marginal tax rates (currently ranging from 10% to 37% for federal income tax) applied to chunks of your income.
- Adjustments: Credits and deductions you claimed on your W-4, such as the Child Tax Credit or deductions for specific expenses, which reduce the total amount withheld during the year.
If you have too little withheld, you may owe a balance at the end of the year. If you have too much withheld, you essentially provide the government with an interest-free loan, resulting in a tax refund when you file your return.
State and Local Income Taxes
Your residence plays a significant role in your net pay. States use various methods to tax income, which can drastically alter your take-home percentage.
- State Income Tax: Some states, such as Florida, Texas, Nevada, Washington, Wyoming, South Dakota, and Tennessee, do not impose a personal income tax on wages. In these jurisdictions, your net pay is naturally higher. Other states employ flat tax rates, where everyone pays the same percentage regardless of income, while most states use a progressive system similar to the federal government.
- Local Taxes: Some cities, counties, or school districts impose an additional "local" or "occupational" tax. These are often small percentages (e.g., 0.5% to 2%), but they are often overlooked until you see the "City Tax" line item on your pay stub.
Impact of Pre-Tax Deductions
While you cannot change the amount of taxes owed on your salary, you can influence your "taxable gross" through pre-tax deductions. These are contributions taken out of your paycheck before income taxes are calculated, effectively lowering the amount of your pay subject to taxation.
Common pre-tax deductions include:
- 401(k) or 403(b) Retirement Plans: Contributions reduce your current taxable income.
- Health Savings Accounts (HSA): Contributions are tax-deductible, reducing your taxable income.
- Flexible Spending Accounts (FSA): Funds set aside for medical or dependent care expenses reduce your total tax liability.
- Employer-Sponsored Health Insurance Premiums: In most cases, these are deducted pre-tax.
By maximizing these contributions, you lower your taxable gross income, which may keep you in a lower federal or state tax bracket, thereby decreasing the total percentage of your check that goes toward taxes.
Summary of Paycheck Deductions
| Category | Typical Impact | Variability |
|---|---|---|
| Social Security | 6.2% | Fixed (until wage base limit) |
| Medicare | 1.45% | Fixed (plus 0.9% for high earners) |
| Federal Income Tax | 10% – 37% | High (depends on bracket/status) |
| State Income Tax | 0% – 10%+ | High (depends on location) |
| Local/City Tax | 0% – 3% | High (depends on municipality) |
How to Verify Your Withholding
If you want to understand if your employer is withholding the correct amount, start by reviewing your most recent pay stub. Calculate your total taxes paid (Federal + State + FICA) as a percentage of your Gross Pay.
If you feel your withholding is incorrect, use the Tax Withholding Estimator provided on the official Internal Revenue Service (IRS) website. This tool allows you to input your specific salary, current tax filings, and personal situation to determine if you are on track to break even at the end of the tax year. If you find a discrepancy, you can submit a new Form W-4 to your employer’s payroll department to adjust your withholding amount.
Frequently Asked Questions
Why do I pay more in taxes than my coworker who makes the same salary? Your take-home pay is likely different because of non-tax deductions like health insurance premiums, retirement contributions, or different state/local tax jurisdictions if you live in different zip codes. Additionally, different W-4 elections—such as claiming dependents or utilizing different filing statuses—will result in different withholding amounts even with identical gross pay.
What is the difference between my "Gross Pay" and "Net Pay"? Gross pay is the total amount you earn before any deductions are taken out. Net pay, often called your "take-home pay," is the amount remaining after all taxes, benefits, and voluntary deductions have been subtracted. Taxes are calculated against your gross pay, but your final paycheck is the net result.
Does a raise always mean more take-home pay? Generally, yes, but not always by the full amount of the raise. Because the U.S. tax system is progressive, a raise might push you into a higher tax bracket. While only the portion of your income that falls into the higher bracket is taxed at that higher rate, your average tax rate may increase slightly. Additionally, if your raise increases your total annual compensation above certain thresholds, it may trigger higher Medicare tax liabilities.
Can I stop paying income taxes if I change my W-4? No. The W-4 is a tool for your employer to calculate how much to withhold to send to the government on your behalf. It does not determine your actual tax liability. If you instruct your employer to withhold zero taxes, you will still owe those taxes when you file your annual return, and you may face underpayment penalties and interest.
Are there taxes on bonuses or overtime? Yes. Bonuses and overtime are considered supplemental wages by the IRS. Employers typically withhold taxes on these amounts at a flat rate (often 22% for federal withholding) rather than using your standard tax bracket. This can result in a larger-than-expected deduction, but if too much is withheld, the overpayment is returned to you as a refund when you file your annual taxes.
Managing Your Tax Burden
Determining how much of your check goes to taxes is the first step in effective financial management. To optimize your take-home pay, review your pay stub quarterly to ensure your deductions align with your actual expenses and savings goals. If you have significant life changes—such as getting married, having children, or taking on a second job—always update your W-4 immediately to reflect your new tax situation.
Consult with a qualified tax professional or financial advisor if you are dealing with complex income sources, self-employment taxes, or high-earner tax planning. They can provide guidance specific to your jurisdiction and financial profile, ensuring you are meeting your legal obligations while utilizing available tax-advantaged strategies effectively.
Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
