To maintain Personal Injury Protection (PIP) auto insurance, you must select a policy that meets your state's minimum legal requirements, pay your premiums on time to avoid coverage lapses, and ensure your medical provider information is current. In "no-fault" states, maintaining this coverage is a mandatory prerequisite for vehicle registration and legal operation.
Personal Injury Protection, commonly referred to as "no-fault" insurance, is a component of automobile insurance that covers medical expenses, lost wages, and funeral costs for the policyholder and their passengers, regardless of who caused the accident. While the concept seems straightforward, the administrative and legal requirements to maintain this coverage vary significantly across jurisdictions. As we move through 2026, understanding the nuances of PIP maintenance is essential for both financial security and legal compliance.
Understanding the Core Components of PIP Coverage
Before focusing on maintenance, it is vital to understand what exactly you are maintaining. PIP is more comprehensive than standard Medical Payments (MedPay) coverage. While MedPay only covers direct medical bills, PIP is designed to address the broader economic impact of an injury.
Medical Expenses
The primary function of PIP is to pay for "reasonable and necessary" medical treatments. This includes emergency room visits, surgeries, X-rays, dental procedures resulting from the crash, and ongoing rehabilitation. In 2026, many states have refined what constitutes a "necessary" expense, often utilizing fee schedules to cap how much providers can charge.
Work Loss and Disability
If an auto accident prevents you from working, PIP provides a percentage of your lost gross income. This is a critical safety net for individuals who do not have robust short-term disability insurance through their employers. Maintaining PIP ensures that a temporary injury does not lead to a total loss of household income.
Essential Services (Replacement Services)
PIP often covers the cost of hiring someone to perform tasks you can no longer do yourself due to your injuries, such as house cleaning, yard work, or childcare. These are often referred to as "replacement services" and are subject to daily or weekly caps defined in your policy.
Death Benefits and Funeral Expenses
In the tragic event of a fatal accident, PIP provides a set amount for funeral and burial expenses. It may also provide survivor benefits to the dependents of the deceased, helping to bridge the financial gap left by the loss of a breadwinner.
The Legal Necessity of Maintaining PIP in 2026
As of 2026, several states maintain a "no-fault" insurance system. In these states, PIP is not an optional add-on; it is a mandatory requirement. Failure to maintain PIP can result in the suspension of your driver’s license, heavy fines, and the impoundment of your vehicle.
Mandatory PIP States
Currently, states including Florida, Hawaii, Kansas, Kentucky, Massachusetts, Michigan, Minnesota, New Jersey, New York, North Dakota, Pennsylvania, and Utah require some form of PIP or a similar no-fault equivalent. Puerto Rico also operates under a no-fault system.
In these jurisdictions, the "maintenance" of PIP is tied directly to your vehicle's registration. State Departments of Motor Vehicles (DMVs) often receive real-time electronic notifications from insurance carriers. If your PIP coverage drops for even a single day, the state is alerted, which can trigger an immediate suspension of your driving privileges.
Choice No-Fault States
States like Kentucky, New Jersey, and Pennsylvania offer a "choice" system. Residents can choose to operate under a no-fault system (maintaining PIP) or a traditional tort system. Maintaining PIP in these states is a strategic decision that limits your right to sue for non-economic damages (like pain and suffering) unless your injuries exceed a specific "tort threshold."
How to Properly Maintain Your PIP Policy
Maintaining PIP involves more than just paying a monthly bill. It requires active management of your policy limits, coordination with other insurance types, and adherence to state-specific filing deadlines.
1. Verify Your State’s Minimum Limits
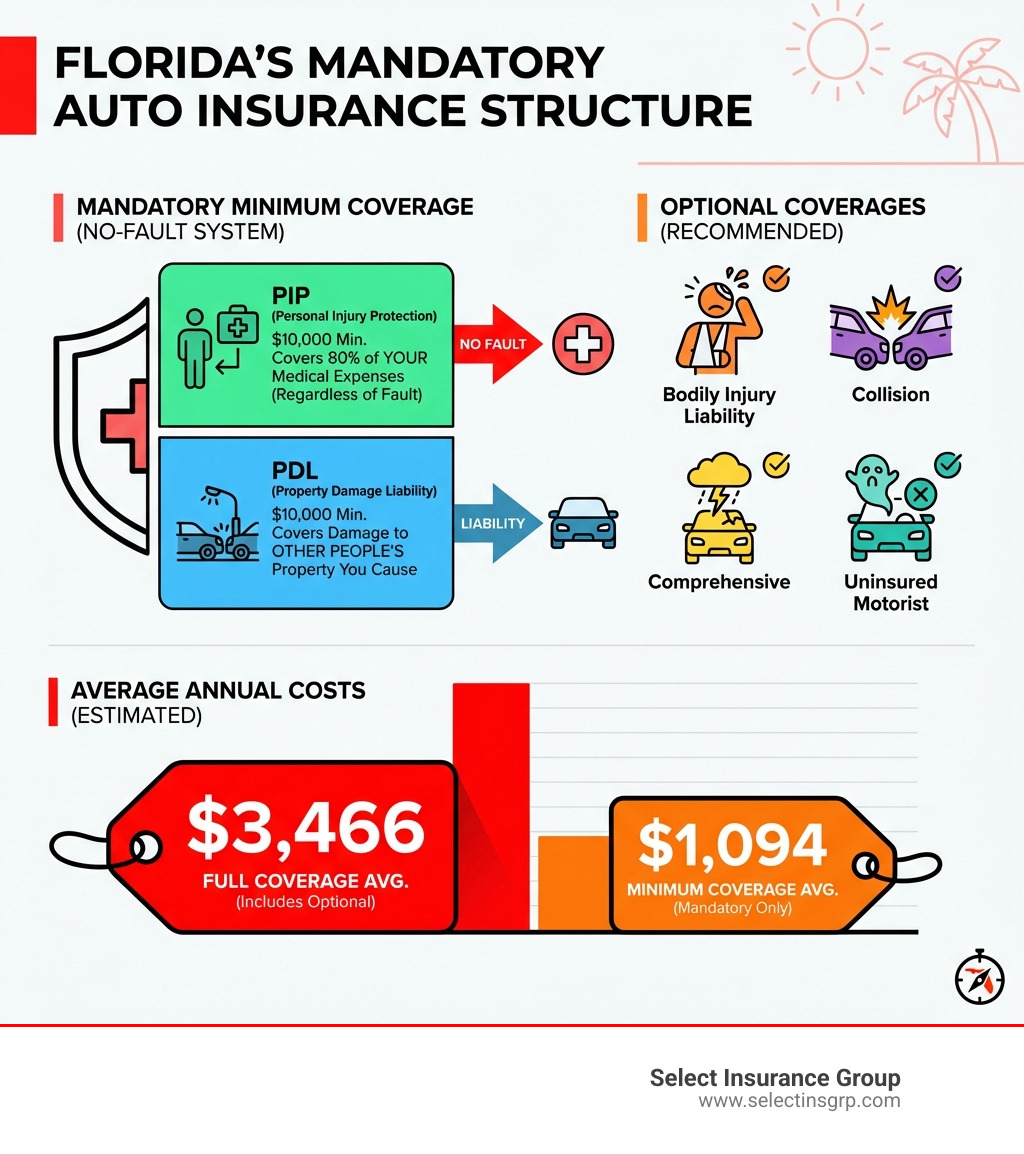
Every no-fault state sets a minimum amount of PIP coverage you must carry. For example, New York typically requires a minimum of $50,000, while other states may require as little as $3,000 or $10,000. To maintain your insurance effectively, you should review these limits annually. Inflation in medical costs often means that a state minimum set several years ago may no longer be sufficient to cover a major trauma in 2026.
2. Manage the "Coordination of Benefits"
One of the most complex aspects of maintaining PIP is how it interacts with your primary health insurance. In states like Michigan, you can choose to "coordinate" your PIP with your health insurance to lower your premium.
- PIP Primary: Your auto insurance pays first.
- Health Primary: Your health insurance pays first, and PIP covers the remaining gaps (like deductibles or services not covered by health insurance).
To maintain this correctly, you must ensure your health insurance policy is "PIP-eligible." Not all ERISA-based employer plans or Medicare/Medicaid plans allow for health-primary coordination. If you lose your health insurance but keep your "coordinated" auto policy, you could face a $500 to $1,000 penalty per claim or a total denial of benefits.
3. Avoid Coverage Lapses
A lapse in coverage occurs if your policy is canceled due to non-payment or if you fail to renew it. Maintaining PIP requires a "no-gap" history. Insurance companies view gaps in coverage as a high-risk indicator, which can lead to significantly higher premiums when you try to reinstate your policy. Setting up automatic payments (EFT) is the most effective way to ensure your PIP remains active.
4. Update Your Household Information
PIP coverage often extends to all members of your household. If a family member moves out, or if a new licensed driver moves in, you must update your policy. Failing to disclose a household resident can be seen as "material misrepresentation," which gives the insurer grounds to void your PIP coverage entirely in the event of a claim.
Comparing PIP to Other Coverage Types
To understand why maintaining PIP is unique, it helps to compare it against other medical-related coverages available in 2026.
| Feature | Personal Injury Protection (PIP) | Medical Payments (MedPay) | Health Insurance |
|---|---|---|---|
| Fault Requirement | None (No-Fault) | None | None |
| Medical Bills | Covered | Covered | Covered |
| Lost Wages | Yes | No | No (Requires Disability Policy) |
| Replacement Services | Yes | No | No |
| Funeral Expenses | Yes | Often Yes | No |
| Mandatory? | Yes (in no-fault states) | No (Optional) | Yes (under federal law) |
| Deductibles | Optional/Varies | Usually None | Usually High |
The Impact of the 14-Day Rule on PIP Maintenance
In some jurisdictions, most notably Florida, maintaining your right to use your PIP benefits depends on a strict "14-day rule." Even if you have been paying for PIP for years, you can lose access to your benefits if you do not seek medical treatment within 14 days of an accident.
To maintain the validity of a PIP claim:
- Seek Initial Care: You must receive an initial medical report from a qualified physician, chiropractor, or hospital within two weeks.
- Emergency Medical Condition (EMC): In specific states, the full PIP limit (e.g., $10,000) is only available if a doctor determines you have an "Emergency Medical Condition." Without this designation, your PIP benefit may be capped at a much lower amount (e.g., $2,500), even if you have maintained the higher limit on your policy.
Financial Strategies for Maintaining PIP Premiums
PIP can be one of the most expensive portions of an auto insurance policy, particularly in states with high medical fraud rates or unlimited benefit structures. To maintain coverage without breaking your budget, consider these strategies:
- Adjust Your Deductible: Most states allow you to apply a deductible to your PIP coverage. Increasing your deductible from $0 to $500 or $1,000 can significantly reduce your premium. However, you must ensure you have the savings to cover that deductible if an accident occurs.
- Utilize Work-Loss Waivers: If you are retired or do not have earned income, some states allow you to "waive" the lost-wage portion of PIP. This maintains your medical coverage while stripping away the parts you don't need, lowering the cost.
- Telematics and Usage-Based Insurance: Many insurers in 2026 offer discounts for safe driving tracked via smartphone apps. Maintaining a high safety score can lead to credits that offset the cost of mandatory PIP.
Common Obstacles to Maintaining PIP Coverage
Maintaining coverage is not always a smooth process. Several external factors can jeopardize your standing.
Insurer Insolvency
While rare, if your insurance carrier becomes insolvent, your PIP coverage could be at risk. Most states have an Insurance Guaranty Association that steps in to cover claims, but there may be delays and lower limits. To maintain reliable PIP, always choose carriers with an "A" rating or better from agencies like A.M. Best.
Fraud Investigations
PIP fraud is a significant issue. If your insurer suspects "staged accidents" or "clinic-padding" (where doctors overbill for simple treatments), they may suspend your benefits during an investigation. Maintaining your coverage in this scenario requires meticulous record-keeping. Always keep a diary of your symptoms and copies of all medical referrals.
Policy Non-Renewal
Insurers may choose not to renew your policy if you have too many at-fault accidents or if the state's regulatory environment becomes too costly for them. If you receive a non-renewal notice, you must secure new PIP coverage before the old policy expires to maintain continuous coverage and avoid state penalties.
FAQs About PIP Maintenance
Does PIP cover me if I am a pedestrian?
Yes, in most no-fault states, if you are struck by a motor vehicle while walking or cycling, your own PIP insurance will cover your medical bills. If you do not own a car or have PIP, the PIP of the vehicle that hit you usually provides coverage. Maintaining your own policy ensures you are protected regardless of the other party's insurance status.
What happens to my PIP if I drive into a state that doesn't have no-fault laws?
Most high-quality auto insurance policies include an "Out-of-State Coverage" clause. This clause automatically adjusts your policy to meet the minimum requirements of the state you are driving in. However, your PIP benefits usually follow you, meaning you would still have access to medical and wage-loss benefits even if the accident happens in a "tort" state.
Can I cancel PIP if I have excellent health insurance?
If you live in a mandatory PIP state, the answer is no. You cannot opt-out of PIP based on having other health insurance. You may be able to coordinate the two to reduce costs, but you must still maintain the PIP portion of your auto policy to keep your vehicle legally registered.
How does the "Michigan Reform" affect PIP maintenance in 2026?
Michigan moved away from a mandatory "unlimited" PIP system in 2020. In 2026, drivers can choose between different levels of coverage (Unlimited, $500,000, $250,000, or even an opt-out for those on Medicare). Maintaining PIP in Michigan now requires an active choice during every renewal period; if you do not make a selection, the insurer may default you to the most expensive "unlimited" option.
Is PIP the same as Liability insurance?
No. Liability insurance pays for the other person's injuries and property damage when you are at fault. PIP pays for your injuries regardless of fault. You must maintain both to be fully protected and legally compliant in most states.
Will my PIP premiums go up if I use the coverage?
In many no-fault states, insurers are prohibited from raising your rates for a PIP claim if you were not at fault for the accident. However, the laws vary by state. It is important to review your state's "surcharge" rules to understand how a PIP claim might affect your long-term maintenance costs.
Final Recommendations for Policyholders
To maintain PIP auto insurance effectively in 2026, you should treat it as a dynamic part of your financial plan rather than a "set it and forget it" expense.
- Conduct an Annual Audit: Every year, compare your PIP limits against your current health insurance coverage and your annual salary. If your salary has increased, your PIP "work loss" limit may need to be raised to provide adequate protection.
- Prioritize Continuous Coverage: Never allow your policy to lapse. The cost of a "high-risk" policy following a lapse is almost always higher than the cost of maintaining a standard policy.
- Consult an Independent Agent: Because PIP laws are subject to legislative changes, working with an agent who understands the specific statutes of your state is invaluable. They can help you navigate coordination of benefits and ensure you aren't paying for redundant coverage.
By staying proactive and informed, you can ensure that your PIP coverage remains a robust shield against the financial devastation that often follows an automobile accident.
Image Gallery
Select an image to open it in a new tab.
Zara El-Hashem
Sociocultural Dynamics and Academics Writer
