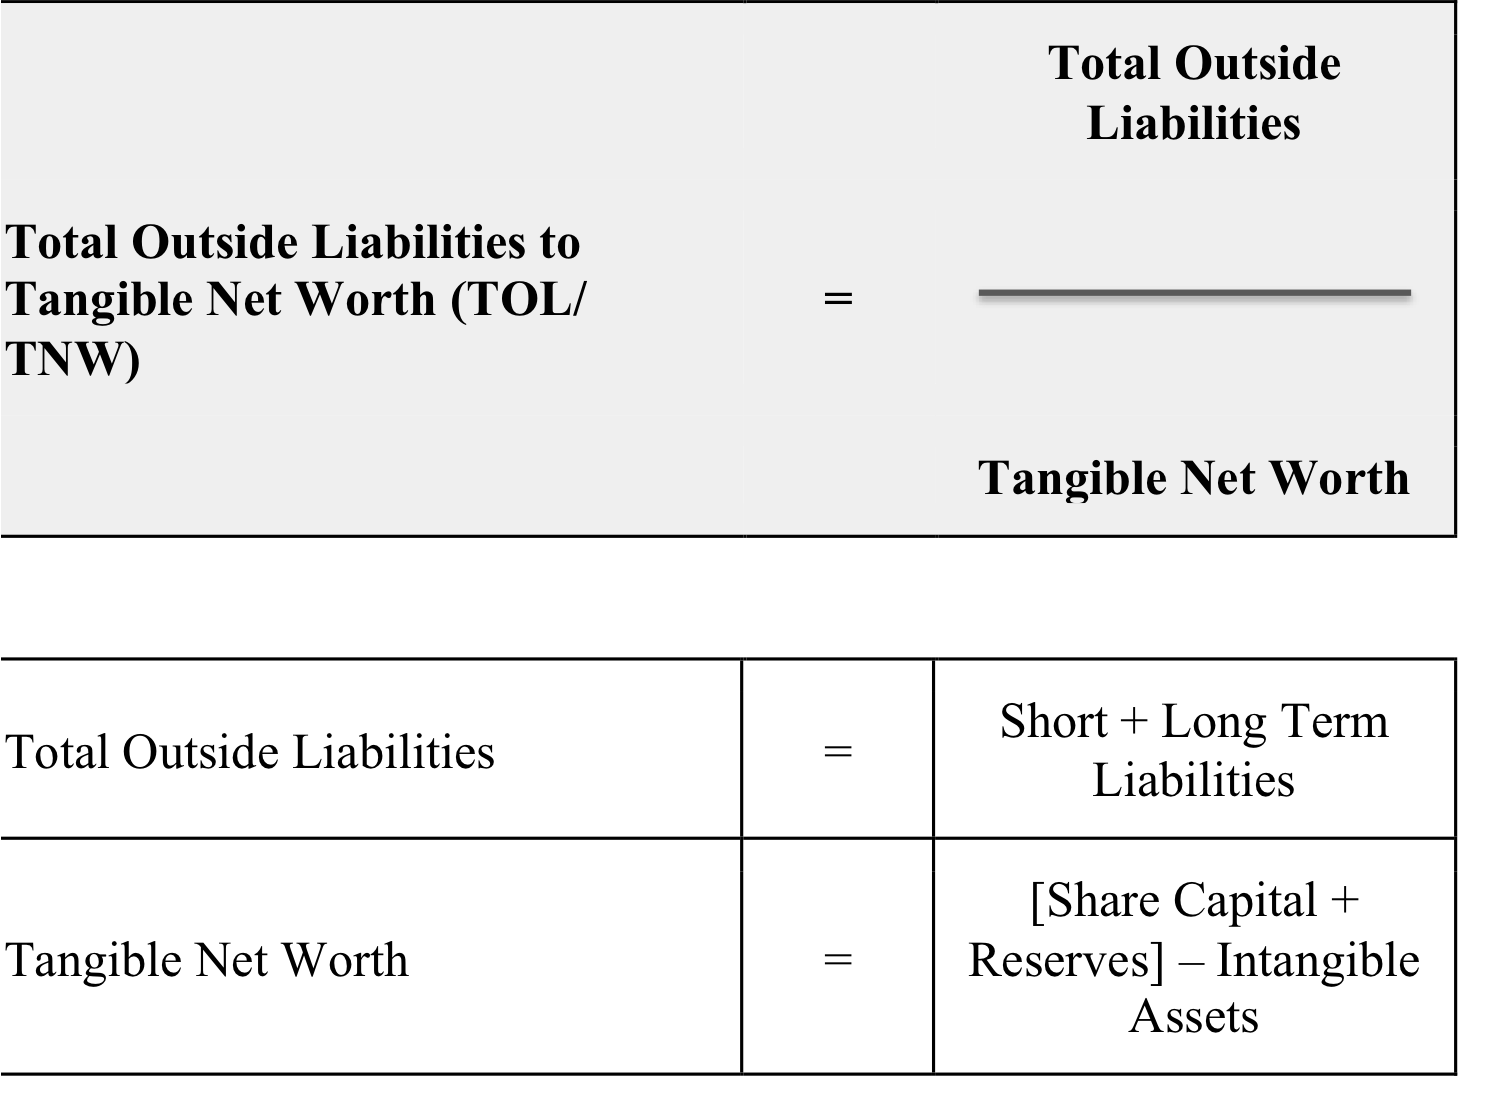
To complete the total liabilities and net worth sections of a personal financial statement (PFS), you must aggregate all outstanding debts—including mortgages, loans, and credit card balances—to calculate total liabilities. Subtracting this total from your total assets yields your net worth, representing your actual equity and financial solvency.
A personal financial statement is a critical document used by lenders, investors, and regulatory bodies to assess an individual's financial health. While the "Assets" column represents what you own, the "Liabilities" and "Net Worth" sections represent what you owe and your ultimate financial value, respectively. As of 2026, standardized forms like the SBA Form 413 or bank-specific templates remain the primary vehicles for this disclosure, particularly for those seeking business financing or high-value personal loans.
Understanding the Structure of Liabilities
Before attempting to fill out the form, it is essential to distinguish between the various types of debts you may carry. In the context of a personal financial statement, liabilities are generally categorized by their urgency and the nature of the collateral securing them.
Current vs. Long-Term Liabilities
While many simplified personal financial statements group all debts together, more sophisticated versions or those required for corporate guarantees may separate current liabilities (debts due within one year) from long-term liabilities.
- Current Liabilities: These include credit card balances, short-term personal loans, and any portion of a long-term debt that is due within the next 12 months.
- Long-Term Liabilities: These typically include the remaining principal on mortgages, student loans, and vehicle loans that extend beyond the current year.
Secured vs. Unsecured Debt
Lenders pay close attention to whether your liabilities are secured by assets. A mortgage is secured by real estate; if you fail to pay, the lender takes the property. In contrast, credit card debt is usually unsecured. Understanding this distinction helps you accurately complete the "Description of Assets" section that often corresponds to specific liability entries.
Step-by-Step Breakdown of the Liabilities Section
Completing the liabilities section requires precision. Estimating these numbers can lead to discrepancies that may jeopardize a loan application or a legal filing. Gather your most recent statements from the first quarter of 2026 to ensure the figures reflect your current standing.
1. Accounts Payable
This line item is often misunderstood. In a personal context, accounts payable refers to money you owe to others for goods or services already received.
- Credit Card Balances: This is the most common entry here. List the total balance across all cards as of the statement date.
- Personal Bills: If you have outstanding medical bills, utility arrears, or money owed to a vendor for a home renovation, they belong here.
2. Notes Payable to Banks and Others
This section covers formal loan agreements that are not secured by real estate. You should list the name of the creditor and the current principal balance.
- Installment Loans: Include auto loans, boat loans, or recreational vehicle financing.
- Personal Lines of Credit: If you have drawn down a personal line of credit (not a HELOC), the outstanding balance must be reported.
- Student Loans: These are often listed here or in a dedicated "Other Liabilities" section. Ensure you include the total payoff amount, not just the annual payment.
3. Mortgages on Real Estate
For many individuals, this is the largest liability. You must list the outstanding principal balance for every property you own.
- Primary Residence: List the first mortgage and any second mortgage or Home Equity Line of Credit (HELOC) balance.
- Investment Property: If you own rental properties, the debt associated with them must be listed separately to correspond with the real estate assets listed in the first half of the statement.
4. Unpaid Taxes
Tax liabilities are high-priority debts. If you owe the IRS, state, or local tax authorities, these must be disclosed. This includes:
- Income Tax: Any back taxes or current year estimates that are due but unpaid.
- Property Tax: If your property taxes are not escrowed in your mortgage and are currently due, they must be recorded.
5. Other Liabilities
This is a catch-all category for debts that do not fit the traditional definitions above. Common examples in 2026 include:
- Alimony and Child Support: Future legal obligations are generally not listed as a lump-sum liability, but any past-due amounts (arrearages) must be included.
- Legal Judgments: If a court has ordered you to pay a specific amount, it is a liability until satisfied.
- Private Debts: Money borrowed from family or friends that is subject to a repayment agreement.

Dealing with Contingent Liabilities
Contingent liabilities are debts that you might have to pay in the future, depending on the outcome of a specific event. While they do not always count toward your primary "Total Liabilities" figure for the purpose of the net worth calculation, they must be disclosed in the footnotes or a dedicated sub-section.
- Co-signed Loans: If you co-signed a car loan for a family member, you are legally responsible if they default. Lenders view this as a potential drain on your future cash flow.
- Guarantees: If you are a business owner and have personally guaranteed a corporate lease or loan, this is a contingent liability.
- Pending Lawsuits: If you are currently a defendant in a civil suit, the potential settlement or judgment amount should be noted.
Calculating Total Liabilities
Once every debt has been categorized and verified against a statement, sum them to reach your Total Liabilities.
| Liability Category | What to Include | Valuation Method |
|---|---|---|
| Accounts Payable | Credit cards, medical bills, trade debt | Current balance on statement |
| Notes Payable | Auto loans, personal loans, student debt | Principal payoff amount |
| Real Estate Mortgages | Primary home, rentals, HELOCs | Remaining principal balance |
| Unpaid Taxes | Federal, state, local, property taxes | Actual amount owed to government |
| Other Liabilities | Private loans, judgments, arrearages | Documented debt amount |
Calculating and Interpreting Net Worth
The final step of the personal financial statement is the calculation of net worth. This is the "bottom line" that tells a lender how much of your asset base you actually own outright.
The Net Worth Formula
The math is straightforward: Total Assets - Total Liabilities = Net Worth
If your assets exceed your liabilities, you have a positive net worth. If your liabilities exceed your assets—often seen with recent graduates with high student debt or homeowners in a localized housing market downturn—you have a negative net worth.
Why Net Worth Matters in 2026
In the current economic landscape of 2026, net worth is used as a proxy for financial resilience. A high net worth suggests that you have a "cushion" to absorb economic shocks or business losses. For SBA 7(a) or 504 loans, your net worth helps determine your eligibility and the level of collateral required.
Lenders also look at the composition of net worth. If your net worth is entirely tied up in "soft assets" like a privately held business valuation or personal property (jewelry, art), it is viewed as less stable than a net worth comprised of liquid cash, marketable securities, and real estate equity.
Common Mistakes to Avoid
Errors in the liabilities and net worth sections can lead to accusations of fraud or simply result in a denied application.
- Omitting "Invisible" Debts: Many people forget to include 401(k) loans. While you are technically borrowing from yourself, the loan is a liability that must be repaid to the plan, and it reduces your effective asset base.
- Using Monthly Payments Instead of Principal: Never list your $1,500 monthly mortgage payment in the liabilities section. You must list the full $285,000 (or whatever the principal balance may be) that remains on the loan.
- Double-Counting: Ensure you do not list the same debt twice. For example, if you list a mortgage under "Notes Payable," do not list it again under "Real Estate Mortgages."
- Inconsistent Asset Valuation: If you list a home as an asset worth $500,000 but the associated mortgage is $550,000, your net worth will correctly reflect $50,000 of negative equity. Trying to "pad" the asset value to avoid showing negative equity is a red flag for auditors.
Professional Advice and Verification
For simple personal use, a self-prepared statement is usually sufficient. However, for complex estates or high-value business transactions, involving a Certified Public Accountant (CPA) is recommended. A CPA can provide a Compiled, Reviewed, or Audited financial statement.
- A Compiled statement is based on your provided data without verification.
- A Reviewed statement involves some analytical procedures to ensure the numbers make sense.
- An Audited statement is the gold standard, where the accountant verifies balances directly with banks and creditors.
FAQ
Should I include my spouse’s debt on my personal financial statement?
If you are filing a joint financial statement, you must include all debts held by both spouses. If you are filing an individual statement, you generally only include debts for which you are legally responsible (individual debts and your portion of joint debts). However, in community property states, the rules may require a more comprehensive disclosure of marital debt.
How do I value a debt if the interest is deferred?
Regardless of interest terms, the liability is the current principal amount you would need to pay to satisfy the debt today. For student loans in deferment or 0% APR furniture loans, the total principal remains a liability that must be recorded.
What if my net worth is negative?
A negative net worth does not automatically disqualify you from all financial activities, but it does change the risk profile. You should be prepared to explain the circumstances—such as high investment in education or a recent major purchase—to any lender or interested party. Providing a narrative "Statement of Financial Position" can help contextualize a negative net worth.
Do I need to list my monthly living expenses as liabilities?
No. Standard living expenses like rent, groceries, and insurance premiums are cash flow items, not liabilities. A liability is a debt obligation. However, if you are behind on those payments and owe back-rent or overdue premiums, those arrears become liabilities that must be listed under "Accounts Payable."
How often should I update the total liabilities and net worth sections?
For active investors or business owners, updating the PFS quarterly is a best practice. Most lenders require a statement that is no more than 90 days old at the time of a loan application. Significant changes, such as selling a property or taking on a new major loan, should trigger an immediate update.
Final Recommendation
When completing the total liabilities and net worth sections, prioritize transparency and documentation. Every figure entered into the liability column should correspond to a physical or digital statement you have on file. Once you have calculated your net worth, review it against your financial goals. If the number is lower than expected, focus on a "debt snowball" or "debt avalanche" strategy to reduce liabilities, which directly increases your net worth even if your assets remain stagnant.
Image Gallery
Select an image to open it in a new tab.
Declan O'Connor
Higher Education and Campus Culture Reporter
