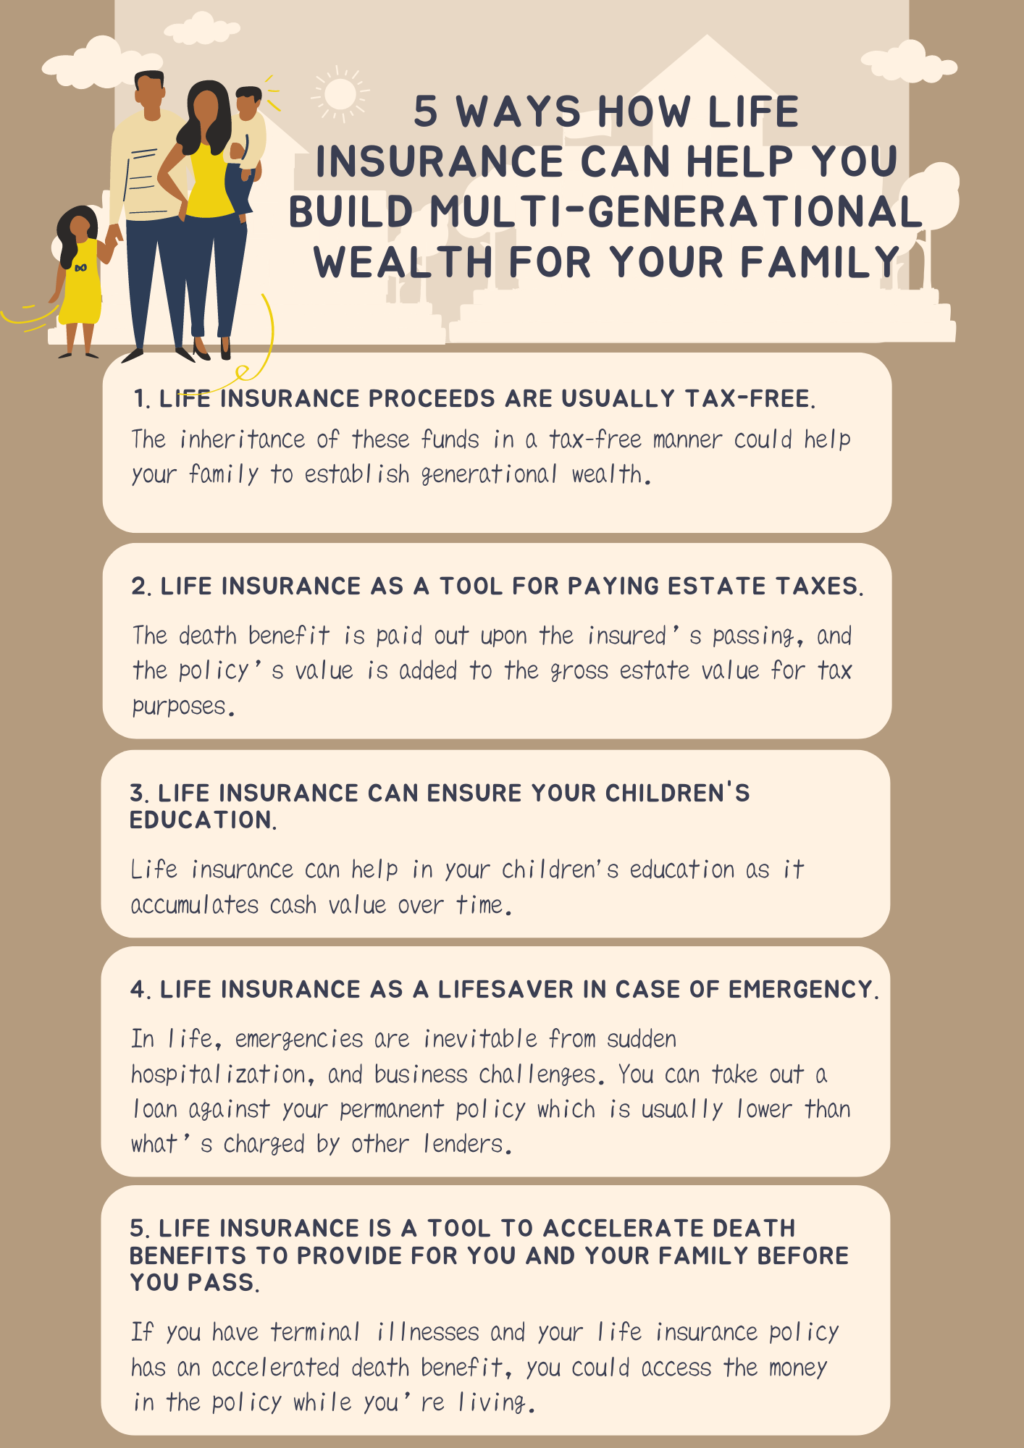
Integrating life insurance into your 2026 financial roadmap offers a dual advantage: securing your family’s future while optimizing your tax liability through government-sanctioned deductions and tax-deferred growth. By leveraging specific policy structures and contribution limits, you can effectively lower your taxable income, minimize capital gains exposure, and ensure long-term wealth transfer efficiency within the current fiscal landscape.
The Strategic Value of Insurance-Based Tax Planning
In 2026, the intersection of rising inflation and evolving tax brackets makes wealth preservation more complex. Many taxpayers focus exclusively on retirement accounts like 401(k)s or IRAs, often overlooking how life insurance—specifically permanent life insurance—acts as a sophisticated financial instrument. It is not merely a death benefit; it is a vehicle that, when managed correctly, provides tax-free liquidity, estate tax mitigation, and a hedge against future tax rate volatility.
By embedding life insurance into your 2026 strategy, you transition from reactive tax filing to proactive wealth management. This approach requires understanding that specific policy types offer different tax treatments under current regulatory guidelines.
1. Leveraging Premium Deductibility for Business Owners
For sole proprietors and business owners, life insurance premiums may be tax-deductible if the policy is structured as an employee benefit (e.g., Section 162 Executive Bonus Plan). By paying the premiums as part of an executive compensation package, the business deducts the expense, while the owner or employee receives the benefit of life insurance coverage. This strategy allows for shifting funds from the business to the individual in a tax-advantaged manner, provided it meets the "reasonable compensation" test under tax codes.
2. Tax-Deferred Cash Value Growth
Permanent life insurance policies, such as Whole Life or Universal Life, accumulate cash value over time. Unlike a brokerage account where you must pay taxes on dividends or capital gains annually, the growth within a life insurance policy is tax-deferred. This allows the internal rate of return to compound without the friction of annual tax payments, leaving more capital in the account to grow over the decades.
3. Tax-Free Policy Loans for Supplemental Income
One of the most powerful tools in a financial planner's arsenal is the ability to borrow against the cash value of a permanent policy. These loans are generally not considered taxable income, provided the policy remains in force. As you move through 2026 and beyond, you can access these funds to supplement your retirement income, bridge gaps between business cycles, or fund major expenses without triggering the tax consequences associated with selling appreciated assets.
4. Avoiding Income Tax on the Death Benefit
The death benefit paid to your beneficiaries is almost universally income-tax-free under current laws. This provides a significant tax-efficient transfer of wealth to your heirs. While life insurance proceeds may be subject to estate taxes if your total net worth exceeds the federal lifetime gift and estate tax exemption, proper structuring—such as using an Irrevocable Life Insurance Trust (ILIT)—can shield these proceeds from the gross estate, ensuring your beneficiaries receive the full amount.
5. Strategic Gifting through ILITs
An Irrevocable Life Insurance Trust (ILIT) is a legal arrangement designed to hold a life insurance policy outside of your taxable estate. By transferring the policy into an ILIT, you can leverage your annual gift tax exclusion to fund the premiums. This effectively reduces the size of your taxable estate in 2026, while providing a substantial, non-taxable liquidity source for your heirs to pay estate taxes or other settlement costs upon your death.
6. Using Life Insurance to Cover Estate Tax Liabilities
If your estate is projected to exceed the 2026 federal exemption threshold, your heirs may face a substantial tax bill, potentially forcing them to liquidate family assets like real estate or businesses to pay the IRS. Life insurance provides the necessary liquidity at the exact time it is needed. By coordinating the size of your policy with a professional appraisal of your estate’s tax liability, you ensure that your legacy remains intact without forcing an "asset fire sale."
7. Converting Taxable Assets to Tax-Free Death Benefits
If you hold a significant amount of assets in taxable accounts, consider the strategy of repositioning a portion of those funds into a single-premium or limited-pay permanent life insurance policy. By moving money from a high-tax environment (where gains are taxed at ordinary or capital gains rates) to a tax-exempt death benefit structure, you increase the net value of your estate, effectively "buying" a tax-free future for your beneficiaries.
8. Accelerated Death Benefits for Chronic Illness
Many modern life insurance policies now include riders that allow you to access a portion of the death benefit while you are still alive if you are diagnosed with a terminal or chronic illness. These "living benefits" are generally tax-free under current tax laws. This provides a critical financial safety net, ensuring you do not have to deplete your taxable investment accounts to pay for long-term care or medical expenses.
9. Efficient Education Funding
While 529 plans are the standard for college savings, permanent life insurance can act as a secondary vehicle. Because the cash value grows tax-deferred and can be accessed via tax-free loans, it provides a flexible reserve. If your child doesn't use the funds for education, the money remains in your policy for retirement or estate planning, avoiding the penalties associated with withdrawing non-qualified funds from a 529 account.
10. Hedging Against Future Tax Rate Increases
Many financial experts note that current federal tax rates are historically low. By placing assets into a life insurance policy, you are effectively "locking in" current tax-free status for those funds. Regardless of what happens to income tax rates in 2027 or beyond, the proceeds and cash value growth within your policy remain shielded, providing a hedge against the uncertainty of future fiscal policy changes.
11. Diversification of Tax Assets
A robust 2026 financial plan should include a mix of taxable (brokerage), tax-deferred (401k/IRA), and tax-free (Roth/Life Insurance) assets. Relying too heavily on tax-deferred accounts can create a "tax time bomb" when you begin taking Required Minimum Distributions (RMDs) later in life. Integrating life insurance into your portfolio balances your tax exposure, giving you the flexibility to choose which "bucket" to draw from based on the tax environment at the time.
12. Protecting Business Continuity
For business partners, a "buy-sell agreement" funded by life insurance is essential. If a partner passes away, the policy provides the cash necessary for the surviving partner to buy out the deceased partner's share. This is structured as a tax-efficient transition. Without the policy, the surviving partner might be forced to take on heavy debt, or the deceased's family might be forced to sell the business interest to a third party, creating significant tax complications for all involved.
Comparative Overview: Tax-Saving Vehicles
| Strategy | Primary Tax Benefit | Best For |
|---|---|---|
| Traditional IRA | Up-front deduction | Lowering current income |
| Roth IRA | Tax-free growth | Younger savers / long-term |
| Permanent Life Insurance | Tax-free death benefit / Loans | Estate planning / Liquidity |
| ILIT | Estate tax exclusion | High-net-worth individuals |
Frequently Asked Questions
Are life insurance loans always tax-free? Yes, generally, as long as the policy is not a Modified Endowment Contract (MEC) and remains in force. If a policy lapses while a loan is outstanding, the IRS may treat the forgiven loan as taxable income.
What is a Modified Endowment Contract (MEC)? An MEC is a life insurance policy that has been "overfunded" according to IRS limits. If a policy is classified as an MEC, withdrawals and loans are taxed on a LIFO (Last-In, First-Out) basis, meaning earnings are taxed before the principal.
How does an ILIT help with 2026 estate taxes? An ILIT removes the life insurance death benefit from your taxable estate, preventing it from increasing your potential estate tax liability while providing cash to heirs to pay any existing estate taxes.
Can I use life insurance for long-term care? Yes, many policies in 2026 offer Long-Term Care (LTC) riders. These allow you to accelerate a portion of your death benefit to pay for qualified long-term care costs on a tax-favored basis.
Do I need professional advice to set this up? Yes. Tax laws involving life insurance are complex and subject to jurisdictional changes. You should work with a fee-only financial advisor and a tax attorney to ensure your policy structure aligns with your specific estate and tax goals.
Next Steps
The best way to begin is to request an "in-force illustration" from your current life insurance carrier if you already hold a policy, or to conduct a "gap analysis" with a fiduciary financial advisor. Ensure your goals for 2026 prioritize liquidity and tax-efficiency, and verify that your beneficiaries and trust documents are current.
Image Gallery
Select an image to open it in a new tab.
Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
