Metropolitan Life Insurance Company: A Historical Overview and Current Status

Metropolitan Life Insurance Company, widely recognized today as MetLife, Inc., stands as one of the most significant pillars of the American financial services sector. Established in the 19th century, the company transitioned from a modest provider of industrial insurance to a global insurance and employee benefits powerhouse. In 2026, the organization operates as a publicly traded holding company providing life insurance, annuities, and group benefit programs to millions of customers worldwide.
Origins and Historical Evolution
The roots of the Metropolitan Life Insurance Company trace back to the aftermath of the American Civil War. Founded in 1868, the company was originally named the National Union Life and Limb Insurance Company, headquartered in New York City. The organization was formed specifically to provide insurance for soldiers and sailors disabled during the conflict, though it quickly realized that the market for such specialized coverage was inherently limited.
In 1868, the company reorganized and adopted the name Metropolitan Life Insurance Company. During its formative years, it followed the lead of British insurance societies by entering the "industrial insurance" market. This sector was designed for working-class individuals who could afford only small, frequent premium payments, often collected weekly by agents visiting homes. This door-to-door agency model was the defining operational characteristic of the firm for decades, embedding "Met Life" into the cultural fabric of American urban neighborhoods.
The Rise of the Metropolitan Life Tower
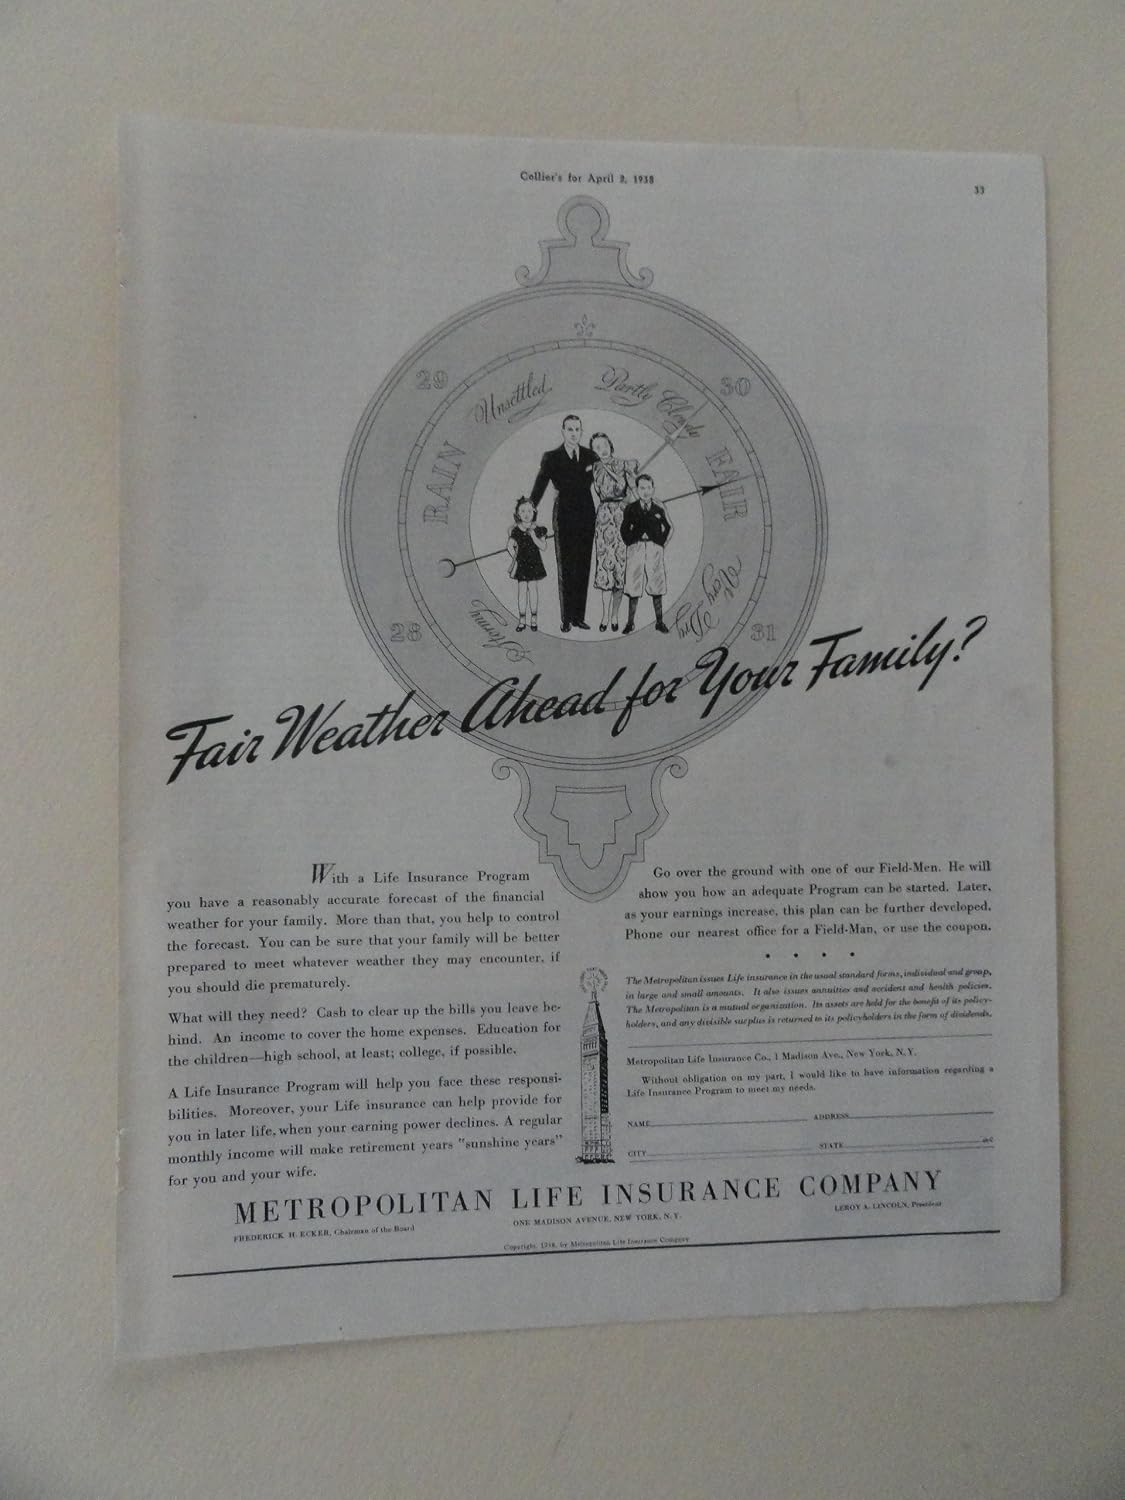
By the turn of the 20th century, the company’s success allowed it to undertake ambitious architectural projects that signaled its financial stability. The most iconic of these was the Metropolitan Life Tower, completed in 1909. Situated at Madison Square in New York City, the tower stood as the tallest building in the world until 1913. The building served as a literal landmark of the company's dominance, and the company's "Light That Never Fails" motto became a well-known slogan associated with its commitment to policyholders.
Mid-Century Expansion and Strategic Shifts
Throughout the 20th century, Metropolitan Life underwent significant structural transformations. It moved away from the industrial insurance model as middle-class wealth expanded and consumer preferences shifted toward group life insurance and long-term investment vehicles. The company became a major provider of life insurance for large corporations, effectively capturing the shift toward employer-sponsored benefits that defined the post-World War II economy.
A defining moment in the company’s history occurred in the year 2000, when Metropolitan Life Insurance Company officially demutualized. As a mutual company, it had been owned by its policyholders. Upon demutualization, the firm became a publicly traded company under the name MetLife, Inc., allowing it to raise capital more easily and pursue global acquisitions. This transition marked the end of the traditional "Metropolitan Life" era and the beginning of its existence as a diversified financial services conglomerate.
MetLife in 2026: Current Organizational Status
As of 2026, MetLife, Inc. operates as a global leader in the insurance and financial services industry. While the legal entity known as Metropolitan Life Insurance Company remains the primary insurance subsidiary, it functions under the umbrella of a much larger, internationally diversified corporation. The brand has evolved significantly from its early days of selling weekly burial policies to offering complex wealth management and insurance products.
Core Business Operations
The company’s operations in 2026 are categorized into several primary segments:
- Group Benefits: This remains a cornerstone of the business, providing life, dental, vision, and disability insurance to employees of corporate clients and government entities.
- Retirement and Income Solutions: The company manages a vast portfolio of annuities and retirement plans, assisting individuals and institutions in navigating long-term financial stability.
- Individual Insurance: MetLife continues to offer term and whole life insurance policies to individual consumers, though these products are now sold through sophisticated digital platforms and independent brokers rather than the traditional door-to-door agent model.
- Global Operations: Unlike its early history, which was localized to the United States, MetLife now maintains significant market shares in Asia, Latin America, and Europe.
Financial Standing and Regulatory Oversight
As a major financial institution, the company is subject to rigorous regulatory standards. In the United States, the primary insurance subsidiaries are regulated by state departments of insurance. At the holding company level, MetLife must comply with SEC regulations regarding public financial disclosures. By 2026, the company continues to maintain robust capital reserves, a requirement for any major life insurer to ensure it can meet its long-term death benefit obligations to policyholders.

Comparison of Historical and Modern Service Models
The shift from the 19th-century "industrial" model to the 21st-century digital-first approach reflects broader trends in the insurance industry. The following table contrasts these operational paradigms.
| Feature | 19th/Early 20th Century Model | 2026 Modern Model |
|---|---|---|
| Sales Channel | Door-to-door agents | Digital portals, independent brokers, HR portals |
| Primary Product | Industrial (weekly) life insurance | Group benefits, annuities, life insurance |
| Corporate Structure | Mutual (owned by policyholders) | Publicly traded (MetLife, Inc.) |
| Customer Interaction | In-person, cash-based | Automated, electronic, digital self-service |
| Geographic Scope | Primarily local/regional | Global operations across 40+ markets |
Navigating Legacy Policies and Claims
One of the most frequent questions regarding the "old" Metropolitan Life Insurance Company involves the status of legacy policies. If a family member holds a paper policy issued decades ago, it is essential to understand that these contracts remain legally binding. The merger, acquisition, and demutualization processes that formed MetLife, Inc. did not absolve the company of its obligations to pay valid claims on older policies.
Steps to Verify and Claim
If you are managing the estate of a relative or attempting to locate a long-lost policy:
- Locate Documentation: Search for physical certificates, premium receipt books, or old correspondence. Even if the document is faded or seemingly outdated, it may contain a policy number that is traceable.
- Use the Official Search Tool: MetLife provides an online portal for policyholders to report death claims or search for unclaimed funds.
- Contact Official Support: For legacy cases, reach out directly to the company’s service center. Be prepared to provide the policyholder's full name, social security number, and approximate dates of policy purchase.
- State Unclaimed Property Databases: If a policy has been inactive for many years, the funds may have been turned over to the state’s Unclaimed Property Division. Always check the official website of the state where the policyholder resided at the time of purchase.
Important Considerations for Policyholders
Insurance products today are subject to strict legal guidelines. While historical policies offer security, modern consumers must balance the benefits of traditional whole life products with the tax advantages and flexibility of modern retirement vehicles.
- Financial Advice Limitation: This article is for informational purposes and does not constitute financial, legal, or tax advice. Individuals should consult with a licensed financial advisor or a qualified estate attorney before making decisions regarding long-term insurance assets or claims.
- Regulatory Changes: Insurance laws vary significantly by jurisdiction. Always verify the status of a policy through official channels and confirm that you are interacting with the authorized, legally recognized entity, rather than third-party search aggregators.
Frequently Asked Questions
Is "Metropolitan Life Insurance Company" still a valid business entity?
Yes, the entity continues to exist as a licensed insurer and is a core subsidiary of MetLife, Inc. While the branding has evolved into the more recognizable "MetLife," the legal entity remains fully operational and responsible for the obligations of its historical policies.
Can I still cash in a 50-year-old life insurance policy?
If the policy has accumulated cash value, it can typically be surrendered or utilized according to the terms of the original contract. However, policies that have been inactive for decades may have already been designated as "unclaimed property" and remitted to the state government. You should check both the company’s records and your state’s unclaimed property office.
How does the current company differ from the historical one?
The primary difference is the shift in ownership and business model. The original company was a mutual, focused on small-scale industrial insurance. The modern company is a global public corporation with a focus on institutional group benefits and sophisticated financial planning products.
How do I find a lost policy from the early 1900s?
Finding a policy from that era is difficult but possible if you have identifying information. If you lack the policy number, use the National Association of Insurance Commissioners (NAIC) Life Insurance Policy Locator service. This is a secure, official resource designed to help consumers find lost or forgotten life insurance policies.
Next Actions for Policyholders and Researchers
If you are a policyholder or an heir, your immediate next action should be to verify the existence of your coverage through official channels. Avoid using third-party websites that promise to "find money" for a fee; these services are unnecessary as state unclaimed property searches are free. If you are a student or researcher, the company archives—often held in partnership with university collections or public libraries—offer extensive insight into the social history of American insurance.
For those currently holding active policies, ensure your contact information and beneficiary details are updated. Administrative errors, such as outdated addresses, are the primary reason why policies become "lost" and eventually reach the status of unclaimed property. Maintaining an updated digital or physical file of your insurance portfolio is the single most effective step you can take to preserve these long-term assets.
Image Gallery
Select an image to open it in a new tab.




Vivian Cho
Executive IT and Emerging Technologies Reporter
