Choosing a Financial Advisor Planner: A Comprehensive Guide to Professional Wealth Guidance
Choosing a financial advisor planner is a critical life decision that involves assessing your financial goals, verifying professional credentials, understanding fee structures, and establishing a fiduciary relationship to protect your long-term economic well-being. Selecting the right partner requires navigating complex regulatory frameworks, distinguishing between various advisory designations, and evaluating how different professionals charge for their expertise.
Understanding the Role of a Financial Advisor Planner
Navigating the landscape of personal finance often requires more than budgeting software or self-directed investment apps. A financial advisor planner is a qualified professional who helps individuals and families design comprehensive roadmaps for wealth accumulation, risk management, retirement security, tax efficiency, and estate planning. Rather than focusing solely on picking stocks, a holistic planner evaluates your entire financial ecosystem to align your investments and savings habits with your life milestones.
The scope of service provided by these professionals can vary dramatically. Some advisors focus primarily on investment management, constructing portfolios tailored to your risk tolerance and time horizon. Others provide comprehensive financial planning that encompasses retirement income projections, college funding strategies, insurance adequacy reviews, and business succession planning. Understanding what you need from the relationship is the foundational step in selecting the appropriate professional.
Furthermore, the advisory industry encompasses a wide spectrum of business models. Some practitioners operate independently as registered investment advisers, while others work within large brokerage firms, insurance companies, or commercial banks. These structural differences dictate the breadth of products they can offer, the software and analytical tools at their disposal, and the governing regulatory bodies holding them accountable.
Fiduciary Duty vs. Suitability Standard
One of the most consequential factors in choosing a financial advisor planner is understanding the legal and ethical standard under which they operate. Not all financial professionals are held to the same legal obligations when managing your money, making this distinction a vital component of your due diligence.
The Fiduciary Standard
A fiduciary is legally and ethically bound to put your best financial interests ahead of their own or their firm's interests. Registered Investment Adviser (RIA) firms and practitioners holding specific designations like Certified Financial Planner (CFP) professionals are typically held to a fiduciary standard when providing financial planning or investment advice. Under this standard, an advisor must disclose any potential conflicts of interest, avoid practices that benefit them at your expense, and recommend options that are demonstrably optimal for your situation, even if those options yield lower compensation for the advisor.
The Suitability Standard
Conversely, many traditional stockbrokers, insurance agents, and dual-registrants operate under a suitability standard established by regulatory bodies like the Financial Industry Regulatory Authority (FINRA). Under this standard, an investment product or strategy only needs to be "suitable" for your demographic, risk profile, and goals at the time of the recommendation. This leaves room for advisors to recommend products that carry higher fees, commissions, or surrender charges, provided they meet a baseline threshold of appropriateness, even if a lower-cost or structurally superior alternative exists.
Regulatory Oversight
To verify the background, disciplinary history, and registration status of a prospective advisor, you can consult official regulatory databases. In the United States, the Securities and Exchange Commission (SEC) and FINRA maintain the Investment Adviser Public Disclosure (IAPD) website and BrokerCheck tool, respectively. These public databases allow you to confirm whether an advisor or their firm has faced customer complaints, regulatory disciplinary actions, or criminal convictions.
Professional Designations and Credentials
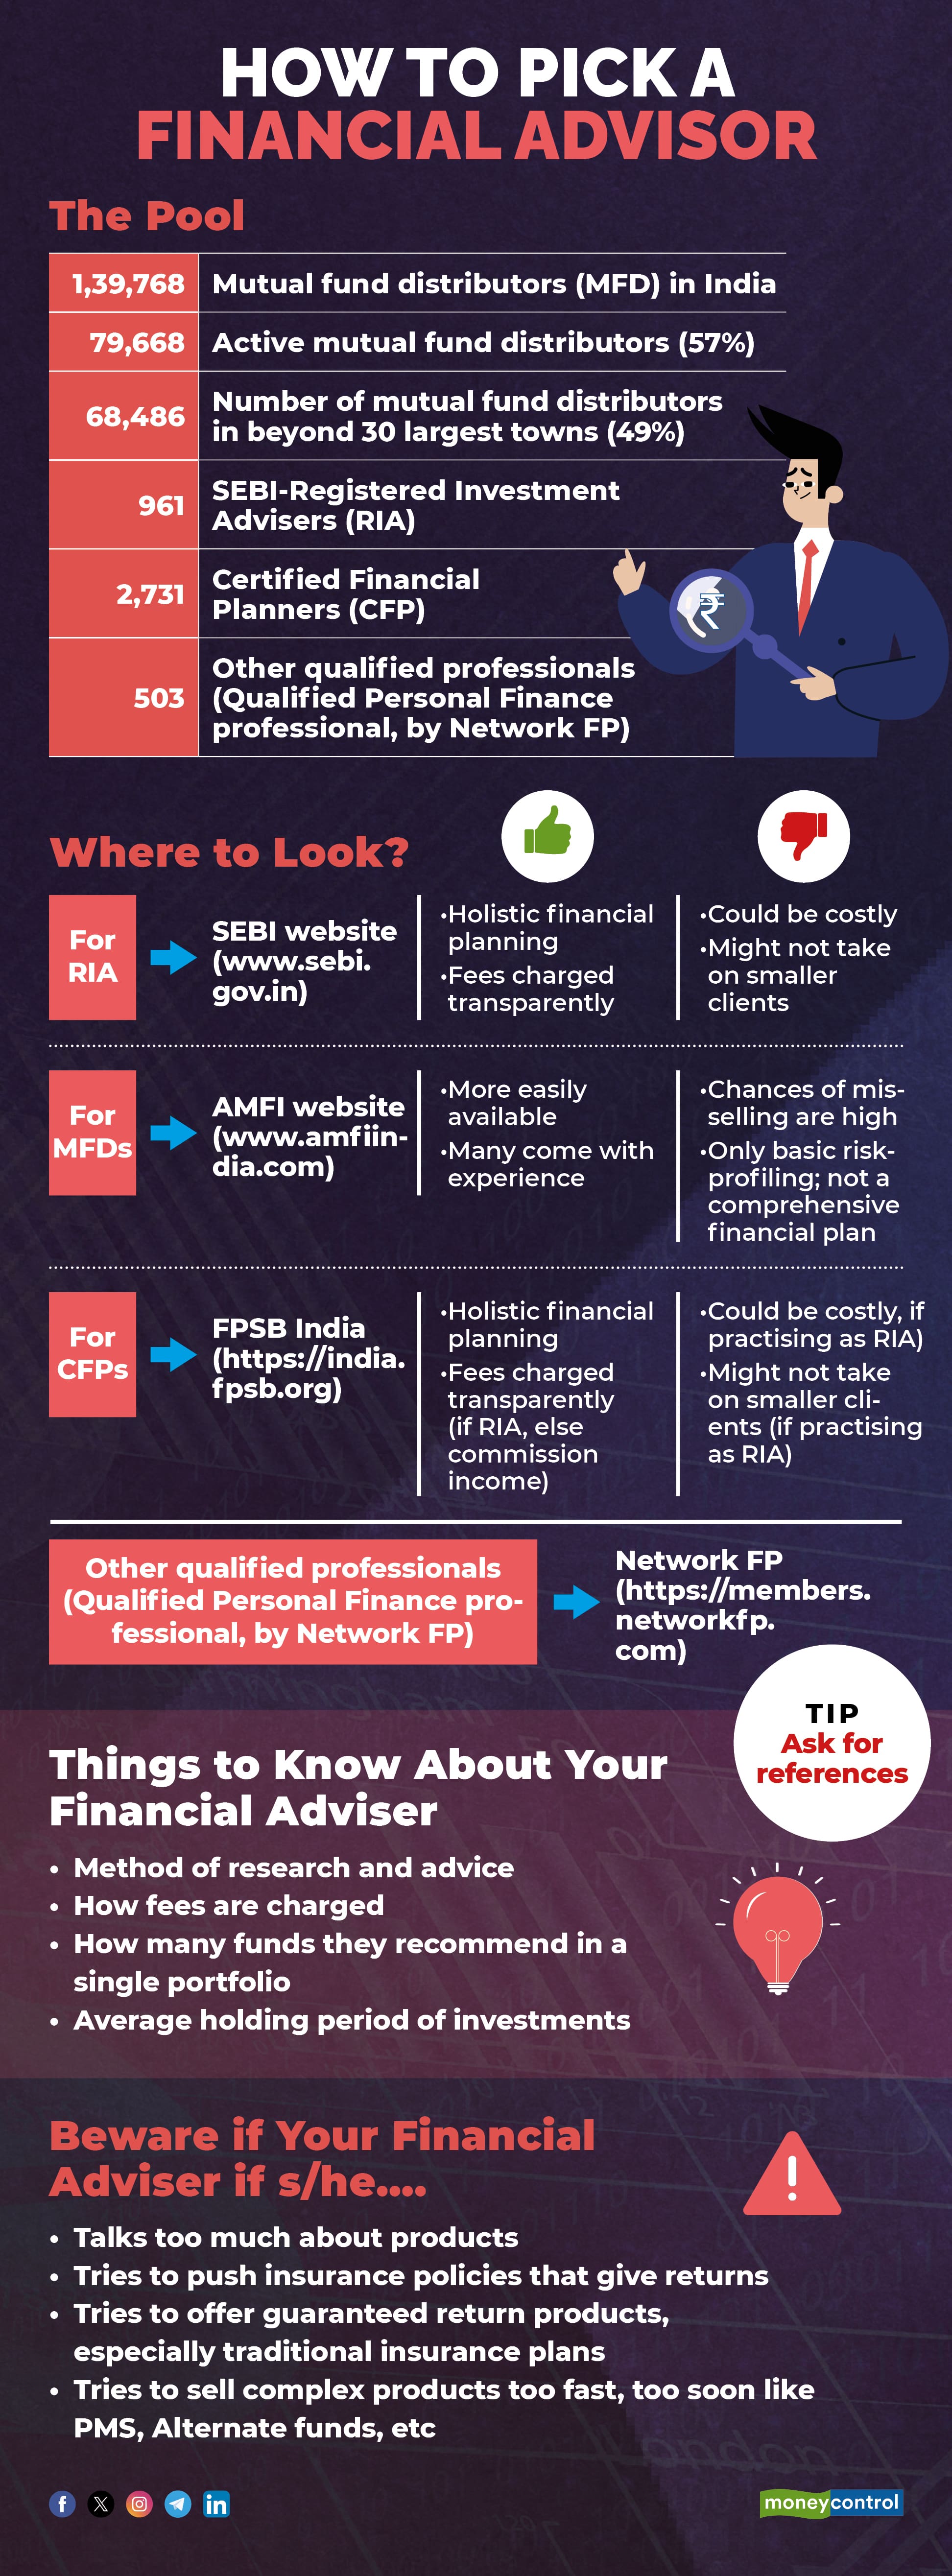
The financial services industry features a dizzying array of acronyms and certifications. While anyone can legally call themselves a financial advisor or wealth manager without specific credentials, legitimate professionals typically earn rigorous designations that require extensive study, continuing education, and adherence to strict ethical codes.
| Designation | Issuing Organization | Primary Focus | Fiduciary Obligation |
|---|---|---|---|
| CFP (Certified Financial Planner) | CFP Board | Comprehensive financial planning, tax, retirement, and estate strategies | Yes, when providing financial planning |
| CFA (Chartered Financial Analyst) | CFA Institute | Investment analysis, portfolio management, and financial research | Yes |
| CPA/PFS (Personal Financial Specialist) | AICPA | Tax-integrated financial planning and wealth management | Yes |
| ChFC (Chartered Financial Consultant) | The American College | Insurance, risk management, and comprehensive financial planning | Varies by registration |
When evaluating these credentials, look beyond the letters and examine the ongoing requirements to maintain them. For instance, CFP professionals must complete continuing education credits every two years, adhere to a rigorous code of ethics, and undergo regular background checks by the CFP Board. Conversely, generic or self-granted titles often indicate marketing designations rather than rigorous academic and professional achievements.
Evaluating Fee Structures and Compensation Models
How a financial advisor planner gets paid influences the advice they deliver and the potential conflicts of interest inherent in the relationship. Advisory compensation generally falls into three primary categories: fee-only, fee-based, and commission-based.
Fee-Only Advisors
Fee-only advisors are compensated solely by direct payments from their clients. They do not accept commissions, referral fees, or product kickbacks from third-party financial institutions. Fee-only structures typically manifest as:
- Assets Under Management (AUM): A percentage of the investment portfolio the advisor manages for you, typically ranging from 0.50% to 1.50% annually.
- Hourly Rates: Billing clients by the hour for specific consultations or plan reviews.
- Flat Fees: Charging a set price for a comprehensive financial plan or an ongoing annual retainer.
This model minimizes conflicts of interest, as the advisor’s income is tied directly to the quality of service or the long-term growth of your portfolio rather than the volume of products sold.
Fee-Based Advisors
The term "fee-based" is frequently confused with "fee-only," but it carries a distinct meaning. Fee-based advisors charge fees (such as AUM fees or hourly rates) but are also permitted to sell commission-based products, such as mutual funds with front-end loads, annuities, or insurance policies. While fee-based advisors may offer comprehensive planning, their ability to earn commissions introduces potential conflicts of interest that require careful scrutiny.
Commission-Based Advisors
Commission-based advisors earn their living entirely or primarily through the sale of financial products, such as insurance policies, managed funds, or specific securities. While they may offer free financial planning as a loss leader, their compensation is directly linked to product transactions. This model can incentivize frequent trading or the purchase of complex, high-commission products that may not align with your best interests.
Step-by-Step Process for Choosing an Advisor
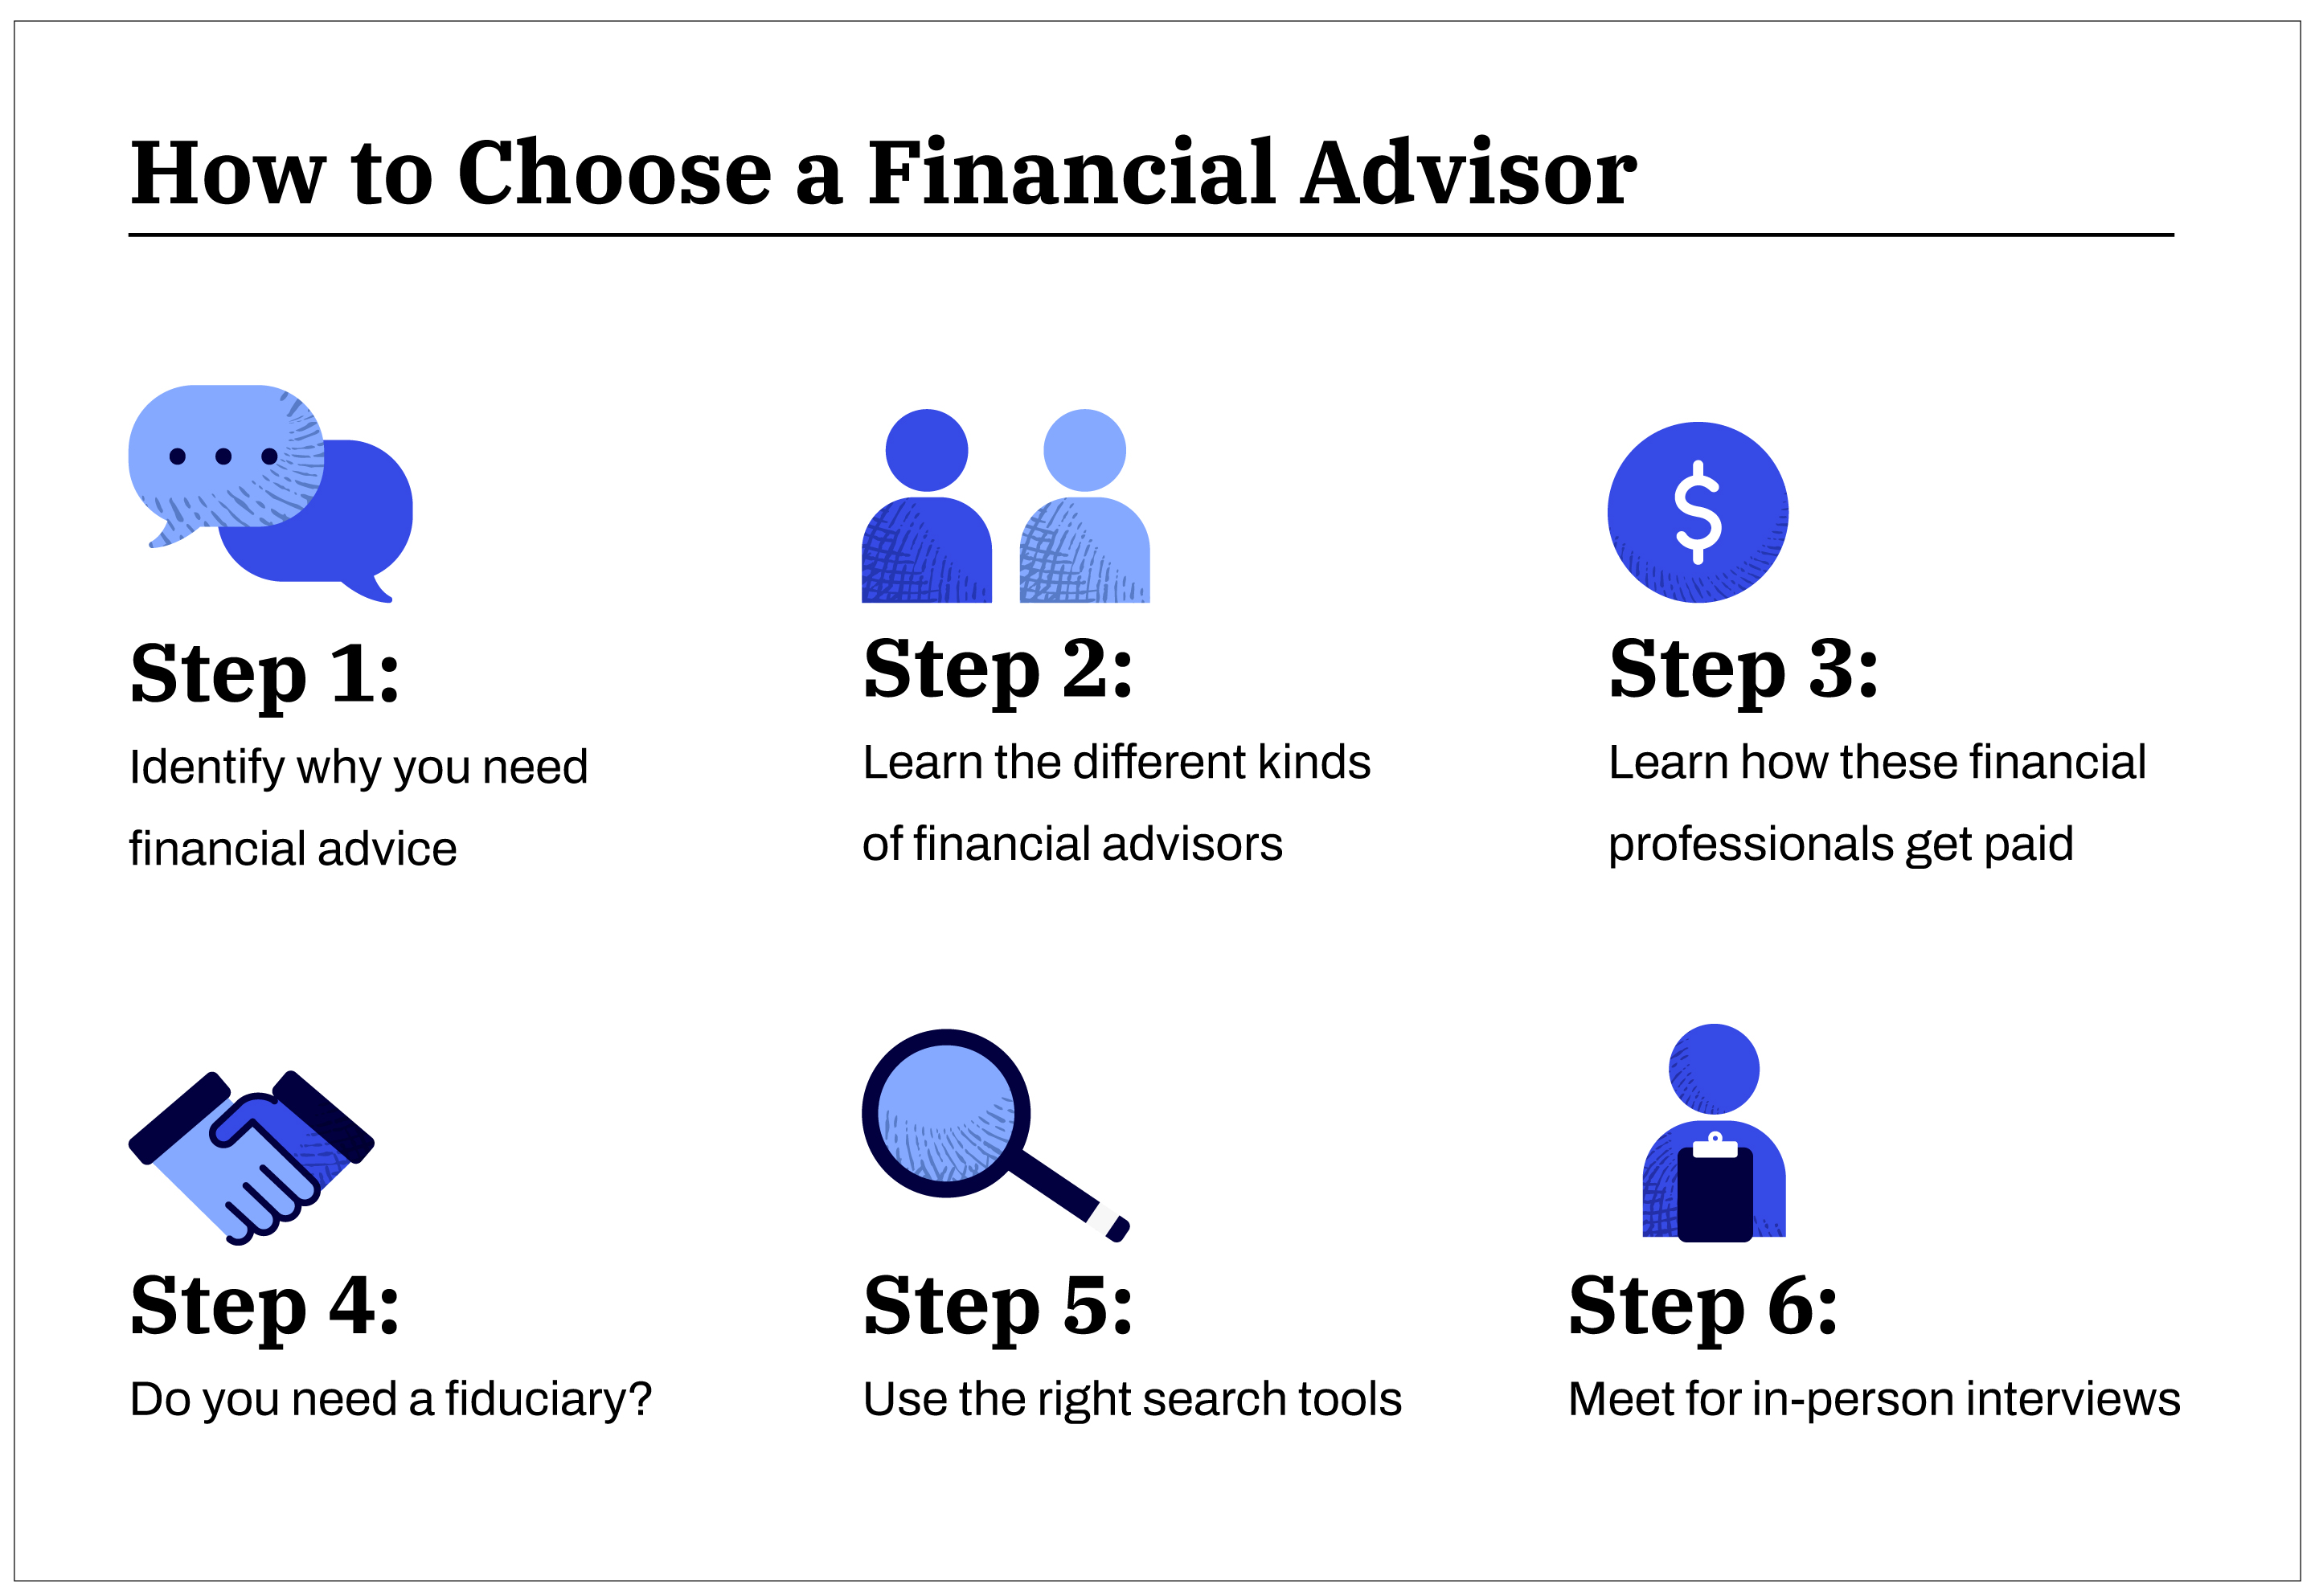
Finding, vetting, and hiring the right financial advisor planner requires a systematic approach. Rushing this process or relying solely on a personal recommendation without independent verification can lead to misaligned expectations and costly mistakes.
- Define Your Objectives: Determine why you need an advisor. Are you preparing for retirement, navigating a sudden inheritance, launching a business, or seeking ongoing portfolio management? Knowing your scope narrows down the field of qualified candidates.
- Determine Your Preferred Fee Model: Decide whether you prefer paying an ongoing percentage of your assets, a flat annual retainer, or hourly rates based on your net worth and comfort level.
- Compile a Shortlist of Candidates: Seek recommendations from trusted peers, certified public accountants, or estate planning attorneys, and cross-reference them with directories provided by professional associations like NAPFA (National Association of Personal Financial Advisors) or the Garrett Planning Network.
- Review Regulatory Filings: Access the SEC IAPD database or FINRA BrokerCheck to review Form ADV Part 2A (the firm's brochure) for every candidate on your shortlist. Pay close attention to Item 5 (fees), Item 10 (other financial industry activities and affiliations), and Item 11 (disciplinary information).
- Conduct Initial Interviews: Schedule introductory consultations—ideally with at least three candidates—to discuss their investment philosophy, communication style, team structure, and how they handle conflicts of interest.
- Evaluate and Execute: Compare the candidates based on their fiduciary commitment, transparency, chemistry, and alignment with your financial philosophy before signing an advisory agreement.
Common Pitfalls to Avoid
Navigating the advisory market exposes investors to several common traps. Recognizing these warning signs can save you from financial loss and frustration.
- Falling for High-Pressure Sales Tactics: Avoid advisors who pressure you to sign agreements immediately, claim they have exclusive access to market-beating strategies, or promise guaranteed returns. Legitimate planning focuses on risk management and realistic long-term projections.
- Ignoring Hidden Costs: Always read the fine print regarding custodial fees, underlying mutual fund expense ratios, and trading commissions. A low advisory fee can be offset by high internal product costs.
- Neglecting Cultural Fit: Financial planning deals with deeply personal aspects of your life. If an advisor talks down to you, dismisses your risk tolerance, or fails to communicate in a clear, transparent manner, the relationship is unlikely to succeed.
- Failing to Verify Credentials: Never take a professional title at face value. Always verify active certification status through the issuing organization's public lookup tool.
Conclusion
Choosing a financial advisor planner is an investment in your financial future that demands careful research, critical thinking, and rigorous due diligence. By prioritizing fiduciary accountability, verifying professional designations, understanding transparent fee structures, and conducting thorough background checks, you can establish a collaborative partnership that provides clarity, security, and strategic guidance for decades to come.
Image Gallery
Select an image to open it in a new tab.



Declan O'Connor
Higher Education and Campus Culture Reporter
