Choosing the Best Auto Insurance in North Lauderdale Florida: A Comprehensive Guide for 2026
Choosing the best auto insurance in North Lauderdale, Florida, requires balancing the state’s strict no-fault legal requirements with the specific risks inherent to Broward County’s dense urban environment. Residents must secure Personal Injury Protection (PIP) and Property Damage Liability (PDL) to maintain compliance while evaluating optional coverages like comprehensive and collision to protect against localized hazards such as flood damage and high-traffic congestion.
Understanding Florida’s No-Fault Insurance Framework
Florida is one of the few remaining "no-fault" states, a designation that fundamentally changes how you approach insurance. Under Florida law, regardless of who is at fault in an accident, your own insurance company pays for your medical expenses and lost wages up to the limits of your policy. This system is designed to minimize litigation for minor accidents, but it also necessitates specific coverage prerequisites.
To operate a motor vehicle legally in North Lauderdale, every driver must maintain a policy that includes:
- Personal Injury Protection (PIP): A minimum of $10,000 in coverage. This covers 80% of necessary medical expenses and 60% of lost wages, subject to policy terms.
- Property Damage Liability (PDL): A minimum of $10,000 in coverage. This pays for damages you cause to another person’s property, such as their vehicle, a fence, or a light pole, when you are at fault.
Because North Lauderdale is located in Broward County, many insurers consider your ZIP code a high-density area. Statistically, the risk of fender-benders and theft is higher in South Florida than in more rural regions of the state, which often results in higher baseline premiums for residents.
Factors Influencing Your Premium in North Lauderdale
Insurance providers in Florida do not use a "one-size-fits-all" pricing model. Instead, your premium is calculated using a complex algorithm based on several demographic and technical factors. Understanding these variables allows you to better manage your costs.
Driver Profile and History
Your driving record is the most significant determinant of your rate. A history of moving violations, at-fault accidents, or insurance lapses will classify you as a "high-risk" driver. In 2026, many carriers have implemented sophisticated telematics programs that track driving habits—such as hard braking, rapid acceleration, and late-night driving—to offer personalized discounts for "safe" behavior.
Vehicle Specifications
The make, model, and year of your vehicle directly impact your comprehensive and collision premiums. Expensive vehicles with complex safety sensors, advanced electronic components, or parts that are difficult to source in the Florida market will cost more to insure. Furthermore, your vehicle’s safety rating and theft susceptibility—a critical factor in urban South Florida—will be reflected in your final quote.
Coverage Limits and Deductibles
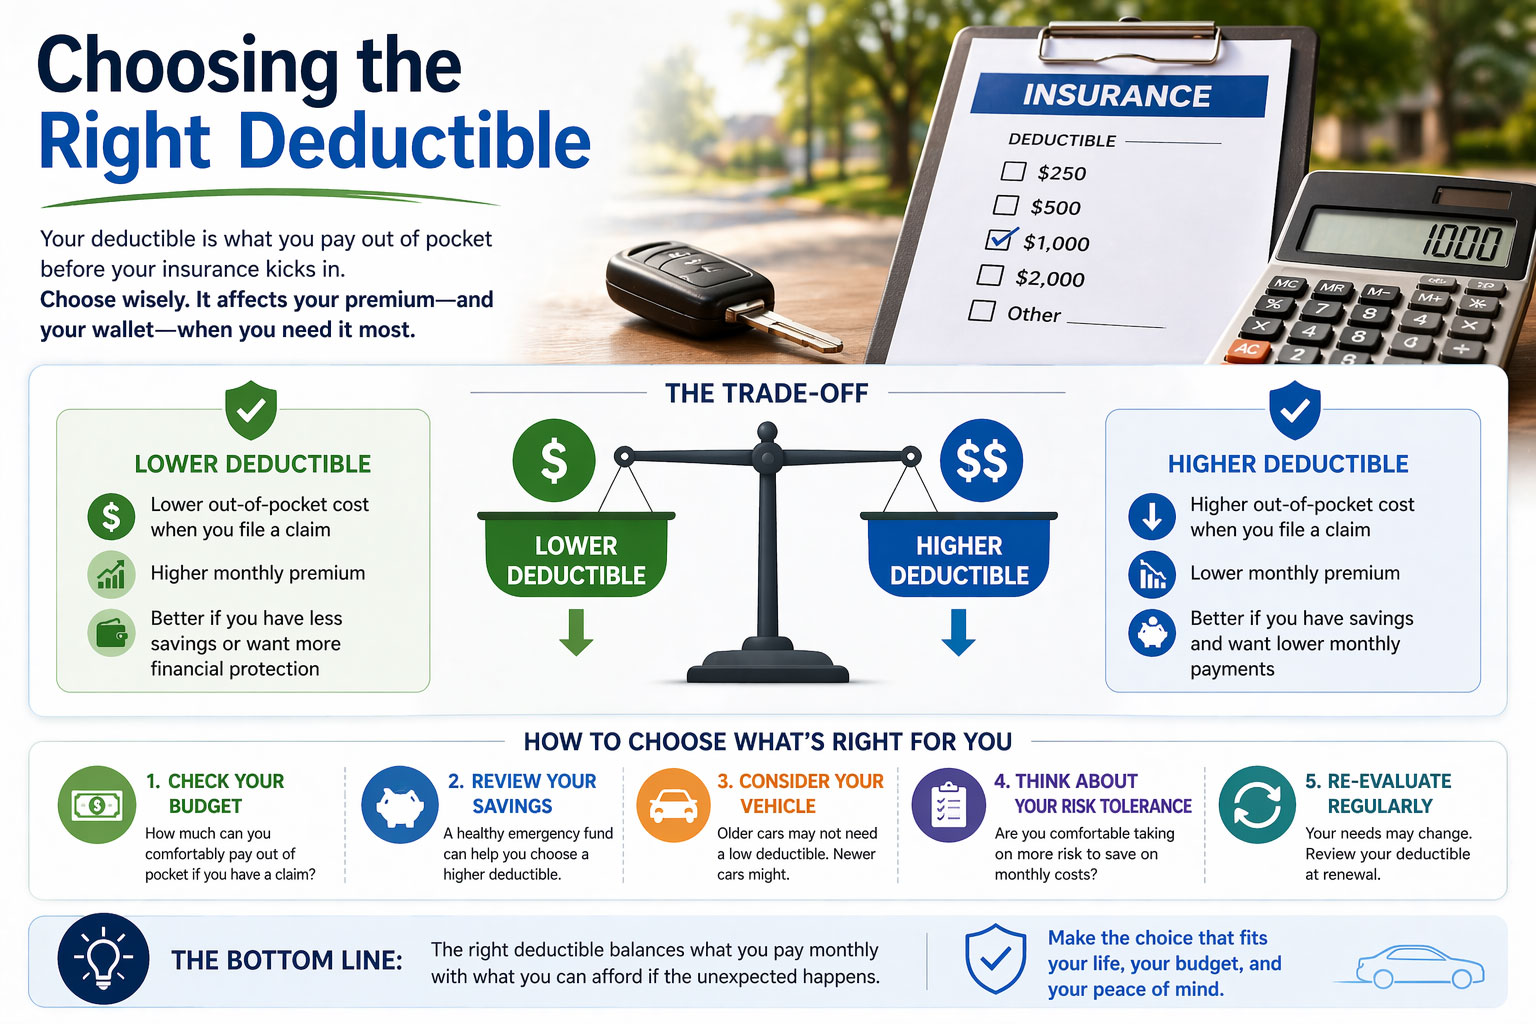
The "best" insurance is not necessarily the cheapest. If you drive a newer vehicle, carrying only the state-mandated $10,000 in PDL leaves you financially vulnerable. If you cause an accident involving an expensive luxury car, your liability could far exceed $10,000, leaving you personally responsible for the remainder. Increasing your liability limits and choosing an appropriate deductible for collision and comprehensive coverage are vital steps in protecting your assets.
Comparing Coverage Types: What Do You Really Need?
When reviewing quotes, you will encounter several coverage tiers. Determining which are necessary depends on your financial situation and your car’s current market value.
| Coverage Type | Purpose | Recommendation for North Lauderdale |
|---|---|---|
| PIP | Medical/Lost wages | Mandatory minimum required |
| PDL | Property damage to others | Increase above minimum ($50k-$100k) |
| Collision | Repairs to your car | Essential for financed/newer cars |
| Comprehensive | Theft, flood, weather | Highly recommended for Florida weather |
| Uninsured Motorist | Protects you from uninsured drivers | Strongly recommended for high-traffic areas |
In Florida, Uninsured Motorist (UM) coverage is highly valuable. Given that a significant percentage of drivers in the state either operate without insurance or carry only the bare minimum, UM coverage acts as a critical safety net. It covers your medical bills and property damage if you are struck by someone who lacks the financial capacity to pay for the damage they caused.
Navigating Local Challenges: Weather and Traffic
North Lauderdale presents unique challenges that influence your insurance strategy.
Flood Risk and Comprehensive Coverage: Florida is prone to sudden, severe rain events. If your vehicle sustains water damage, standard liability insurance will not cover it. Comprehensive coverage is the specific component that handles non-collision-related damage, including flooding, fallen tree branches, or vandalism. For residents living in low-lying areas or near drainage zones in Broward County, skipping comprehensive coverage is a significant financial risk.
Traffic Density: The proximity to major highways like the Florida Turnpike and I-95 creates a high-frequency accident environment. Your commute, the time of day you travel, and the safety features of your vehicle (such as automatic emergency braking) can sometimes lead to "safety discounts" offered by major providers operating in the region.
Steps to Selecting the Best Policy
- Gather Documentation: Before requesting quotes, have your Driver’s License, Vehicle Identification Number (VIN), and current policy declaration page ready.
- Evaluate Your Financial Risk: Determine how much you can afford to pay out-of-pocket (your deductible) versus the monthly premium cost. A higher deductible usually lowers your premium.
- Request Multiple Quotes: Use the Florida Office of Insurance Regulation (OIR) tools to verify that a company is licensed to do business in the state. Avoid "too good to be true" offers from non-admitted carriers.
- Review the Fine Print: Look specifically at the "exclusions" section of the policy. Understand what your insurance will not cover, particularly regarding rental car reimbursements or towing services.
- Assess Customer Service: Look for reviews regarding the company's claims handling process in South Florida. A cheap policy is ineffective if the claims department is difficult to reach or denies reasonable requests.
Common Mistakes to Avoid
- Underinsuring to Save Money: Cutting liability limits to the state minimum is a common trap. If you are sued after a significant accident, your personal savings, home, and wages could be subject to a lien.
- Failing to Update Policy Information: If you move, get married, or install a new alarm system, notify your insurer immediately. These changes can often result in lower premiums.
- Ignoring the "Gap" in Gap Insurance: If you have a lease or a high-interest loan on your car, ensure you have Gap Insurance. This covers the difference between what your car is worth (its depreciated value) and what you owe on the loan if the car is totaled.
Frequently Asked Questions
Does Florida law allow me to carry only the bare minimum insurance? Yes, you can legally drive with only $10,000 in PIP and $10,000 in PDL. However, financial experts strongly advise against this. Because medical costs in Florida can easily exceed $10,000 following a single hospital visit, the minimum coverage is almost never sufficient to protect your financial well-being in the event of a serious collision.
How does my credit score affect my auto insurance rate in 2026? In Florida, many insurance carriers use credit-based insurance scores as one of the many factors to set rates. Statistical models often correlate lower credit scores with a higher frequency of claims. Maintaining good credit can often lower your premiums, whereas poor credit may make it difficult to secure competitive rates from top-tier carriers.
Are there specific discounts I should ask about in North Lauderdale? Yes. Always ask your agent about discounts for defensive driving courses, anti-theft devices, low annual mileage, and "bundling" (having your homeowners or renters insurance with the same company). Students with good grades and drivers over the age of 50 may also qualify for specific, state-recognized discounts.
Should I choose an agent or buy direct online? This depends on your preference. Buying online offers convenience and speed. However, working with a local independent agent in Broward County can be advantageous. A local agent understands the specific climate and traffic patterns of North Lauderdale and can navigate the unique challenges of the Florida insurance market on your behalf.
What happens if I let my insurance lapse? Florida is extremely strict regarding continuous coverage. If your insurance lapses, the Florida Department of Highway Safety and Motor Vehicles (FLHSMV) will be notified, and your driver’s license and registration may be suspended. Reinstating them often requires paying a fee and, more importantly, will cause your premiums to spike when you eventually purchase a new policy, as you will be classified as a "lapsed" risk.
Final Recommendation
The "best" auto insurance in North Lauderdale is a policy that aligns your budget with your tolerance for risk. Prioritize higher liability limits (at least $50,000/$100,000) and ensure you have both collision and comprehensive coverage if your vehicle is less than 10 years old. Before finalizing any policy in 2026, verify the company's financial strength rating through a service like AM Best to ensure they have the liquidity to pay out large claims. Start by gathering quotes from at least three different insurers, compare the total package—not just the monthly price—and select the provider that balances competitive pricing with a reputation for reliable claims processing.
Image Gallery
Select an image to open it in a new tab.

Celine Dubois
Contemporary Living and Global Arts Columnist
