Understanding Financial Benchmarks: Average Net Worth, Income, and Credit Scores in Massachusetts

Navigating the financial landscape in Massachusetts requires an understanding of how regional economic factors intersect with personal fiscal health. While individual circumstances vary significantly, state-level data provides a baseline for comparing personal net worth, median household income, and average credit scores, helping residents assess their financial standing relative to the broader Bay State population in 2026.
The Interplay of Regional Economics and Personal Finance
Massachusetts consistently ranks among the states with the highest cost of living, which fundamentally alters the typical metrics for financial success. When discussing average net worth, income, and credit scores, it is essential to distinguish between "averages" (which can be skewed by the high concentration of extreme wealth in areas like Greater Boston) and "medians" (which better represent the typical household).
For many residents, these figures serve as a diagnostic tool rather than a rigid goal. Whether you are planning for retirement, applying for a mortgage in a competitive market, or simply auditing your savings rate, viewing your personal financial data against state benchmarks can reveal gaps in your strategy or validate your current path.
Analyzing Median Household Income in Massachusetts
In 2026, Massachusetts maintains one of the highest median household incomes in the United States. According to U.S. Census Bureau data and current economic projections, the median household income for the state typically hovers well above the national average. This is driven largely by a robust economy anchored in biotechnology, higher education, finance, and professional services.
However, a high median income does not necessarily translate to high disposable income for all. The high cost of housing in counties like Middlesex, Norfolk, and Suffolk consumes a larger percentage of gross income than in many other parts of the country. When evaluating your household income, consider the "adjusted" value—what remains after accounting for state taxes, elevated property costs, and essential services.
Net Worth: Beyond Income and Assets
Net worth is the truest measure of financial health, defined as the total value of all assets (real estate, savings, retirement accounts, investments) minus all liabilities (mortgages, student loans, consumer debt). Because Massachusetts has high property values, many homeowners see their net worth climb significantly over time due to real estate appreciation.
- The Impact of Real Estate: For a significant portion of Massachusetts households, the primary driver of net worth is home equity.
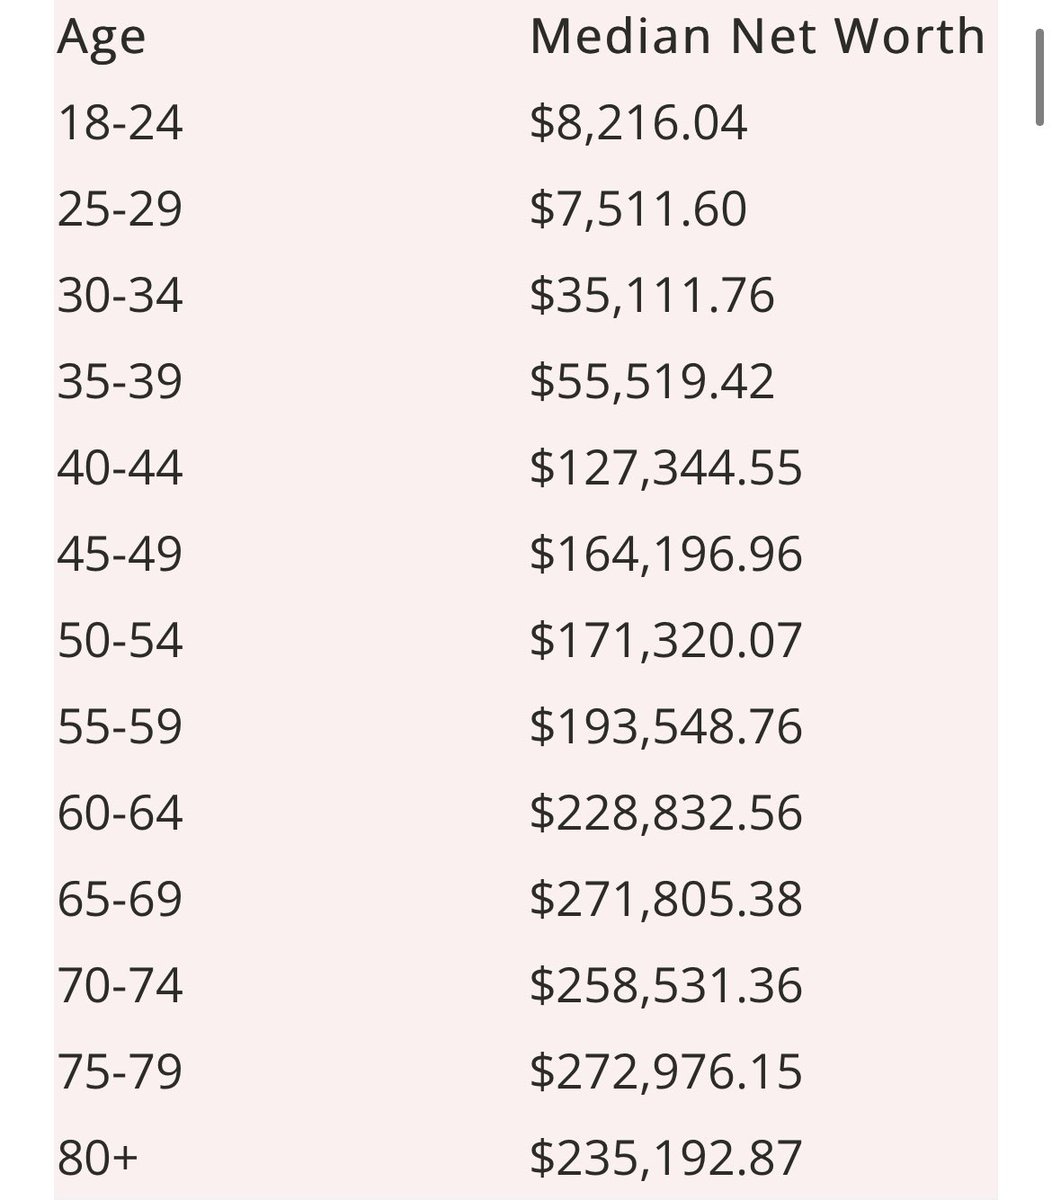
- The Wealth Gap: The state exhibits a distinct wealth disparity. While the average net worth might seem high, this is heavily influenced by the upper quintile of earners. Median net worth is often a more accurate metric for the middle-class experience.
- Asset Allocation: Massachusetts residents often hold a high concentration of their net worth in retirement vehicles (401(k) and 403(b) plans), supported by the state’s high concentration of professional roles.
Credit Score Standards in the Bay State
Credit scores are objective, but the "average" credit score in Massachusetts generally trends slightly higher than the national mean. This is often attributed to a workforce that frequently engages with high-level financial services and a demographic that skews toward higher educational attainment, which correlates statistically with better credit management.
A strong credit score—typically defined as 740 or above on the FICO scale—is almost a prerequisite for securing housing in Massachusetts. With interest rates fluctuating and competition for rentals and homes remaining fierce, your credit score is your most important tool for accessing credit at favorable terms.
Factors Influencing Your Credit Standing
- Payment History: This remains the single largest factor in your score. Consistent, on-time payments are the foundation of a healthy profile.
- Credit Utilization: Keeping balances low relative to total available credit is crucial, especially when living in a high-cost area where residents may be tempted to rely on credit for daily expenses.
- Length of Credit History: Longer relationships with creditors demonstrate stability.
- Credit Mix: Having a combination of revolving credit (credit cards) and installment loans (mortgages, auto loans) often boosts scores.
Comparative Financial Metrics Table
The following table provides a conceptual framework for comparing standard financial metrics in Massachusetts. These figures are approximations based on aggregate economic reporting and should be treated as comparative benchmarks rather than individual targets.
| Metric | Contextual Importance | Typical Status in Massachusetts |
|---|---|---|
| Median Household Income | Determines baseline purchasing power | Consistently above national median |
| Average Credit Score | Critical for housing/loan approvals | Generally above national average (720+) |
| Net Worth Composition | Indicates long-term stability | Heavy reliance on home equity/investments |
| Debt-to-Income (DTI) Ratio | Loan eligibility threshold | Highly sensitive due to mortgage costs |
The Relationship Between Income, Debt, and Credit
It is a common misconception that high income automatically leads to high credit scores or high net worth. In reality, credit scores are a reflection of credit behavior, not income level. You can have a high income but a low credit score if you miss payments or maintain high utilization. Conversely, you can have a modest income but an excellent credit score through disciplined financial management.
In Massachusetts, the challenge is often maintaining a low DTI ratio. Because the state’s housing market is expensive, many residents have high mortgage-to-income ratios. Lenders are particularly cautious about this in 2026, looking closely at whether a borrower has enough remaining cash flow to handle the state’s cost of living and property tax burdens.
Strategic Financial Management
To improve your financial standing relative to state benchmarks, focus on these three areas:
- Automate Debt Reduction: If you have high-interest debt, prioritize paying this down to improve your DTI ratio. This improves your net worth by reducing liabilities and boosts your credit score by lowering utilization.
- Maximize Tax-Advantaged Accounts: Given the high cost of living, utilizing 401(k) or IRA contributions reduces your taxable income while simultaneously building long-term net worth.
- Regular Audits: Pull your free credit reports annually. In Massachusetts, where identity theft and financial fraud can be concerns, monitoring your report for inaccuracies is a necessary step to protect your credit score.
Frequently Asked Questions
Does a high income automatically result in a high credit score? No. Credit scores measure your ability to manage debt responsibly over time. A person with a lower income who pays every bill on time and keeps credit utilization low will often have a higher credit score than a high-income earner who misses payments or carries high credit card balances.
Why is net worth often higher in Massachusetts than in other states? The primary driver is real estate valuation. Because the cost of buying a home in Massachusetts is significantly higher than the national average, homeowners here accumulate home equity much faster. When that equity is added to their assets, it pushes the total net worth figure upward compared to states with lower property values.
How much does my credit score affect my ability to buy a home in Massachusetts? It is a decisive factor. In a high-cost market like Massachusetts, lenders require a strong credit profile to approve competitive mortgage rates. A score below 700 may limit your loan product options or result in significantly higher interest rates, which, on a large Massachusetts mortgage, can translate into thousands of dollars in extra costs per year.
What is the best way to verify my current net worth? To calculate your net worth, create a comprehensive list of all your assets, including cash, retirement accounts, and the current market value of your property. Subtract all your liabilities, including your mortgage balance, car loans, and any outstanding credit card debt. The remaining total is your net worth.
Should I be concerned if my income is below the state median? Not necessarily. Median income is a statistical midpoint, not a standard for individual financial health. Your focus should be on your personal budget, your ability to save, and your progress toward your specific financial goals rather than comparing your gross income to a state-wide statistic.
Next Steps for Personal Financial Planning
If you are looking to benchmark your financial health, start by documenting your current total assets and total liabilities to determine your net worth. Simultaneously, obtain your credit report from the three major bureaus to verify that your information is accurate. If you find that your metrics are lower than you would like, focus first on increasing your monthly savings rate and reducing high-interest debt. For specific investment or tax-related advice, consider consulting a certified financial planner who understands the unique tax environment of Massachusetts.
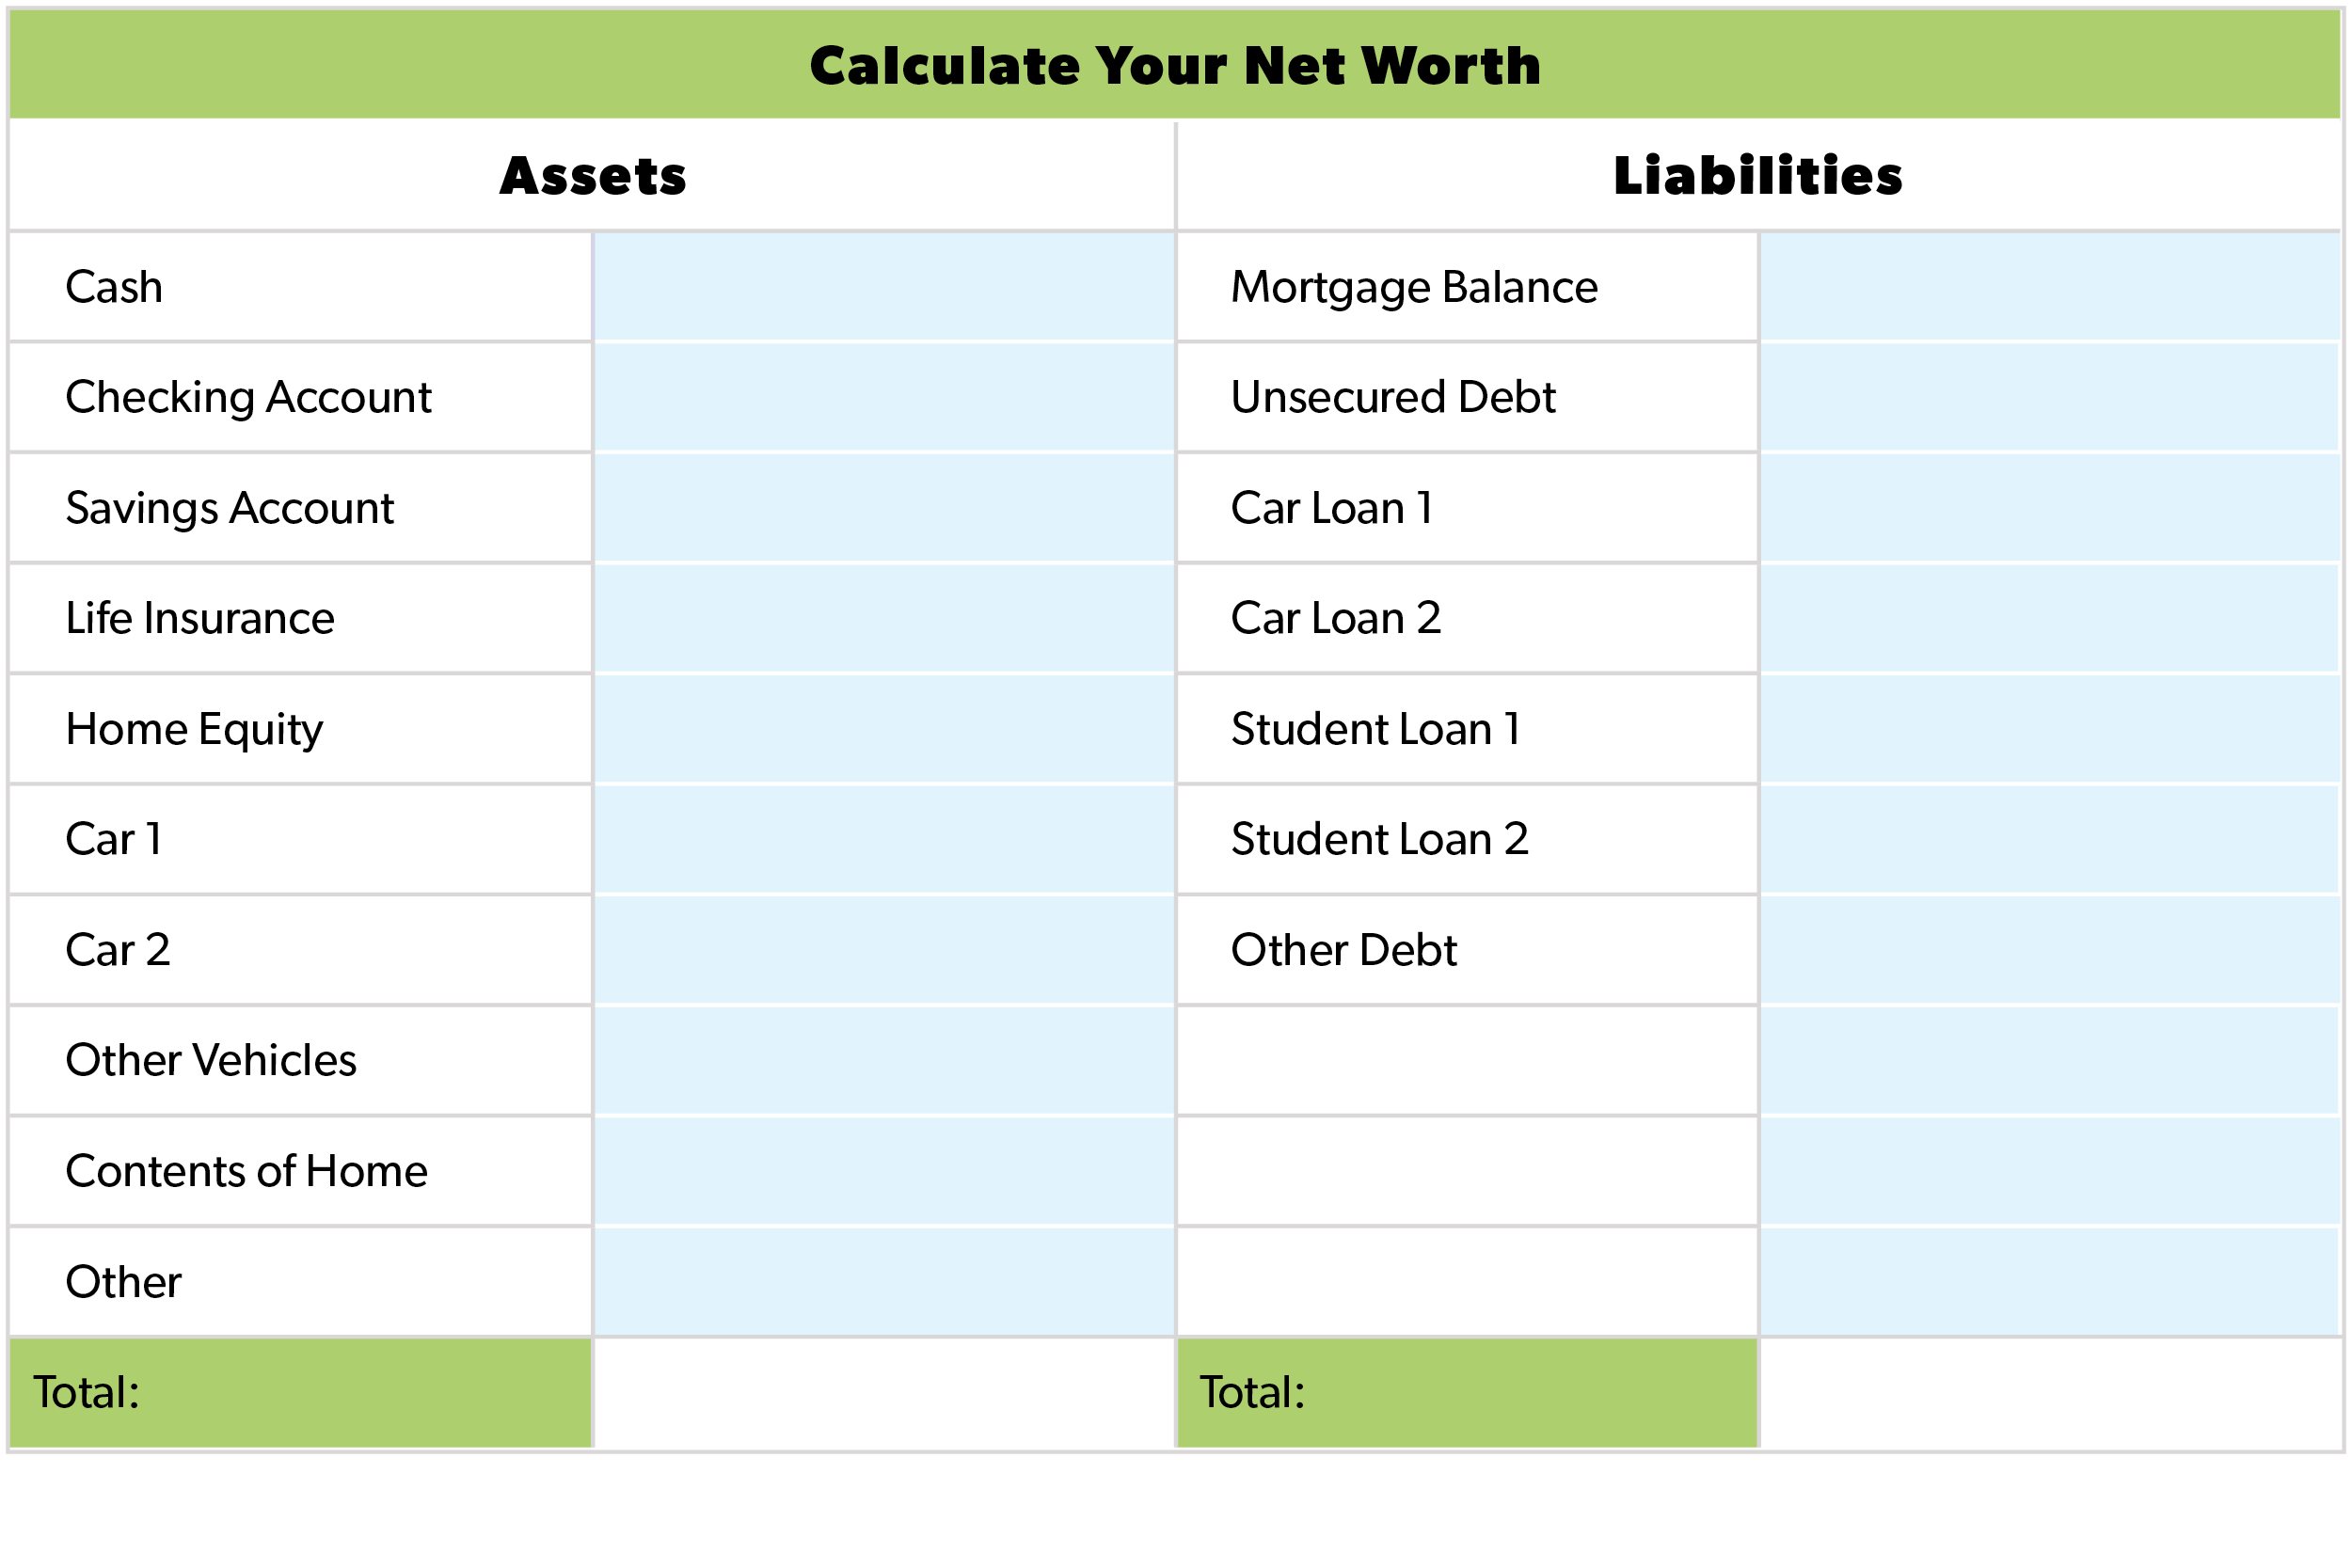
Image Gallery
Select an image to open it in a new tab.


Simon Caldwell
Enterprise Technology and Systems Editor
