Allianz Whole Life Insurance Explained: Features, Benefits, and Global Availability in 2026

Allianz whole life insurance is a permanent life insurance contract designed to provide lifelong coverage, a guaranteed death benefit, and a cash value component that grows over time. While Allianz primarily offers Indexed Universal Life (IUL) in the United States, its global whole life products provide policyholders with fixed premiums and predictable long-term financial security for estate planning and legacy protection.
Understanding the Foundation of Allianz Whole Life Insurance
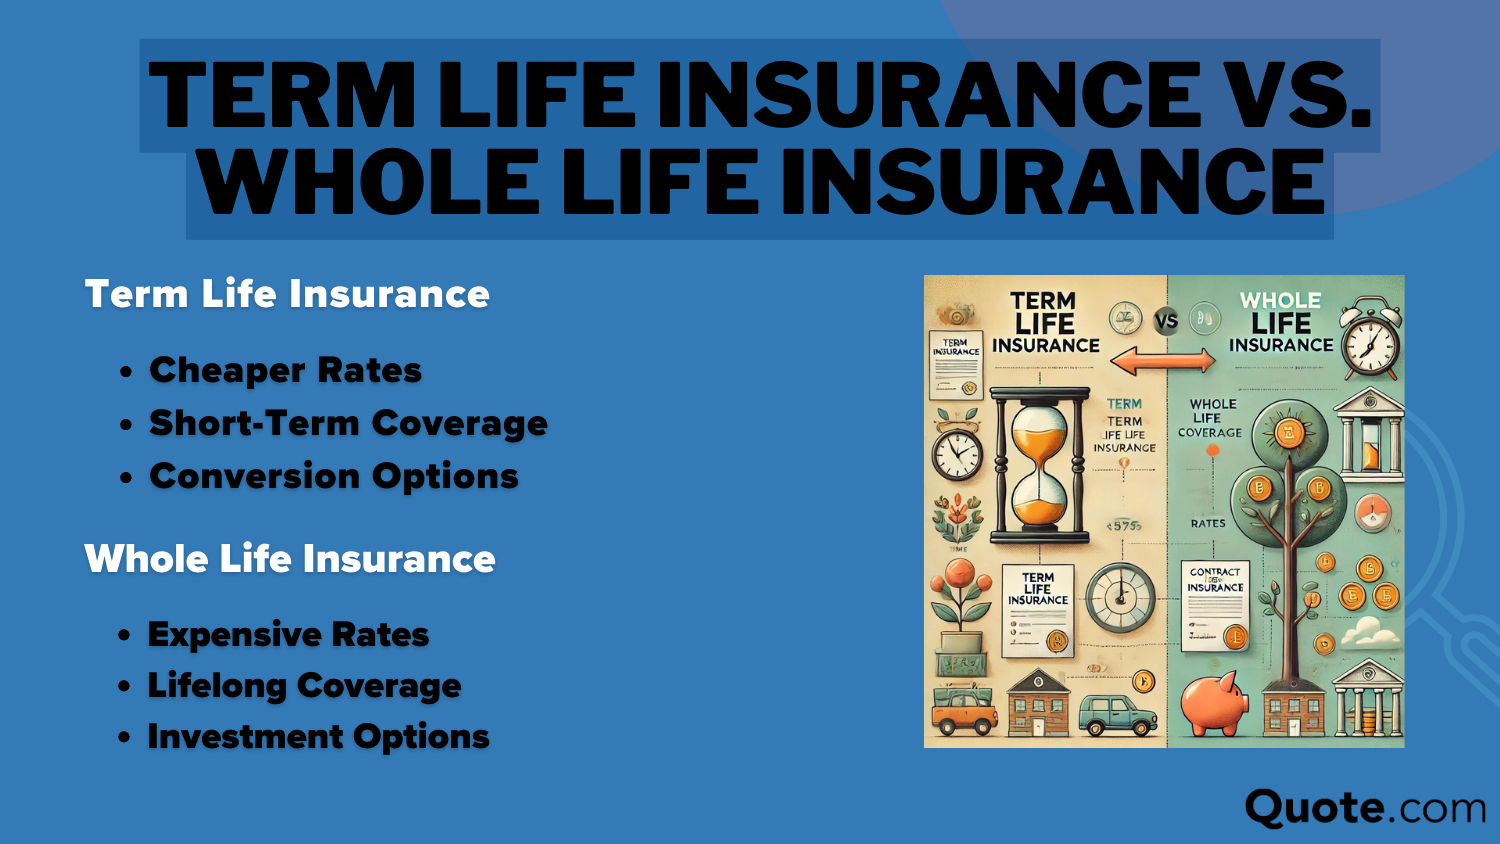
To understand Allianz whole life insurance, one must first distinguish between the various types of permanent life insurance. Unlike term life insurance, which expires after a set period (usually 10 to 30 years), whole life insurance is designed to remain in force for the duration of the insured’s life, provided premiums are paid. In 2026, Allianz continues to be recognized as one of the world's most stable financial institutions, lending significant weight to the long-term guarantees inherent in these policies.
The "whole" in whole life refers to the comprehensive nature of the timeline. As long as the policyholder meets their obligations, the contract generally cannot be canceled by the insurer due to changes in health or age. This makes it a foundational tool for individuals looking for "forced savings" or those who need a guaranteed payout to cover estate taxes, funeral costs, or an inheritance for heirs.
In the global market, Allianz often structures these policies as "participating" or "non-participating." Participating policies may be eligible for dividends, which are essentially a return of a portion of the premium if the company’s financial performance exceeds expectations. While dividends are never guaranteed, Allianz’s historical performance as a global leader in asset management often makes these versions attractive to conservative investors.
The Three Pillars: Death Benefit, Premiums, and Cash Value
An Allianz whole life policy is built on three core components that work in tandem to provide both protection and a living benefit.
1. The Guaranteed Death Benefit
The primary purpose of the policy is the death benefit. Upon the passing of the insured, Allianz pays a tax-free lump sum to the designated beneficiaries. Because this is a whole life policy, the amount is guaranteed from day one. In 2026, many families use this guarantee to ensure that their mortgage is paid off or that their children's education is funded, regardless of when the policyholder passes away.
2. Level Premiums
One of the most significant advantages of Allianz whole life insurance is premium stability. When the policy is issued, the premium is locked in for life. It will not increase as the insured gets older or if they develop a chronic illness. This predictability is vital for long-term retirement planning, as it allows individuals to account for a fixed expense in their budget decades into the future.
3. Cash Value Accumulation
A portion of every premium payment is funneled into a cash value account. This account grows on a tax-deferred basis at a minimum guaranteed interest rate set by Allianz. Over several decades, this cash value can grow into a significant asset. Policyholders can access this money through policy loans or withdrawals, providing a source of liquidity for emergencies, supplemental retirement income, or business opportunities.
Regional Availability and Product Disambiguation
It is essential to clarify the distinction between Allianz Life Insurance Company of North America (Allianz Life) and the broader Allianz SE global entity.
In the United States, as of 2026, Allianz Life does not typically market a "traditional" whole life insurance product. Instead, they have cornered the market on Indexed Universal Life (IUL) and annuities. If a US-based consumer is searching for Allianz whole life, they are often directed toward the Allianz Life Pro+ series. While IUL is a permanent policy with cash value, it differs from whole life because its growth is tied to external market indexes (like the S&P 500) rather than a fixed rate, and premiums can be flexible rather than strictly level.
However, in Europe, Asia, and Africa, Allianz offers robust whole life portfolios. For instance, in markets like Singapore, Malaysia, and Germany, Allianz whole life products (such as "Allianz Life Power" or "Allianz Heritage") are staples. These products are often used for "key person" insurance in businesses or as high-net-worth estate planning tools. When evaluating "Allianz whole life," you must ensure the product specifications align with your specific geographical jurisdiction.
The Role of Dividends in Allianz Policies
For Allianz policies that are "participating," dividends play a crucial role in the policy’s internal rate of return. Dividends are not legally guaranteed, but they are a hallmark of established mutual or well-capitalized stock insurers like Allianz.
In 2026, policyholders typically have several options for how to use their dividends:
- Cash: Receive the dividend as a check.
- Premium Reduction: Apply the dividend toward the next year’s premium.
- Paid-Up Additions: Use the dividend to purchase more death benefit and cash value within the same policy. This is often the most effective way to compound the policy's value over time.
- Accumulate at Interest: Leave the dividends with Allianz to earn interest, similar to a savings account.
Technical Specifications and Policy Riders
To customize a policy, Allianz offers several "riders"—optional add-ons that provide extra benefits, often for an additional cost. In 2026, the following riders are most common in Allianz permanent life contracts:
- Waiver of Premium: If the insured becomes totally disabled and cannot work, Allianz waives the premium payments while keeping the policy in force.
- Accelerated Death Benefit: This allows the policyholder to access a portion of the death benefit while still living if they are diagnosed with a terminal or chronic illness. This is increasingly used to fund long-term care needs.
- Accidental Death Benefit: Provides an additional payout if the cause of death is an accident rather than natural causes.
- Child Term Rider: Allows the policyholder to add a small amount of term coverage for their children under the parent’s primary policy.
Comparing Allianz Permanent Insurance Options
When deciding on a policy, it is helpful to see how whole life stacks up against other Allianz offerings.
| Feature | Whole Life Insurance | Indexed Universal Life (IUL) | Term Life Insurance |
|---|---|---|---|
| Duration | Entire Life | Entire Life | 10, 20, or 30 years |
| Premiums | Fixed/Level | Flexible | Fixed for term length |
| Cash Value | Guaranteed Growth | Market-Linked Growth | None |
| Death Benefit | Guaranteed | Variable (based on funding) | Guaranteed for term |
| Complexity | Low to Moderate | High | Very Low |
| Ideal Use Case | Legacy/Estate Planning | Wealth Accumulation | Temporary Debt/Income Replacement |
Assessing the Financial Strength of Allianz in 2026
When you purchase whole life insurance, you are entering into a contract that could last 50, 60, or even 80 years. Therefore, the financial "health" of the insurer is the most critical factor.
Allianz SE is consistently rated among the highest in the world by independent agencies. In 2026, its ratings remain strong:
- Standard & Poor’s: AA or higher.
- A.M. Best: A+ (Superior).
- Moody’s: Aa3 or higher.
These ratings indicate a "very strong" or "superior" ability to meet ongoing insurance obligations. For a whole life policyholder, this provides peace of mind that the death benefit will be paid and the cash value guarantees will be honored even in volatile economic cycles.
Pros and Cons of Allianz Whole Life Insurance
As with any financial product, whole life insurance has specific trade-offs that must be weighed against your personal goals.
The Advantages
- Risk Mitigation: The stock market does not affect the guaranteed portion of your cash value. This "non-correlated asset" can provide a hedge against market volatility.
- Tax Advantages: The death benefit is usually income tax-free to beneficiaries under Internal Revenue Code Section 101(a). Furthermore, cash value grows without being taxed annually.
- Ease of Management: Unlike Universal Life, which requires monitoring of "cost of insurance" (COI) charges and interest rates, Whole Life is largely "set it and forget it."
The Disadvantages
- Higher Initial Cost: Premiums for whole life are significantly higher than term life because you are pre-funding the later years of your life and building an equity account.
- Rigidity: Once the policy is established, you generally cannot easily change the premium amount or the death benefit without starting a new application.
- Slower Growth: While safe, the guaranteed interest rate on whole life is typically lower than the potential returns of the stock market or an IUL policy during a bull market.
Who Should Consider Allianz Whole Life?
Allianz whole life insurance is not for everyone. It is most appropriate for:
- High-Net-Worth Individuals: Those who have maximized their 401(k) or IRA contributions and are looking for another tax-advantaged vehicle for wealth transfer.
- Parents of Children with Special Needs: A whole life policy ensures that a trust will be funded regardless of when the parents pass away, providing lifelong care for the child.
- Business Owners: It can be used for "Buy-Sell" agreements or to provide a "Golden Handshake" executive benefit.
- Conservative Savers: People who want a guaranteed return and are wary of the market volatility associated with IUL or Variable life insurance.
Common Mistakes to Avoid
When navigating the Allianz application process, be mindful of these pitfalls:
- Underfunding the Policy: If you plan to use the cash value for retirement, ensuring the policy is structured for maximum cash accumulation (often through Paid-Up Additions) is vital.
- Lapsing the Policy: If you stop paying premiums in the early years before enough cash value has built up, the policy will lapse, and you will lose the coverage and the premiums paid.
- Ignoring the Loan Interest: While you can borrow from your cash value, Allianz charges interest on those loans. If the loan balance plus interest exceeds the cash value, the policy could terminate, potentially triggering a significant tax bill.
FAQ
Is Allianz whole life insurance available in the USA?
In the United States, Allianz Life primarily focuses on Indexed Universal Life (IUL) rather than traditional Whole Life. US residents looking for permanent coverage with Allianz typically choose the Allianz Life Pro+ IUL, which offers similar permanent benefits but with different growth mechanics. Traditional whole life is more common in Allianz’s international divisions.
How does the cash value grow in an Allianz whole life policy?
The cash value grows through a combination of a guaranteed interest rate and potential dividends. The guaranteed rate is locked in at the time of purchase. If the policy is a participating policy, Allianz may credit dividends to the cash value based on the company's annual financial performance.
Can I withdraw money from my Allianz policy?
Yes, you can access your cash value through policy loans or partial surrenders. Loans are generally tax-free as long as the policy remains in force. However, any outstanding loans will reduce the death benefit paid to your beneficiaries.
What happens if I can no longer afford the premiums?
If your policy has accumulated enough cash value, you may be able to use "Automatic Premium Loans," where the cash value pays the premium for you. Alternatively, you can convert the policy to "Reduced Paid-Up" status, which stops all future premiums but keeps a smaller death benefit in place for life.
How do Allianz's financial ratings affect my policy?
Financial ratings from agencies like A.M. Best and S&P measure the company's ability to pay claims. Since whole life insurance is a multi-decade commitment, Allianz’s consistently high ratings (A+ or AA range) suggest they have the capital reserves necessary to honor your death benefit and cash value guarantees.
Final Recommendation
If you are seeking a predictable, guaranteed financial instrument that provides both a legacy for your heirs and a liquid asset for yourself, Allianz whole life insurance is a premier choice in the global market. While US-based consumers should look closely at Allianz’s IUL offerings as a functional alternative, international clients can leverage the traditional whole life structure for maximum stability.
Before committing, request a formal Illustration from an Allianz representative. This document will show you exactly how the death benefit and cash value are projected to grow over the next 50 years based on your age and health. Compare this to your long-term goals to ensure that the fixed-premium structure of whole life aligns with your 2026 financial plan.
Image Gallery
Select an image to open it in a new tab.
Mateo Castillo
Decentralized Finance and E-Payments Strategist
